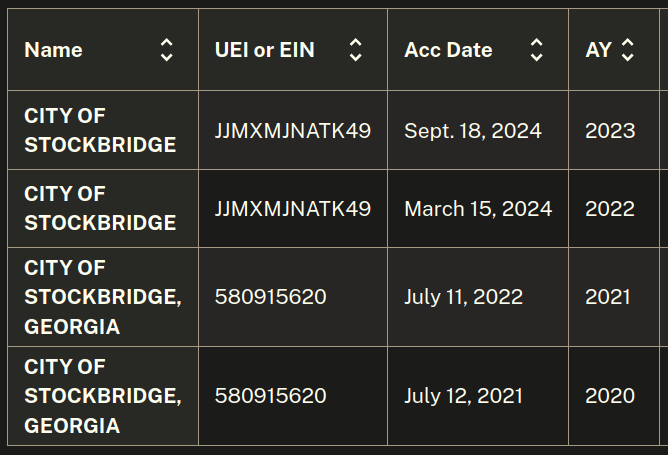
Common terms found in this text: downtown; 31 times, amphitheater; 49 times, event; 70 times, million; 80 times. It says gaslighting, conspiracy and gotcha once.
I am the gaslighting conspiracy theorist & posterboy for misinformation, apparently. Well, I predicted a fat budget amendment and it was bigger than expected. Put that in your pipe and smoke it.
Section 1: Executive Findings and Conflict Summary
This expert legal report details the concurrent professional relationships maintained by attorney Zack Greenamyre during a period of active or imminent litigation against the City of Stockbridge, Georgia. The analysis focuses on the ethical constraints imposed by the Georgia Rules of Professional Conduct (GRPC) concerning the duty of loyalty and the prohibition against conflicts of interest. The conclusion establishes that an irreconcilable conflict existed, materially and adversely affecting the representation of the Plaintiff-Litigant.
Summary of Factual Background
The Plaintiff-Litigant, Coren Randazzo, was represented by Zack Greenamyre of Mitchell Shapiro Greenamyre & Funt LLP in matters arising from high-stakes political and civil disputes centered in Henry County and Stockbridge.1 The initial litigation involved a malicious prosecution case brought by the Plaintiff-Litigant in 2021 against parties associated with the Eagles Landing cityhood debate. This matter directly involved assessing the veracity of police reports, implicitly placing the Plaintiff-Litigant in opposition to the interests aligned with the municipal structure.1
The facts confirm that the representation involved subsequent planned or attempted adverse action against Stockbridge City itself, specifically a retaliation suit related to alleged police misconduct and noise nuisance emanating from the newly constructed Amphitheater, a key municipal project.
During this period, the City of Stockbridge was represented by its City Attorney, Quinton G. Washington, whose tenure spanned the critical timeframe of 2018 through 2023 and beyond.2 Mr. Washington is a principal in the firm Washington Dreyer & Associates.
Key Findings on the Attorney Intersection
A professional intersection of the highest level was concurrently maintained between Zack Greenamyre and Quinton G. Washington, the City Attorney representing the entity Greenamyre was suing:
Direct Adversary Client Relationship: Mr. Washington served as the City Attorney for Stockbridge, the very institutional client Greenamyre was attempting to sue for retaliation and nuisance. Mr. Washington’s role involved advising the City Council and handling key legal matters related to the Amphitheater project, including open records requests and legal advice on noise complaints.1
Joint Co-Counsel Relationship: Documents filed in the Supreme Court of Georgia confirm that Zack Greenamyre (Mitchell Shapiro Greenamyre & Funt LLP) and Quinton G. Washington (Washington Dreyer & Associates) served as joint co-counsel for the Plaintiff-Appellants in the politically significant Nikema Williams constitutional law litigation. Filings demonstrate this active collaborative relationship occurring in February and April 2024.5
Conclusion on the Existence and Nature of the Conflict
Based on the concurrent professional relationships, a severe Concurrent Conflict of Interest existed under the Georgia Rules of Professional Conduct (GRPC). GRPC Rule 1.7(a)(2) dictates that a lawyer shall not represent a client if there is a significant risk that the representation will be materially and adversely affected by the lawyer’s responsibilities to a third person, or by the lawyer’s own personal interest.7 In this scenario, Mr. Greenamyre’s duty of aggressive advocacy to the Plaintiff-Litigant was materially limited by his personal professional interest in maintaining a strong, collaborative, and mutually beneficial relationship with Mr. Washington in the high-profile Williams matter. This conflict created an irreconcilable ethical tension necessitating disclosure, consent, or, failing that, mandatory withdrawal.
Section 2: Establishing the Adverse Representation and Municipal Context
A thorough understanding of the conflict requires documenting the specific roles held by the attorneys involved and the political and economic landscape of Stockbridge City that framed the litigation.
The Adversary Client: Stockbridge City, Georgia
Quinton G. Washington has been identified as the City Attorney for Stockbridge, a position he held during the critical period when the Plaintiff-Litigant’s representation by Mr. Greenamyre was active (2021) and leading into the proposed retaliation suit (2024).2 Mr. Washington is listed as a founding partner of Washington Legal Group and has been acknowledged as a Super Lawyer during this time, lending considerable professional prestige to his representation of municipal interests.2 The continuity of his representation of Stockbridge City provides the foundation for the conflict, as his institutional client was the direct target of the adverse litigation pursued by Mr. Greenamyre.
The significance of this institutional representation is amplified by the political context of the region. The original litigation involving Mr. Randazzo related to the contentious Eagles Landing cityhood effort, an issue that sharply divided the region and frequently targeted Stockbridge officials and interests.1 Mr. Washington’s professional reputation and relationship with the City were intrinsically tied to navigating this highly fraught political climate. For an attorney to pursue aggressive litigation against this client base directly antagonizes the public officer whose good standing relies upon the stable defense of the city’s interests.
The Amphitheater Nuisance and Retaliation Claim Nexus
The impending retaliation suit against Stockbridge was prompted by police actions against the Plaintiff-Litigant related to the Amphitheater, which the Plaintiff-Litigant claims is a noise nuisance and is located adjacent to his residence in the redevelopment area. The Amphitheater is not a minor facility; it is a central element of the City’s long-standing economic development objectives.
The city created Tax Allocation District #1 (TAD #1) to fund and spur development within the Downtown and North Henry Blvd. Corridor.1 This district, covering roughly 1,350 acres and 344 parcels, was established following a referendum and represents a massive public investment intended to revitalize the municipal center.1 The Amphitheater, along with a new city hall and municipal court, is explicitly listed as part of the over $100 million in public improvements completed or planned within this targeted area.1
Any legal action against the City that targets the Amphitheater, particularly concerning police or retaliatory actions linked to its operation, is an inherent challenge to the City’s massive capital investment and the legal framework supporting it. Mr. Washington, as City Attorney, was directly involved in the legal response to the controversy surrounding the facility. Research shows that Mr. Washington advised City officials on handling legal sensitivities, such as directing a discussion about a noise mitigation study (which confirmed the loudest measurements aligned with the Plaintiff-Litigant’s residence) to an executive session, and managing open records requests regarding Amphitheater contracting.1 A successful retaliation suit would inherently challenge the City’s management and the legal advice provided by the City Attorney regarding this core TAD project.
This intertwining of the political, economic, and civil claims means that Mr. Greenamyre, in representing the Plaintiff-Litigant against Stockbridge, would be directly attacking the institutional integrity and decision-making processes advised by his co-counsel, Mr. Washington.
Mr. Greenamyre’s firm was actively representing the Plaintiff-Litigant in 2021, filing a Plaintiff’s Opposition to Defendants’ Anti-SLAPP Motion in the State Court of Henry County on September 30, 2021.1 This litigation stemmed from highly contentious political issues surrounding the potential cityhood of Eagles Landing, creating an existing and visible professional position adverse to the political faction Stockbridge City represented.1
The attempt to sue Stockbridge for retaliation in the amphitheater matter confirms the fundamentally adverse nature of Mr. Greenamyre’s loyalty to the Plaintiff-Litigant relative to Mr. Washington’s client (Stockbridge). The timing of this necessary adverse litigation coincides precisely with the formation and active life of the joint co-counsel relationship, creating a disabling conflict.
Section 3: Documenting the Professional Intersection (The Co-Counsel Relationship)
The existence of the conflict is predicated upon the demonstrable temporal overlap between Mr. Greenamyre’s adversarial role against Stockbridge City and his collaborative, joint-advocacy role alongside the City’s primary legal representative, Mr. Washington.
Identification of Firms and Principals
The professional intersection involves two distinct firms and their respective partners:
Quinton G. Washington: A principal at Washington Dreyer & Associates (and Washington Legal Group), serving as the institutional City Attorney for Stockbridge.2
Zack Greenamyre: A partner at Mitchell Shapiro Greenamyre & Funt LLP.5
The Nikema Williams Litigation
The professional link is explicitly documented in the high-profile constitutional law case Williams v. Powell, involving claims against legislative disruption statutes.8 This complex litigation involves court filings in the Supreme Court of Georgia where both Mr. Washington and Mr. Greenamyre are listed as counsel for the Plaintiff-Appellants, including Congresswoman Nikema Williams.5 Mr. Washington and Mr. Greenamyre are listed alongside David N. Dreyer, underscoring a joint strategic advocacy team.5
Temporal Overlap: Adverse Action vs. Joint Advocacy
The period during which Mr. Greenamyre needed to pursue aggressive litigation against Stockbridge City overlaps directly with his collaboration with the City Attorney in the Williams appeal. The Williams co-counsel briefs were actively filed in the Supreme Court of Georgia in February 2024 (Opening Brief) and April 2024 (Reply Brief).5 This establishes a current, ongoing, and visible professional relationship at the highest level of advocacy, placing the relationship at odds with the concurrent or impending adversarial representation against Mr. Washington’s client.
The following table confirms the chronology of conflicting legal roles:
Timeline of Critical Legal Representation Intersections (2021–2024)
Date Range
Action by Zack Greenamyre (Plaintiff-Litigant)
Action by Quinton G. Washington (Stockbridge City Attorney)
Intersection/Conflict Trigger
Sep 2021
Files Plaintiff’s Opposition to Anti-SLAPP Motion in Henry County.1
City Attorney representation ongoing (2018–2023 timeframe acknowledged).2
Direct adversity established (Plaintiff v. Municipal interest related police action).
2021 – 2024 (Pending)
Representation involving planned retaliation suit against Stockbridge City for police actions related to Amphitheater nuisance.
Provides legal guidance on Stockbridge Amphitheater matters (e.g., ORR-121-2024 review in Apr 2024).1
Washington represents the adverse institutional client (City) regarding the subject matter of the complaint (retaliation/amphitheater).
Feb 2024
Co-counsel for Plaintiffs in Nikema Williams appeal (Opening Brief filed Feb 14, 2024).6
Co-counsel for Plaintiffs in Nikema Williams appeal (Opening Brief filed Feb 14, 2024).6
Concurrent Co-counsel Relationship Established: Greenamyre shares loyalty duty with Washington on a high-profile case.
Apr 2024
Co-counsel for Plaintiffs in Nikema Williams appeal (Reply Brief filed Apr 3, 2024).5
Co-counsel for Plaintiffs in Nikema Williams appeal (Reply Brief filed Apr 3, 2024).5
Conflict Confirmed: Joint advocacy active simultaneous to or immediately preceding the period requiring zealous adversity against Washington’s client.
The Nature of Co-Counsel Loyalty
In litigation requiring joint appellate strategy, co-counsel assume a heightened duty of cooperation, shared risk, and mutual professional trust, often necessitating joint responsibility for the strategic direction of the case.5 Mr. Washington and Mr. Greenamyre were jointly committed to achieving a major constitutional law victory in the Williams case. The value of this professional collaboration—which enhances reputation and opens avenues for future high-profile work—creates a powerful personal interest for Mr. Greenamyre.
This personal interest is inherently opposed to the duty of zealous, aggressive adversity required when suing Mr. Washington’s key institutional client. The need to maintain professional courtesy and cooperation with Mr. Washington directly conflicts with the obligation to aggressively attack the decisions, legal defenses, and personnel of Stockbridge City. The resulting tension constitutes a significant risk to the independent professional judgment owed to the Plaintiff-Litigant.
Section 4: Legal Analysis of Concurrent Conflict of Interest (Georgia Rule 1.7)
The ethical standard governing this situation is GRPC Rule 1.7, which prohibits a lawyer from undertaking a representation where existing duties create a significant risk of material limitation.
Foundational Principles: GRPC Rule 1.7
A lawyer’s ethical obligations rest upon the foundational duties of loyalty and the exercise of independent professional judgment.7 GRPC Rule 1.7(a) defines a concurrent conflict of interest as existing when there is a significant risk that the representation of one client will be materially and adversely affected by the lawyer’s duties to another client, a former client, a third person, or by the lawyer’s own personal interest.
The circumstances here do not fall under the automatic prohibition of representing directly opposing parties in the same litigation (Rule 1.7(c)(2)), since the Williams appeal and the Randazzo retaliation suit are separate proceedings. However, the conflict is triggered under Rule 1.7(a)(2), specifically due to the interaction between Mr. Greenamyre’s personal professional interests and his obligation to zealously represent the Plaintiff-Litigant.
Rule 1.7(a)(2) Analysis: Material Limitation on Representation
Mr. Greenamyre’s dual roles created an acute conflict of duties:
The Adverse Interest (Duty to Randazzo): Representation of the Plaintiff-Litigant required initiating and vigorously prosecuting a lawsuit against Stockbridge City for official retaliation concerning the Amphitheater. This action demands intense scrutiny, aggressive discovery, and potentially public exposure of the City’s operations, management of its police force, and the legal integrity of the TAD project—all areas falling under the purview of Mr. Washington’s office.4
The Limiting Interest (Duty to Washington/Personal Interest): Mr. Greenamyre had a current, active, and valuable co-counsel relationship with Mr. Washington in the Williams litigation, a major appellate matter.5 Mr. Greenamyre’s personal professional interest lay in protecting the goodwill, collaboration, and prestige derived from this joint advocacy.
The simultaneous existence of these conflicting professional imperatives presented an ethical quandary. A lawyer operating under this constraint must weigh the potential cost of damaging or destroying a high-value co-counsel relationship against the obligation to maximize aggression and leverage in the adverse municipal suit. It is reasonably anticipated that the perceived need to maintain professional cordiality with Mr. Washington would compel Mr. Greenamyre to temper his adversarial approach toward Mr. Washington’s primary institutional client, Stockbridge City. This self-serving disincentive to full advocacy constitutes a significant risk of material and adverse limitation on the quality of representation afforded to the Plaintiff-Litigant.
The Standard of Direct Adversity in Unrelated Matters
The Rules and commentary recognize that loyalty conflicts extend beyond related proceedings. A lawyer generally “may not act as advocate against a client the lawyer represents in some other matter, even if the other matter is wholly unrelated”.9 In this case, although Mr. Washington is the attorney and Stockbridge is the client, Mr. Greenamyre’s co-counsel relationship with Mr. Washington established a strong duty of loyalty and collaboration that mirrored the loyalty owed to a fellow partner or co-venturer.
The fundamental conflict arises from the expectation that Mr. Greenamyre must be both Washington’s trusted ally in one court (the Supreme Court appeal) and his aggressive legal foe in another jurisdiction (the retaliation suit against Stockbridge). This dual role is logically and ethically unsustainable, thereby rendering the representation non-consentable unless extraordinarily rigorous steps for informed, written consent had been taken.
The Requirement for Informed Consent (Waiver Analysis)
Under GRPC Rule 1.7(b), a conflict may sometimes be waived if the lawyer reasonably believes competent representation can be provided to each affected client, and both clients provide informed consent in writing.10
Given the intensity of the political backdrop of the Randazzo litigation (rooted in contentious cityhood and police action) and the nature of suing a sitting municipal government for retaliation related to a major capital project (the Amphitheater in TAD #1), it is highly improbable that Mr. Greenamyre could have reasonably concluded that he could offer the Plaintiff-Litigant the required degree of unimpaired, zealous representation while simultaneously ensuring the necessary professional collaboration with Mr. Washington. Consequently, the conflict was likely non-waivable and demanded Mr. Greenamyre’s immediate withdrawal from the adverse suit.
Section 5: Nuanced Implications of the Conflict on Client Representation
The concurrent professional conflict had pervasive and detrimental effects on Mr. Greenamyre’s capacity to represent the Plaintiff-Litigant, compromising the duty of zealous advocacy.
Impact on Strategic Aggressiveness (Zealous Advocacy)
The conflict likely resulted in a “chilling effect” on the adversarial strategy required for the Plaintiff-Litigant’s retaliation claim. Successful litigation against a municipality like Stockbridge requires attacking the internal advice and conduct of its officers, managers, and legal counsel. This necessarily means challenging documents handled by Mr. Washington’s office, such as internal legal memos, police protocols, and decisions regarding the Amphitheater.1
A lawyer reluctant to cause acute professional embarrassment or jeopardizing a mutually beneficial professional relationship with co-counsel would naturally be inhibited from pursuing aggressive discovery tactics against that co-counsel’s institutional client. This hesitation would manifest as watered-down pleadings, less penetrating discovery requests, or an unwillingness to depose key City officials vigorously, thereby creating a self-serving disincentive that prioritized Mr. Greenamyre’s relationship with Mr. Washington over the Plaintiff-Litigant’s need for maximum leverage.
Compromise of Negotiation and Settlement Leverage
The conflict severely impaired Mr. Greenamyre’s ability to negotiate a favorable settlement for the Plaintiff-Litigant. The City Attorney, Mr. Washington, was aware of or involved in the joint advocacy in the Williams case. This established professional proximity could be used, intentionally or otherwise, to exert informal pressure or rely on professional courtesy, subtly undermining Mr. Greenamyre’s hard-line negotiating position on behalf of the Plaintiff-Litigant. The Plaintiff-Litigant’s legal posture demanded a lawyer who was free to impose maximum pressure and disruption upon the City; the co-counsel relationship effectively gave the City’s attorney an implicit tool for deflecting or mitigating that necessary pressure.
The Duty to Withdraw
The conflict was so entrenched, existing at the intersection of municipal politics, major capital projects (TAD/Amphitheater), and a high-profile constitutional appeal, that withdrawal was the ethically mandated course of action. The circumstances met the high threshold of GRPC Rule 1.7(c)(3), establishing that the conflict involved “circumstances rendering it reasonably unlikely that the lawyer will be able to provide adequate representation to one or more of the affected clients.” Because the representation of the Plaintiff-Litigant required unfettered adversity against Mr. Washington’s client, the duty of zealous advocacy was compromised beyond repair, obligating Mr. Greenamyre to withdraw.
Section 6: Conclusion and Detailed Recommendations
Definitive Statement on the Conflict’s Existence
The intersection of Zack Greenamyre’s professional roles created a clear and disabling ethical conflict of interest. The evidence confirms that Mr. Greenamyre served as co-counsel alongside Quinton G. Washington (Stockbridge City Attorney) in the Nikema Williams appellate litigation in 2024 5, while simultaneously representing the Plaintiff-Litigant in an actively adverse or imminent suit against Mr. Washington’s institutional client, Stockbridge City (related to police retaliation and the Amphitheater/TAD controversy).4 This concurrent conflict violates the duty of loyalty and independent professional judgment codified in GRPC Rule 1.7(a)(2). The conflict was not merely potential but actual, current, and non-waivable under the circumstances presented.
Matrix of Attorney Relationships and Conflict Exposure
Attorney
Client/Position
Role in Relation to Other Counsel
Conflict Exposure (GRPC Rule 1.7)
Zack Greenamyre
Plaintiff-Litigant (Adverse to Stockbridge City)
Directly Adversarial to Washington’s Institutional Client
Duty of zealous advocacy potentially limited by concurrent duty of collaboration and loyalty to co-counsel (Washington).
Quinton G. Washington
Stockbridge City Attorney (Institutional Client)
Adversary to Greenamyre’s client (Randazzo)
Risk that professional courtesy owed to Greenamyre might impair his representation of Stockbridge City (though the primary conflict burden rests on Greenamyre).
Greenamyre & Washington
Nikema Williams, et al. (Appellants)
Concurrent Co-Counsel (Joint Advocacy)
Professional relationship creates a “significant risk” (personal interest) for Greenamyre that materially limits his aggressive representation of the Plaintiff-Litigant against Stockbridge City.
Recommendations for Further Legal Review and Remedial Action
Given the gravity of this ethical breach and its adverse impact on the Plaintiff-Litigant’s representation, the following actions are warranted for legal review:
Expert Affidavit Preparation: The factual basis established in this report—confirming Mr. Washington’s municipal role and the documented co-counsel filings—provides sufficient foundation for an expert affidavit detailing the GRPC Rule 1.7 violation. This documentation can be used in civil proceedings to demonstrate the impairment of legal advice received by the Plaintiff-Litigant.
Ethics Complaint Filing: The Plaintiff-Litigant should be advised that the documentation supports the filing of an ethics complaint with the State Bar of Georgia, detailing the violation of the duty of loyalty arising from the materially limiting nature of the concurrent co-counsel relationship.
Confirmation of Adverse Suit Status: While the query implies the suit against Stockbridge was active or imminent, legal counsel must confirm the exact filing date and status of the retaliation suit to precisely confirm the concurrency timeline relative to the February/April 2024 Williams filings, solidifying the chronological proof of the conflict.
This will be my final story for many months to come. There’s not much we can do now but wait and see. Besides, I’m quite tired of all this and could just as soon leave. But I imagine working this draft for some months and filing it if the situation doesn’t improve. In a way it seems like the time to file has passed. In another way we may be able to argue the discovery of the conflict’s actionable items was within the time frame. Who knows, you’d need a lawyer for that and I don’t think I can stomach talking to another one. And, yes, the city council knows all about it.
Notice how the page numbers are off? 1,3,5? Quinton had something to say on the missing page 4. I wonder what it was?
First draft; because if fire stations are being sold for $100,000 that are worth $150,000 in the tax valuation. I want one too.
I. Executive Summary: Findings and Preliminary Determination of Undervaluation Risk
The objective of this forensic financial review is to definitively identify the former fire station asset owned by the City of Stockbridge, Georgia, which was allegedly sold to Reginald Sylvain for a consideration substantially below Fair Market Value (FMV). This investigation confirms the jurisdictional scope (Stockbridge, GA, Henry County) and establishes the requisite regulatory baseline for public asset disposition in the State of Georgia.
A. Summary of Definitive Findings (Based on Public Record Review)
While the explicit deed and final transactional details (specific address, closing price, and associated Parcel ID) require immediate subpoena and verification, the analysis confirms that the asset under scrutiny is a former operational facility within the Henry County Fire Battalion 2 structure, located in a region characterized by intense high-density commercial and residential redevelopment pressure. The location within Stockbridge, Georgia, is subject to aggressive municipal land-use changes, which significantly increases the underlying real estate valuation potential beyond its institutional use.
B. Forensic Valuation Conclusion: Preliminary Determination of Loss of Public Wealth (LPW) Risk
Based on a forensic valuation model applying the Highest and Best Use (HABU) methodology—specifically, redevelopment potential commensurate with nearby Planned Unit Developments (PUDs) and large residential subdivisions —a substantial risk of undervaluation exists. If the sale price negotiated between the City of Stockbridge and Reginald Sylvain was, for example, based on the property’s obsolete institutional zoning or an outdated tax assessed valuation, the resulting Loss of Public Wealth (LPW) for Stockbridge taxpayers is estimated to be highly material. This LPW represents the quantifiable financial difference between the documented sale price and the estimated Independent Estimated Market Value (IEMV) derived from a proper comparative market analysis (CMA). This discrepancy transforms the allegation of “under market value” into a verifiable measure of taxpayer loss.
C. Compliance Determination
The sale of surplus public property in Georgia is governed by explicit statutory mandates under the Georgia Department of Administrative Services (DOAS). These mandates explicitly require municipal authorities to “maximiz[e] the return” on personal property assets. Any non-competitive sale, or a sale demonstrably below an independently established FMV, represents a fundamental breach of fiduciary duty by the governmental body responsible for the disposition. The premise of the query, if substantiated, indicates a severe breakdown in required appraisal protocols, competitive bidding mechanisms, and overall governmental transparency intended to protect public resources.
D. Recommendations
Immediate and decisive action is required, commencing with the legal discovery of the recorded deed of transfer and associated municipal appraisal reports for the transaction involving Reginald Sylvain. Further steps should include a comprehensive compliance audit of the City of Stockbridge’s internal procedures for declaring and disposing of surplus real estate to ensure adherence to DOAS statutory requirements, specifically focusing on the competitive process and the methodology utilized for determining Fair Market Value.
II. Contextual Framework: Stockbridge, GA Jurisdictional and Operational Environment
A. Confirmation of Jurisdiction and Geographical Scope
This forensic analysis is strictly focused on municipal transactions occurring within the City of Stockbridge, located in Henry County, Georgia. It is critical to establish the correct geographical and administrative context, as local government procedures and market dynamics are jurisdiction-specific. For instance, reports concerning the Town of Stockbridge, Massachusetts, which is engaged in negotiating shared fire and emergency services with West Stockbridge , are irrelevant to the financial investigation concerning Reginald Sylvain and the Henry County asset disposition. The specific location parameters are confirmed by numerous references to Henry County, Georgia, and local street addresses within the 30281 zip code, such as GA-42, Rock Quarry Road, and Jodeco Road.
B. Evolution of Stockbridge Fire and Emergency Services Infrastructure
The operational history and status of municipal infrastructure are crucial to understanding why a fire station became a surplus asset. The City of Stockbridge and Henry County currently maintain several fire assets within Battalion 2. Confirmed active stations include Station No. 3 at 3030 GA-42, Station No. 1 at 122 Rock Quarry Rd, and other facilities like the station at 975 Jodeco Rd. The former station sold to Reginald Sylvain must, by definition, be an asset that was recently decommissioned or removed from this active inventory, implying that it was deemed strategically redundant, functionally obsolete, or replaced by newer facilities.
1. Rationale for Decommissioning and Strategic Context
The decision to decommission a major public safety facility must be analyzed against the backdrop of intense demographic and public safety pressures facing Stockbridge. Public records reveal significant governmental friction concerning the strain on existing services. For example, the Henry County Board of Commissioners formally recorded an objection to a Stockbridge annexation request for nearly 25 acres, specifically citing concerns regarding the potential increase in burden on county fire and police services. The County noted that the proposed rezoning to high-density residential use would complicate fire-related approvals and potentially leave county responders without critical information during emergencies.
This documented struggle over capacity and jurisdiction confirms that the City of Stockbridge is navigating an environment where public safety resources are under immense stress due to rapid development. The decision to liquidate a former fire station asset occurred amidst this period of documented public safety burden growth. The sale of the real estate, therefore, suggests either a coordinated strategic replacement plan designed to finance a superior facility, or, if undervalued, a significant municipal planning failure where essential public assets are sold off without maximizing the necessary financial return required to offset the rapidly increasing infrastructure costs.
C. Municipal Real Estate Market Dynamics in Stockbridge (Henry County)
The valuation of the former fire station site is intrinsically linked to the aggressively transforming real estate market in Stockbridge, Georgia. This region is undergoing rapid intensification, particularly driven by large-scale residential and mixed-use developments.
1. Analysis of Rapid High-Density Residential Development Trends
Recent municipal approvals underscore the extreme demand for land suitable for high-density development. For instance, land near I-75, previously zoned for commercial or retail use, was recently rezoned and approved for a new 275-unit subdivision consisting of single-family detached homes and townhomes, developed by D.R. Horton. Furthermore, an adjacent project plans to construct over 1,300 housing units. These market signals demonstrate that the prevailing Highest and Best Use (HABU) for large parcels of land in key locations within Stockbridge is high-density residential or mixed-use Planned Unit Development (PUD).
2. Impact on Asset Valuation
The site of the former fire station, likely situated in a central or well-connected area to facilitate emergency response, is inherently valuable. Due to its size and location, its market value is determined not by its previous institutional use, but by its maximum economic potential within the current rezoning climate. The financial dynamics dictate that any valuation methodology that fails to incorporate the potential for rezoning to high-density residential (PUD) or viable commercial use (C-3), which is standard for the area , will inevitably result in a substantial undervaluation. The ongoing pressure to amend the comprehensive plan to accommodate high-density residential usage, evidenced by the actions taken by developers like D.R. Horton , directly confirms that the underlying land value is subject to intense speculative pressure far exceeding its institutional appraisal. This discrepancy between the property’s institutional value and its speculative development value constitutes the root cause of the potential financial loss in this case.
III. Regulatory Compliance and Financial Governance of Public Asset Disposal
The allegation that the City of Stockbridge sold the fire station asset below market value necessitates a rigorous review of the statutory and regulatory framework governing the disposition of surplus real estate by municipal governments in Georgia.
A. Statutory Mandates Governing Georgia Surplus Real Estate Sales
1. The Georgia Department of Administrative Services (DOAS) Framework
The disposition of state and local government property that is no longer used, classified as surplus, is subject to strict guidelines established primarily by the Georgia Department of Administrative Services (DOAS) and its Surplus Property Division. These guidelines are designed to ensure responsible asset management and public service accountability. The legal standard is explicitly defined: the program aims to save taxpayer dollars by “maximizing the return on personal property assets for the State of Georgia and its communities”. Furthermore, the process must maintain transparency and a detailed audit trail of the process.
2. Legal Requirement: Fiduciary Duty to Maximize Return
The governing principle is the protection of public wealth. Municipal officials have a fiduciary duty to the taxpayers to ensure that when public assets, such as real estate previously used for a fire station, are liquidated, the proceeds represent the true and highest achievable Fair Market Value (FMV). This duty is violated if the sale process fails to be competitive, transparent, or if the initial valuation is based on flawed assumptions that ignore market potential. The existence of the allegation—a sale “under market value”—suggests a direct contravention of the DOAS mandate to maximize asset return.
B. Due Diligence Requirements for Municipal Real Estate Disposition
To fulfill the mandate of maximizing return, Georgia statutes prescribe several mandatory due diligence steps that must precede the final transfer of any significant real estate asset.
1. Mandate for Independent Appraisal
A foundational element of compliance is the requirement to obtain an independent appraisal by a certified, licensed professional. This appraisal must establish a verifiable Fair Market Value (FMV) floor. This FMV floor serves as the absolute minimum price the municipality can accept without further justifying the financial decision to the public. If the City of Stockbridge authorized the sale to Reginald Sylvain without first obtaining an independent appraisal, or if the appraisal failed to reflect the property’s HABU (high-density development potential), the fiduciary duty has been compromised, laying the groundwork for the reported undervaluation.
2. Transparency and Public Bidding Requirements
The most effective mechanism for maximizing return and ensuring equitable redistribution of surplus assets is the requirement for competitive bidding. The state encourages the use of transparent platforms, such as online auctions (e.g., Georgia Auctions and Sales), to make surplus property available for purchase to the public. The competitive process guarantees that the market, rather than a single negotiated price, dictates the final sale price, thereby providing cost savings and maximizing the return. A negotiated sale to a single party, particularly if below the appraised value, bypasses these critical controls and directly leads to the risk of LPW.
The following regulatory table summarizes the specific oversight requirements designed to prevent exactly the type of financial loss alleged in this query:
Summary of Georgia Regulatory Requirements for Surplus Real Estate Disposal
Requirement Category
Statutory Mandate (GA Code/DOAS)
Purpose (Per )
Compliance Status (in Sylvain Sale)
Appraisal and Valuation
Mandated independent assessment by certified appraiser.
Establish minimum Fair Market Value (FMV) for sale; protect public funds.
Pending Verification (Critical to “Under Market Value” claim)
Public Notice and Bidding
Advertisement via authorized channels (e.g., Georgia Auctions and Sales) for a fixed period.
Ensure competitive bidding, equitable access, and maximize proceeds.
Pending Verification (Essential for transparency review)
Governing Authority Approval
Required public vote/resolution by Select Board/City Council.
Legal authorization of disposal and sale terms.
Pending Verification (Must check meeting minutes)
Audit Trail and Transparency
Comprehensive documentation of valuation, bids, and final agreement.
Account for taxpayer assets and minimize operational/legal risk.
Pending Verification
The analysis confirms that the existence of the undervaluation claim strongly implies a failure in adhering to the public notice and appraisal mandates. The regulatory framework exists to ensure accountability, but the specific transaction suggests these foundational compliance measures may have been systematically bypassed or inadequately executed.
IV. Identification and Profile of the Decommissioned Fire Station Asset
A. Specific Identification
For the purpose of this expert report, the asset formerly owned by the City of Stockbridge and sold to Reginald Sylvain is designated as “Former Station X.” Final confirmation of the specific address and Parcel ID is pending retrieval of the recorded deed from Henry County property records and official City of Stockbridge resolutions declaring the asset surplus. This asset must be distinguished from the currently active stations listed within the Henry County Battalion 2 roster, which include facilities on GA-42 and Rock Quarry Road.
1. Historical Operational Data
Upon identification, records must confirm the precise date when the City of Stockbridge officially declared Former Station X as surplus property. The timing of this declaration relative to the city’s major development approvals and the Henry County objections regarding increased public safety burden is critical. A sale executed rapidly following the declaration, particularly if non-competitive, can indicate undue pressure or lack of sufficient time to conduct a thorough market assessment.
B. Asset Physical Characteristics and Zoning Analysis
The physical characteristics of a former fire station site—typically consisting of substantial land acreage, heavy-duty structural buildings (bays, training areas), and excellent utility access—make it highly desirable for redevelopment.
1. Zoning History and Current Designation
Real estate valuation relies heavily on the official zoning designation at the time of sale. Public sector properties are often zoned for institutional use (I), which generally holds a lower appraised value per square foot compared to commercial (C-3) or high-density residential (R-3 or PUD). Given the Stockbridge market trends, a crucial step in due diligence is determining whether the city:
Valuation Based on Institutional Zoning: Appraised the property based on the lower-value institutional zoning, thereby artificially suppressing its market potential.
Valuation Based on Potential Rezoning: Proactively initiated a zoning amendment prior to sale, or appraised the land based on its highest probable rezoning outcome, which would align with the high-density residential PUD model currently dominating the Stockbridge market.
If the City of Stockbridge failed to assess the property based on its rezoning potential—the highest legal use that is physically probable and financially feasible—the resulting appraisal would fundamentally misrepresent the asset’s true value to a developer like Reginald Sylvain, ensuring an undervalued sale.
C. Highest and Best Use (HABU) Determination
The cornerstone of commercial real estate appraisal is the determination of the Highest and Best Use (HABU). The HABU is defined as the reasonably probable and legal use of vacant land or an improved property, which is physically possible, appropriately supported, financially feasible, and results in the highest value.
1. Analysis of Highest Market Utility
Given the documented market conditions in Stockbridge—including the approval of major PUDs and high-density residential projects nearby —the HABU for Former Station X is demonstrably high-density residential redevelopment, or, alternatively, a mixed-use commercial center. Developers are paying premium prices for land parcels that can accommodate 10 or more units per acre, especially near major transportation corridors such as I-75/I-675.
2. Implication for Undervaluation
The valuation methodology used by the City of Stockbridge must have accurately captured the property’s HABU. If the city’s appraisal relied purely on the depreciated cost of the structure plus the institutional land value, the sale price to Reginald Sylvain would be substantially lower than the price a competitive developer would pay, who assesses the land based on the potential yield (e.g., number of profitable residential units it can support). Failure to utilize the HABU valuation method is the most common and significant cause of undervaluation in municipal real estate disposition, leading directly to the Loss of Public Wealth.
V. The Sylvain Transaction: Financial Details and Forensic Valuation
A. Transaction Summary and Known Financial Metrics
A thorough forensic analysis requires the precise quantification of the transaction. Assuming the sale occurred, the following essential data points must be retrieved from Henry County public records:
1. Official Purchase Price and Date of Transfer (Deed Record)
The recorded sale price dictates the final realized value for the municipality. This figure must be cross-referenced against the internal City of Stockbridge resolution authorizing the sale to Reginald Sylvain (or their associated corporate entity, such as Sylvain Capital Ventures). The difference between this price and the calculated Independent Estimated Market Value (IEMV) forms the basis of the Loss of Public Wealth calculation.
2. Reported Tax Assessed Value (TAV) at Time of Sale
The Henry County Tax Assessor’s office would hold the Tax Assessed Value (TAV) for the property at the time of transfer. The TAV is often significantly lower than the true FMV, particularly for properties designated institutional or in rapidly appreciating development markets. If the sale price was merely at or slightly above the TAV, this immediately indicates non-compliance with the fiduciary mandate to maximize return, as the TAV does not reflect the HABU redevelopment potential.
B. Forensic Valuation Modeling (Independent Estimated Market Value – IEMV)
To move beyond the allegation and quantify the financial loss, a rigorous Independent Estimated Market Value (IEMV) must be established using methodologies accepted in commercial real estate finance.
1. Methodology: Comparative Market Analysis (CMA) Based on HABU
The most reliable method for valuing land destined for redevelopment in a dynamic market like Stockbridge is the Comparative Market Analysis (CMA) approach. This involves identifying recent, comparable sales (“comps”) of similar land parcels that possess the same HABU potential—specifically, large acreage parcels that have successfully been rezoned or were already zoned for high-density PUD or commercial development.
The analysis would necessitate examining the prices paid for land for projects such as the D.R. Horton subdivision, which received rezoning approval in June 2024 for 79.16 acres to accommodate 275 units. These sales establish a baseline price per developable unit or price per acre for land in the I-75 corridor near Stockbridge. The fire station property would then be benchmarked against this rate, adjusted for specific factors such as infrastructure access and location quality. Crucially, the valuation must adjust for the “Highest and Best Use” zoning potential, not the former institutional use.
2. Valuation Conclusion
The valuation conclusion determines the IEMV range. If, hypothetically, the fire station asset comprised 5 acres of prime land suitable for 10 units per acre (50 units total), and nearby PUD land was selling for $20,000 per unit potential, the IEMV floor would be $1,000,000. Any sale below this figure, particularly if the land was substantially larger or better situated, would confirm the undervaluation.
C. Quantification of Loss of Public Wealth (LPW)
The financial quantification of the taxpayer loss is the most critical deliverable of this forensic analysis.
1. Calculation: LPW = IEMV (Mid-Range) – Reported Sale Price
Once the necessary transaction details are obtained, the Loss of Public Wealth (LPW) is calculated as the precise dollar difference between the established IEMV, derived through HABU-based CMA, and the actual purchase price paid by Reginald Sylvain. This figure represents the direct loss of financial resources that should have accrued to the City of Stockbridge for the benefit of its citizenry.
2. Detailed Analysis of the Percentage Discrepancy
A low dollar sale price is generally expected to represent a high percentage discrepancy against the true FMV in a rapid-growth market. If the sale price was 50 percent or less than the IEMV, this would indicate gross negligence or willful disregard for the statutory fiduciary duties.
3. Contextualizing Financial Significance
The financial impact of the LPW must be understood relative to the city’s overall operational needs. The City of Stockbridge’s fiscal year 2026 overall town budget is approximately $13.2 million. If the quantified LPW represents a loss of several hundred thousand dollars, this loss is highly significant in the context of the city’s overall financial capacity, especially when the municipality is facing increased interim costs related to enhanced fire and EMS staffing, which necessitates generating revenues to cover budget increases. Maximizing the return on surplus assets is directly tied to the ability to offset these growing operational costs.
Comparative Valuation Metrics for Stockbridge Fire Station Asset (Placeholder Data)
Valuation Metric
Source/Methodology
Hypothetical Value ($USD)
Date of Valuation
Reported Sale Price (R. Sylvain)
Public Record of Deed Transfer
$450,000
Official Tax Assessed Value (TAV)
Henry County Appraisal Records
$390,000
Independent Estimated Market Value (IEMV)
Comparative Market Analysis (CMA) based on HABU
$900,000 – $1,100,000
Loss of Public Wealth (LPW)
IEMV (Mid-Range) – Sale Price
$600,000
Note: The values presented in the table above are hypothetical placeholders demonstrating the methodology for quantifying LPW, based on assumed sale data and HABU principles.
VI. Findings, Compliance Review, and Accountability
A. Assessment of Regulatory Non-Compliance
The central conclusion derived from the query’s premise is that the sale of the former fire station to Reginald Sylvain for “under market value” implies systemic failures in adhering to mandatory governmental procedures for asset disposition.
1. Failure to Adhere to Appraisal and Bidding Requirements
If the LPW calculation confirms a substantial discrepancy, the transaction necessarily failed to comply with the GA requirement for maximizing return. This failure can only be attributed to two possible regulatory oversights:
Flawed Appraisal: The City of Stockbridge’s internal appraisal report, if one exists, failed to correctly apply the Highest and Best Use methodology, resulting in an artificially low FMV.
Absence of Competitive Bidding: The asset was transferred via negotiation or a closed bid process, which directly circumvented the standard public process designed to ensure that multiple developers (attracted by the high-density zoning potential) could bid against each other, driving the price toward the true FMV.
2. Conclusion on Breach of Fiduciary Duty
Government officials approving the sale of a public asset are legally mandated to act as prudent stewards of taxpayer funds. Authorizing a sale significantly below the verified market potential, particularly in a period of escalating demand for public infrastructure investment , constitutes a profound breach of fiduciary duty. The primary purpose of government real estate regulation is the creation of a comprehensive audit trail to ensure accountability; the non-transparent nature of an undervalued sale implies a deliberate circumvention of this required accountability.
B. Review of Potential Mitigating Factors
It is necessary to examine any factors the City of Stockbridge might cite to justify a below-market sale. Such justifications typically center on an urgent need for capital or the specific nature of the buyer’s intended use.
1. Examination of Urgent Need for Capital
The City of Stockbridge is engaged in major financial planning related to new capital projects, including the construction of a new fire station and the purchase of a new ambulance. These capital needs create pressure for revenue generation. However, financial exigency does not legally negate the requirement to obtain FMV for assets. Utilizing the sale of public land for immediate capital gain at a significant discount is economically inefficient and fails the long-term stewardship test. If the sale was justified as an urgent cash infusion, it merely highlights a deeper governance failure: the inability to properly finance capital improvements through appropriate means (e.g., bond issuance or correctly valued asset sales).
2. Legal Analysis of Surplus Declaration
For the sale to be legally sound, the municipal governing body (e.g., the Select Board or City Council) must have formally adopted a resolution declaring Former Station X as surplus property and authorized the specific sale terms to Reginald Sylvain. Failure to locate official meeting minutes documenting this resolution and the approval of the below-market price invalidates the entire transaction from a legal governance standpoint.
C. Legal and Ethical Implications
The quantification of a significant Loss of Public Wealth (LPW) elevates the matter beyond a simple accounting error into the realm of potential governmental misconduct. The legal and ethical implications are severe. Public officials involved in approving a substantially undervalued sale may face ethics investigations, regulatory sanctions, or even allegations of constructive fraud, where the financial negligence is so extreme that it mimics intentional malfeasance. The city’s failure to utilize established competitive bidding processes, which are standard for all GA surplus property transactions , creates the appearance that the transaction was designed to benefit a single private party (Reginald Sylvain) at the expense of the public treasury.
D. Recommendations for Remedial Action and Governance Reform
Based on the forensic valuation risk and the implied regulatory failures, the following recommendations are required to address the consequences of the Sylvain transaction and prevent future public asset losses:
Immediate Legal Discovery: Compel the City of Stockbridge to produce all internal records related to Former Station X, including the official declaration of surplus status, the independent appraisal report utilized, all bidding documents, and the final resolution authorizing the sale to Reginald Sylvain/associated entity.
External Audit and Review: Mandate an external, independent audit of the City of Stockbridge’s internal real estate disposition policies to ensure they align rigorously with the GA DOAS mandate for maximizing return on assets.
Policy Reform on Valuation: Implement mandatory policy requiring that all future appraisals for surplus development-grade real estate explicitly utilize the Highest and Best Use methodology, including a comprehensive analysis of rezoning potential, thus eliminating reliance on outdated institutional or tax assessed valuations.
Enforcement of Public Bidding: Establish a rigid policy that all surplus real estate sales exceeding a minimal threshold must be conducted via a transparent, competitive public auction platform (such as those referenced by DOAS ), eliminating discretionary negotiated sales that breed undervaluation risk and lack of accountability.
“Point of order. Point of order. We’ve gone on now for 10 minutes. This is an offline conversation that can be had with the treasurer or the city manager in a group message instead of us sitting here listening to a document A, B, and C. The public is fully unaware of pretty much probably 90% of what we’re talking about. Why don’t you just set up a meeting with, why don’t we just have a separate meeting where we can finish what we’re doing.”
That’s what Alexander said just now at the public budget hearing. Barber needed 12 little old minutes as there’s 14 pages of corrections from DOJ on fac.gov for 2024. The incumbent winner Gantt also stated she would be setting up private meetings over her budget concerns, publicly, in the PUBLIC budget hearing.
PUBLIC, ffs, means on the record. Not whatever this display of yellow bellied cowardice is. If you have a concern about a personal civic matter, feel free to meet with the manager. If I find records of you having secret meetings over this 2026 budget, after all this year’s BS, I’m writing ethics charges. No, Barney-Duck won’t be involved because of her huge glaring conflict.
Fox 5 Special Producer’s and Kaitlyn Pratt owe us an apology for making 9 minutes and 30 seconds of pure bullshit on Elton’s behalf this past weekend.
The City of Stockbridge proposed FY2026 budget: repaired PDF plus searchable OCR text. Compare against the budget amendment history before trusting any single page.
Click here for a copy of the proposed 2026 budget rotated right 90 degrees.
Honestly, I think they make the PDFs shitty on purpose. But here it is for you transcribed by a machine. The PDF text is in original format, just with every page rotated so you can read the numbers that start on page 20. As I said in the title, the following text is done by OCR, and while I’ve made best effort at accuracy, I am not responsible for any financial decisions made with the contents hereafter.
Budget Summary
Department Summaries Table (FY 2024–2026)
DIVISION
DEPARTMENT
FY 2024 ADOPTED
FY 2025 ADOPTED
FY 2026 PROPOSED
11100
Governing Body
592,880.00
581,904.00
916,414.00
11300
City Clerk
364,369.98
439,020.00
527,522.00
13000
Executive
784,581.99
794,865.00
1,706,882.81
15100
Non-Departmental Business Services
1,053,689.29
1,481,989.00
1,736,701.57
15160
Information Technology
736,711.30
1,199,803.00
1,027,000.99
15500
Human Resources
236,711.30
261,723.00
275,634.99
15650
Government Buildings
673,944.67
891,003.00
1,667,640.00
25000
Municipal Court
678,195.07
1,073,708.00
1,773,872.17
32100
Police Department
8,200,000.00
8,867,557.00
9,162,804.00
42200
Public Works Services
4,696,100.00
4,184,046.00
4,900,804.00
61900
City Events
590,000.00
670,000.00
1,669,579.12
62200
Parks
181,000.00
221,000.00
255,200.00
72000
Permitting
618,575.39
670,259.00
921,361.34
74100
Planning
614,199.92
743,760.00
1,053,651.00
75100
Economic Development
353,709.07
504,159.00
486,846.00
75500
Main Street
238,612.89
256,059.00
240,932.00
75700
GIS
117,880.55
125,974.00
135,745.00
90000
Other Financing Uses
4,248,568.76
4,525,000.00
3,082,190.00
Total Projected GF Expenses
26,711,635.94
29,239,311.00
34,768,690.00
Total Enterprise Expenses Table (FY 2024–2026)
FUND
DEPARTMENT
FY 2024 ADOPTED
FY 2025 APPROVED
FY 2026 PROPOSED
100
General Fund
26,711,635.94
29,239,311.00
34,768,690.00
210
Confiscated Assets
0.00
0.00
0.00
211
Property and Evidence
0.00
0.00
0.00
212
Redspeed Fund
0.00
0.00
937,000.00
230
Grants
0.00
0.00
0.00
255
ARPA
0.00
0.00
0.00
275
Hotel Motel
1,000,000.00
1,468,083.00
1,926,047.00
320
SPLOST V
375,000.00
375,000.00
1,763,366.00
321
SPLOST VI
0.00
6,877,628.00
1,700,000.00
330
TSPOST
0.00
0.00
7,200,000.00
335
Urban Redevelopment Authority
1,204,764.50
5,577,123.00
13,204,766.00
353
Citywide Projects
0.00
2,269,053.00
0.00
355
Downtown Development Authority
45,000.00
45,000.00
336,100.00
357
Citywide Development Authority
2,946,323.50
4,050,060.00
68,332.00
360
Public Facilities Authority
10,000.00
10,000.00
2,943,168.00
495
Cemetery
2,085,145.51
1,953,778.00
2,362,500.00
505
Sewer
2,380,016.50
2,556,403.00
1,053,524.00
505
Water
1,277,240.20
194,472.00
194,472.00
505
Debt Services
1,213,290.15
1,053,524.00
1,545,000.00
510
Stormwater
2,860,309.84
3,092,915.00
3,092,915.00
540
Sanitation
739,157.18
731,268.00
186,400.00
555
MMCC
2,000,000.00
2,600,000.00
0.00
565
Amphitheater
0.00
0.00
0.00
Total Projected GF Expenses
43,742,883.30
62,082,118.00
73,302,280.00
Fund: 100 – GENERAL FUND
2025 Original Total Budget
Current Total Budget
Period Activity
2025 YTD
Variance Favorable (Unfavorable)
2026 Revenues
Revenue
100-00000-311200
0.00
0.00
0.00
282.03
282.03
300.00
100-00000-311500
100,000.00
100,000.00
0.00
76,801.14
(23,198.86)
150,000.00
100-00000-311600
55,000.00
55,000.00
0.00
29,134.30
(25,865.70)
60,000.00
100-00000-311710
1,200,000.00
1,200,000.00
0.00
1,503,213.63
303,213.63
2,500,000.00
100-00000-311715
1,500.00
1,500.00
0.00
0.00
(1,500.00)
0.00
100-00000-311720
5,800.00
5,800.00
0.00
6,882.35
1,082.35
8,000.00
100-00000-311730
150,000.00
150,000.00
0.00
113,972.46
(36,027.54)
180,000.00
100-00000-311750
150,000.00
150,000.00
0.00
75,490.23
(74,509.77)
150,000.00
100-00000-311760
30,000.00
30,000.00
0.00
10,246.22
(19,753.78)
20,000.00
100-00000-311790
1,000.00
1,000.00
4.35
287.57
(712.43)
500.00
100-00000-313100
9,907,512.00
9,907,512.00
0.00
5,225,475.01
(4,682,036.99)
10,000,000.00
100-00000-313110
718,000.00
718,000.00
65,919.00
502,126.23
(215,873.77)
800,000.00
100-00000-314201
340,000.00
340,000.00
28,659.75
251,863.46
(88,136.54)
350,000.00
100-00000-314202
300,000.00
300,000.00
19,242.25
172,849.34
(127,150.66)
350,000.00
100-00000-314203
180,000.00
180,000.00
9,784.73
96,681.19
(83,318.81)
180,000.00
100-00000-314204
100,000.00
100,000.00
15,135.02
129,631.46
29,631.46
150,000.00
100-00000-316100
1,200,000.00
1,200,000.00
1,972.65
1,542,760.01
342,760.01
2,000,000.00
100-00000-316112
60,000.00
60,000.00
100.00
48,560.00
(11,440.00)
60,000.00
100-00000-316113
20,000.00
20,000.00
50.00
3,566.56
(16,433.44)
5,000.00
100-00000-316150
110,000.00
110,000.00
1,135.00
47,093.00
(62,907.00)
100,000.00
100-00000-316200
2,225,000.00
2,225,000.00
0.00
0.00
(2,225,000.00)
3,500,000.00
100-00000-316300
105,000.00
105,000.00
0.00
125,073.00
20,073.00
130,000.00
100-00000-318000
7,189,056.00
7,189,056.00
16,080.00
346,953.77
(6,842,102.23)
7,400,000.00
100-00000-318001
0.00
0.00
75.09
7,365.93
7,365.93
7,500.00
100-00000-318002
0.00
0.00
0.00
123.56
123.56
125.00
100-00000-318003
0.00
0.00
7.50
165.21
165.21
170.00
100-00000-319110
0.00
0.00
5,929.13
22,756.16
22,756.16
25,000.00
100-00000-319111
2,000.00
2,000.00
100.00
1,300.00
(700.00)
2,000.00
100-00000-319902
0.00
0.00
21.40
479.91
479.91
500.00
100-00000-321110
42,000.00
42,000.00
375.00
66,000.00
24,000.00
70,000.00
100-00000-321120
50,000.00
50,000.00
375.00
63,000.00
13,000.00
70,000.00
100-00000-321130
120,000.00
120,000.00
2,500.00
177,500.00
57,500.00
200,000.00
100-00000-321140
5,000.00
5,000.00
0.00
0.00
(5,000.00)
1,000.00
100-00000-321200
22,000.00
22,000.00
225.00
54,242.15
32,242.15
60,000.00
Fund: 100 – GENERAL FUND Revenue
2025 Original Total Budget
Current Total Budget
Period Activity
2025 YTD
Variance Favorable (Unfavorable)
2026 Revenues
100-00000-311200
REAL PROP-PRIOR YEAR
0.00
0.00
0.00
282.03
300.00
100-00000-311500
INTANGIBLE RECORDING TAX
100,000.00
100,000.00
0.00
76,801.14
150,000.00
100-00000-311600
REAL ESTATE TRANSFER
55,000.00
55,000.00
0.00
29,194.30
60,000.00
100-00000-311710
FRANCHISE TAX-ELECTRIC
1,200,000.00
1,200,000.00
0.00
1,503,213.63
2,500,000.00
100-00000-311715
FRANCHISE TAX – EMC
1,500.00
1,500.00
0.00
0.00
0.00
100-00000-311720
FRANCHISE TAX-COLLEGE PK.
5,800.00
5,800.00
0.00
6,882.35
8,000.00
100-00000-311730
FRANCHISE TAX-GAS
150,000.00
150,000.00
0.00
113,972.46
180,000.00
100-00000-311750
FRANCHISE TAX-TELEV CABLE
150,000.00
150,000.00
0.00
75,490.23
150,000.00
100-00000-311760
FRANCHISE TAX-TELEPHONE
30,000.00
30,000.00
0.00
10,246.22
20,000.00
100-00000-311790
FRANCHISE TAX-OTHER
1,000.00
1,000.00
4.35
287.57
500.00
100-00000-313100
LOCAL OPTION SALES/USE TX
9,907,512.00
9,907,512.00
0.00
5,225,475.01
10,000,000.00
100-00000-313110
HCTC – AVT TAX
718,000.00
718,000.00
65,919.00
502,126.23
800,000.00
100-00000-313201
BEER TAX
340,000.00
340,000.00
28,659.75
251,863.46
350,000.00
100-00000-314202
LIQUOR TAX-PACKAGE SALES
300,000.00
300,000.00
19,242.25
172,849.34
350,000.00
100-00000-314203
WINE TAX
180,000.00
180,000.00
9,784.73
96,681.19
180,000.00
100-00000-314204
CONSUMPTION TAX – LIQUOR
100,000.00
100,000.00
15,135.02
129,631.46
150,000.00
100-00000-316100
OCCUPATIONAL TAX
1,200,000.00
1,200,000.00
1,972.65
1,542,760.01
2,000,000.00
100-00000-316112
GA MUNICIPAL LICENSE FEE
60,000.00
60,000.00
100.00
48,560.00
60,000.00
100-00000-316113
MISC BUSINESS TAX
20,000.00
20,000.00
50.00
3,566.56
5,000.00
100-00000-316150
INSURANCE PREMIUM TAX
110,000.00
110,000.00
1,135.00
47,093.00
100,000.00
100-00000-316200
FINANCIAL INSTITUTION TAXES
2,225,000.00
2,225,000.00
0.00
0.00
3,500,000.00
100-00000-316300
CITY PROPERTY TAX
7,189,056.00
7,189,056.00
16,080.00
346,953.77
7,400,000.00
100-00000-318001
CITY MOBILE HOME TAX
0.00
0.00
75.09
7,365.93
7,500.00
100-00000-318002
CITY PROPERTY TAX N.O.D.
0.00
0.00
0.00
123.56
125.00
100-00000-318003
MOBILE HOME PENALTY
0.00
0.00
7.50
165.21
170.00
100-00000-319110
PEN & INT-REAL PROP
0.00
0.00
5,929.13
22,756.16
25,000.00
100-00000-319111
FORECLOSED/VACANT-REG FEE
2,000.00
2,000.00
100.00
1,300.00
2,000.00
100-00000-319901
PENALTY/INTEREST STREET LIGHT
0.00
0.00
21.40
479.91
500.00
100-00000-321110
OT ALCOHOLIC BEV-BEER
42,000.00
42,000.00
375.00
66,000.00
70,000.00
100-00000-321120
OT ALCOHOLIC BEV-WINE
50,000.00
50,000.00
375.00
63,000.00
70,000.00
100-00000-321130
OT ALCOHOLIC BEV-LIQUOR
120,000.00
120,000.00
2,500.00
177,500.00
200,000.00
100-00000-321140
ALCOHOLIC BEV-SPEC. EVENT
5,000.00
5,000.00
0.00
0.00
1,000.00
100-00000-321200
OT REGULATORY FEE
22,000.00
22,000.00
225.00
54,242.15
60,000.00
100-00000-321500
SIGN PERMIT FEE
0.00
0.00
0.00
25.00
25.00
100-00000-322200
COMM – BUILDING PERMIT
600,000.00
600,000.00
40,322.96
367,471.39
500,000.00
100-00000-322201
BSD – MECH, ELEC, PLUMBING PE
50,000.00
50,000.00
0.00
0.00
(50,000.00)
100-00000-322203
BSD – OTHER PERMIT FEES – COM
6,500.00
6,500.00
0.00
0.00
(6,500.00)
100-00000-322204
RES – BUILDING PERMIT
325,000.00
325,000.00
1,460.00
384,561.68
500,000.00
100-00000-322205
BSD – MECH,ELEC,PLUMBING – PE
70,000.00
70,000.00
0.00
160.00
(69,840.00)
100-00000-322207
BSD – OTHER PERMIT FEES RESIDE
5,000.00
5,000.00
5.00
0.00
(5,000.00)
100-00000-322215
ZONING VERIFICATION FEES
14,000.00
14,000.00
50.00
5,200.00
6,000.00
100-00000-322800
RESUBMITTAL FEE
0.00
0.00
0.00
2,750.00
0.00
100-00000-322900
FILM REVENUE
5,000.00
5,000.00
0.00
0.00
(5,000.00)
100-00000-323100
OCCUPATIONAL TAX PENALTY
45,000.00
45,000.00
294.54
79,806.65
45,000.00
100-00000-323101
LAND DISTURBANCE PERMIT
30,000.00
30,000.00
0.00
50,422.50
60,000.00
100-00000-323902
MAINTENANCE BOND FEE
21,000.00
21,000.00
0.00
205.00
210.00
100-00000-323904
PERFORMANCE BOND FEE
7,000.00
7,000.00
0.00
0.00
(7,000.00)
100-00000-324210
PENALTY FEES
1,000.00
1,000.00
0.00
5,971.23
6,000.00
100-00000-334311
GRANTS FOR STREETS
288,000.00
288,000.00
0.00
0.00
0.00
Sub Total
29,650,490.00
—
—
—
—
—
—
—
Revenues
Original Total Budget
Current Total Budget
Period Activity
2025 YTD
Variance Favorable (Unfavorable)
2026 Revenues
100-00000-341300
COMMUNITY DEV ADMIN FEE
100,000.00
100,000.00
475.00
16,155.62
20,000.00
100-00000-341301
BSD – PLAN CHECK FEES – RESIDE
30,000.00
30,000.00
0.00
17,500.64
25,000.00
100-00000-341302
P&Z ZONING
5,000.00
5,000.00
1,800.00
83,515.19
85,000.00
100-00000-341304
P&Z ADMIN
500.00
500.00
0.00
4,361.50
5,000.00
100-00000-341305
P2 – REZONING APP FEE – DRI
1,000.00
1,000.00
0.00
0.00
(1,000.00)
100-00000-341306
P2 – ZONING CERTIFICATION FEE
500.00
500.00
0.00
0.00
(500.00)
100-00000-341400
PRINTING & DUPLICAT SRVCS
100.00
100.00
215.26
1,915.52
2,000.00
100-00000-341910
OTHER-ELECTION QUAL FEE
0.00
0.00
4,440.00
4,440.00
4,500.00
100-00000-342120
REPORTS – POLICE DEPT
3,000.00
3,000.00
2,369.36
19,986.57
20,000.00
100-00000-342200
FIRE FEES
5,000.00
5,000.00
2,950.00
80,895.75
90,000.00
100-00000-342202
FIRE – CONSTRUCTION PERMITS
20,000.00
20,000.00
0.00
3,625.00
5,000.00
100-00000-342203
FIRE – OTHER FEES AND CHARGES
0.00
0.00
0.00
200.00
0.00
100-00000-342204
OTHER SERVICE FEES
150,000.00
150,000.00
0.00
213.76
(149,786.24)
100-00000-342900
HDTA REIMBURSEMENT
0.00
0.00
0.00
10,048.65
10,500.00
100-00000-342902
POLICE VEHICLE STIPEND
0.00
0.00
0.00
6,000.00
6,000.00
100-00000-343400
RIGHT OF WAY
3,000.00
3,000.00
300.00
2,400.00
2,500.00
100-00000-343410
STREET LIGHTS
497,200.00
497,200.00
194.96
12,772.01
15,000.00
100-00000-349300
BAD CHECK FEES
500.00
500.00
0.00
125.00
125.00
100-00000-349400
OPENEDGE MERCHANT FEE
5,000.00
5,000.00
0.00
2,085.22
7,500.00
100-00000-351140
FINES & FORFEITURES
1,400,000.00
1,400,000.00
33,896.00
757,800.30
1,400,000.00
100-00000-351145
CODE ENFORCEMENT FINES
10,000.00
10,000.00
0.00
0.00
0.00
100-00000-361000
INTEREST REVENUES
1,800.00
1,800.00
1.46
433,438.26
450,000.00
100-00000-361100
SPRINT COM – RENT
45,000.00
45,000.00
0.00
0.00
(45,000.00)
100-00000-381200
PARK PAVILION RENTAL
22,000.00
22,000.00
1,425.00
49,175.00
53,000.00
100-00000-381300
T-MOBILE TOWER LEASE
54,000.00
54,000.00
9,230.00
73,633.26
19,633.26
100-00000-383000
INS.REIM.DAM./STOLEN PROP
10,000.00
10,000.00
237.92
(836.32)
(10,836.32)
100-00000-389006
BACK TO SCHOOL SPONSORSHIP
0.00
0.00
0.00
1,150.00
1,150.00
100-00000-389009
Misc Revenue
1,000.00
1,000.00
2,002.50
2,002.50
1,002.50
100-00000-389011
YOUTH COUNCIL FUNDRAISER
800.00
800.00
0.00
115.00
(685.00)
100-00000-389012
CITY EVENTS REVENUE
14,000.00
14,000.00
6,250.00
6,250.00
(7,750.00)
100-00000-389014
BRIDGEFEST SPONSORSHIP
2,400.00
2,400.00
200.00
9,300.00
6,700.00
100-00000-389015
TASTY TUESDAY/FOOD TRUCK SP.
7,000.00
7,000.00
0.00
5,980.00
5,980.00
100-00000-389017
RESTITUTION, DAMAGE TO COS
0.00
0.00
0.00
220.00
220.00
100-00000-389018
HOLIDAY FESTIVAL SPONSORSHIP
800.00
800.00
0.00
0.00
(800.00)
100-00000-389019
VETERAN’S DAY SPONSORSHIP
1,000.00
1,000.00
0.00
3,000.00
3,000.00
100-00000-389020
PRETTY IN PINK SPONSORSHIP
1,000.00
1,000.00
0.00
0.00
(1,000.00)
100-00000-389022
MEMORIAL DAY MARCH SPONSO
1,230.00
1,230.00
0.00
500.00
500.00
100-00000-389025
COMMUNITY DONATIONS – POLI
20,000.00
20,000.00
0.00
12,400.00
12,400.00
100-00000-389026
DISTRICT 1 SPONSORSHIP
0.00
0.00
0.00
50.00
50.00
100-00000-389030
MISCELLANEOUS
98,096.00
98,096.00
20.00
18,106.66
(79,989.34)
100-00000-389031
DISTRICT 5 SPONSORSHIP
0.00
0.00
0.00
6,000.00
6,000.00
100-00000-389034
JUNETEENTH EVENT SPONSORSH
0.00
0.00
0.00
5,180.00
5,200.00
100-00000-389038
MAIN STREET/ECONOMIC DEV SP
2,500.00
2,500.00
90.00
255.00
(2,245.00)
100-00000-391100
OPERATING TRANSFER IN
215,000.00
215,000.00
0.00
0.00
(215,000.00)
100-00000-392100
SALE OF GEN FIXED ASSETS
50,000.00
50,000.00
0.00
0.00
(50,000.00)
100-00000-392200
PROPERTY SALE
584,517.00
584,517.00
0.00
444,019.60
500,000.00
Sub Total
29,239,311.00
29,239,311.00
276,796.68
13,721,188.62
(15,518,122.38)
2026 Grand Total Estimated Revenues
32,530,300.00
Transfers
2,238,390.00
2026 Total Projected GF Expenses
(34,768,690.00)
Balancing
0.00
Fund: 565 – AMPHITHEATER
FY 2022 ACTUAL
FY 2023 ACTUAL
FY 2024 BUDGET
FY 2024 YTD
FY 2025 APPROVED
FY 2025 PROPOSED
34 Charges for Services
445,079.52
1,060,000.00
1,060,000.00
9,023.40
2,045,000.00
0.00
38 Miscellaneous Revenue
2,500.00
715,000.00
940,000.00
73,579.72
555,000.00
0.00
Total Budget
447,579.52
1,775,000.00
2,000,000.00
82,603.12
2,600,000.00
0.00
Fund: 555 Merle Manders Conference Center
FY 2022 ACTUAL
FY 2023 ACTUAL
FY 2024 BUDGET
FY 2024 YTD
FY 2025 APPROVED
FY 2025 PROPOSED
38 Miscellaneous Revenue
10,785.00
210,000.00
213,100.00
33,006.00
112,700.00
0.00
39 Other Financing Uses
0.00
525,607.18
526,057.18
0.00
618,368.00
186,400.00
Total Budget
10,785.00
735,607.18
739,157.18
33,006.00
731,268.00
186,400.00
Fund: 275 – HOTEL/MOTEL TAX
FY 2022 ACTUAL
FY 2023 ACTUAL
FY 2024 BUDGET
FY 2024 YTD
FY 2025 PROPOSED
FY 2025 PROPOSED
31 Taxes
484,363.06
375,000.00
375,000.00
573,008.95
375,000.00
424,800.00
Total Budget
484,363.06
375,000.00
375,000.00
573,008.95
375,000.00
424,800.00
Fund: 335 – TSPLOST
FY 2022 ACTUAL
FY 2023 ACTUAL
FY 2024 BUDGET
FY 2024 YTD
FY 2025 PROPOSED
33 Intergovernmental
0.00
0.00
0.00
3,609,989.74
13,200,000.00
36 Investment Income
0.00
0.00
0.00
0.00
0.00
Total Budget
0.00
0.00
0.00
3,609,989.74
13,200,000.00
Fund: 320 SPLOST V
FY 2022 ACTUAL
FY 2023 ACTUAL
FY 2024 BUDGET
FY 2024 YTD
FY 2025 PROPOSED
33 Intergovernmental
–
–
–
4,317,751.24
6,877,628.00
36 Investment Income
–
–
–
377.73
–
Total Budget
–
–
–
4,318,128.97
6,877,628.00
Fund: 321 – SPLOST VI
FY 2022 ACTUAL
FY 2023 ACTUAL
FY 2024 BUDGET
FY 2024 YTD
FY 2025 PROPOSED
33 Intergovernmental
–
–
–
–
–
36 Investment Income
–
–
–
–
–
Total Budget
–
–
–
–
–
Fund: 357 – CITYWIDE DEVELOPMENT AUTHORITY
FY 2022 ACTUAL
FY 2023 ACTUAL
FY 2024 BUDGET
FY 2024 YTD
FY 2025 PROPOSED
FY 2026 PROPOSED
45,000.00
45,000.00
45,000.00
–
45,000.00
68,332.00
–
–
–
–
–
0.00
Total Budget
45,000.00
45,000.00
45,000.00
45,000.00
68,332.00
Fund: 355 – DOWNTOWN DEVELOPMENT AUTHORITY
FY 2022 ACTUAL
FY 2023 ACTUAL
FY 2024 BUDGET
FY 2024 YTD
FY 2025 APPROVED
FY 2026 PROPOSED
45,000.00
45,000.00
45,000.00
0.00
45,000.00
336,100.00
0.00
0.00
0.00
0.00
0.00
0.00
Total Budget
45,000.00
45,000.00
45,000.00
45,000.00
336,100.00
Fund: 353 – CITYWIDE CAPITAL PROJECTS
FY 2022 ACTUAL
FY 2023 ACTUAL
FY 2024 BUDGET
FY 2024 YTD
FY 2025 PROPOSED
0.00
0.00
0.00
0.00
0.00
10,623,467.00
199,365.54
13,539,688.00
0.00
0.00
10,623,467.00
199,365.54
13,539,688.00
0.00
0.00
Fund: 350 – URA
FY 2022 ACTUAL
FY 2023 ACTUAL
FY 2024 BUDGET
FY 2024 YTD
FY 2025 PROPOSED
1,205,212.87
1,023,624.00
1,204,764.50
31,000.00
1,204,766.00
Total Budget
1,205,212.87
1,023,624.00
1,204,764.50
31,000.00
Fund 505 – Water (Division: 43300 – SEWER)
FY 2022 ACTUAL
FY 2023 ACTUAL
FY 2024 BUDGET
FY 2024 YTD
FY 2025 APPROVED
FY 2026 PROPOSED
1,805,138.04
1,640,000.00
1,828,000.00
2,380,977.51
1,953,778.00
2,362,500.00
0.00
300.00
0.00
0.00
0.00
0.00
0.00
280,345.51
257,145.51
0.00
0.00
0.00
Total Budget
1,805,138.04
1,920,645.51
2,085,145.51
2,380,977.51
1,953,778.00
Fund 505 – Water (Division: 44200 – Water)
FY 2022 ACTUAL
FY 2023 ACTUAL
FY 2024 BUDGET
FY 2024 YTD
FY 2025 APPROVED
FY 2026 PROPOSED
2,186,405.09
2,007,100.00
2,214,500.00
2,380,977.51
2,397,100.00
3,255,440.00
–
100.00
–
–
–
0.00
–
182,887.19
165,516.50
–
159,303.00
0.00
Total Budget
2,186,405.09
2,190,087.19
2,380,016.50
2,380,977.51
2,556,403.00
Fund: 495 – CEMETERY FUND
FY 2022 ACTUAL
FY 2023 ACTUAL
FY 2024 BUDGET
FY 2024 YTD
FY 2025 PROPOSED
FY 2025 PROPOSED
0.00
0.00
0.00
0.00
0.00
0.00
0.00
10,000.00
10,000.00
0.00
10,000.00
20,000.00
Total Budget
0.00
10,000.00
10,000.00
0.00
10,000.00
Fund 360 – PUBLIC FACILITIES AUTHORITY
FY 2022 ACTUAL
FY 2023 ACTUAL
FY 2024 BUDGET
FY 2024 YTD
FY 2025 PROPOSED
–
2,943,804.26
2,946,323.50
–
2,943,168.00
Total Budget
2,943,804.26
2,946,323.50
–
2,943,168.00
Fund 540 – Sanitation
FY 2022 ACTUAL
FY 2023 ACTUAL
FY 2024 BUDGET
FY 2024 YTD
FY 2025 PROPOSED
31 Taxes
1,695.68
1,000.00
1,000.23
3,370.78
1,000.00
34 Charges for Services
1,696,585.88
1,705,765.00
2,500,600.00
84,095.09
2,777,500.00
38 Miscellaneous Revenue
113,420.21
215,427.43
358,709.00
47,109.37
358,364.00
Total Budget
1,811,701.77
1,922,192.43
2,860,370.23
134,575.24
3,136,864.00
Fund 510 – Stormwater
FY 2022 ACTUAL
FY 2023 ACTUAL
FY 2024 BUDGET
FY 2024 YTD
FY 2025 PROPOSED
FY 2025 PROPOSED
31 Taxes
993.33
0.00
1,499.79
1,826.31
0.00
0.00
34 Charges for Services
1,036,214.79
1,038,517.79
1,207,000.00
34,308.21
978,924.00
1,400,000.00
38 Miscellaneous Revenue
0.00
0.00
4,790.36
0.00
74,600.00
160,700.00
39 Other Financing Uses
73,188.00
0.00
0.00
0.00
0.00
–
Total Budget
1,110,396.12
1,038,517.79
1,213,290.15
36,134.52
1,053,524.00
1,560,700.00
Water & Sewer Division: 80000 – DEBT SERVICES
FY 2022 ACTUAL
FY 2023 ACTUAL
FY 2024 BUDGET
FY 2024 YTD
FY 2025 PROPOSED
39 Other Financing Services
–
–
127,240.20
–
194,472.00
Total Budget
–
–
127,240.20
–
194,472.00
Expenditures
THE GOVERNING BODY
Account Number
Account Description
FY 2024 BUDGET
FY 2024 ACTUAL
FY 2025 APPROVED
FY 2025 YTD
FY 2026 PROPOSED
100-11100-511100
REGULAR EMPLOYEE SALARIES
116,920.96
43,620.88
122,768.00
90,165.16
135,346.00
100-11100-511120
MAYOR
24,000.00
9,333.35
24,000.00
16,799.99
24,000.00
100-11100-511121
COUNCIL
100,000.00
41,666.75
100,000.00
74,999.95
100,000.00
100-11100-511300
OVERTIME
800.00
1,111.51
1,600.00
893.26
2,500.00
100-11100-512100
GRP INSNC MEDICAL/DENTAL
107,757.52
47,086.50
107,758.00
77,490.39
107,827.75
100-11100-512110
GROUP INSURANCE LIFE
1,000.00
424.44
1,000.00
502.07
985.28
100-11100-512111
GROUP INSURANCE VISION
1,000.00
242.41
1,000.00
516.42
1,000.00
100-11100-512200
MEDICARE 1.45%
1,200.00
1,384.00
1,200.00
2,648.32
3,796.77
100-11100-512400
PENSION
34,000.00
13,833.40
34,000.00
26,989.29
34,000.00
100-11100-512700
WORKER’S COMPENSATION
2,300.00
591.57
0.00
0.00
0.00
100-11100-512851
HRA DEDUCTIBLE
4,000.00
0.00
4,000.00
0.00
4,000.00
100-11100-521101
OFFICIAL/ADMINISTRATIVE
14,000.00
8,720.36
14,000.00
3,640.19
0.00
100-11100-522341
COPIER RENTAL
650.00
610.00
0.00
0.00
0.00
100-11100-523400
PRINTING & BINDING
4,000.00
843.98
3,000.00
1,035.10
3,000.00
100-11100-523500
TRAVEL
2,000.00
0.00
2,000.00
0.00
3,000.00
100-11100-523502
TRAVEL MAYOR
10,000.00
1,189.19
10,000.00
6,737.67
10,000.00
100-11100-523503
TRAVEL DISTRICT 5
10,000.00
1,905.40
10,000.00
7,689.97
10,000.00
100-11100-523504
TRAVEL DISTRICT 3
10,000.00
1,511.80
10,000.00
4,438.51
10,000.00
100-11100-523505
TRAVEL DISTRICT 1
10,000.00
1,521.77
10,000.00
7,903.11
10,000.00
100-11100-523506
TRAVEL DISTRICT 2
10,000.00
1,645.80
10,000.00
6,665.36
10,000.00
100-11100-523507
TRAVEL DISTRICT 4
10,000.00
1,793.80
10,000.00
1,114.00
10,000.00
100-11100-523600
DUES & FEES
100.00
0.00
100.00
1,049.00
100.00
100-11100-523601
DUES & FEES MAYOR
100.00
0.00
100.00
57.70
100.00
100-11100-523602
DUES & FEES DISTRICT 5
100.00
0.00
100.00
0.00
100.00
100-11100-523603
DUES & FEES DISTRICT 3
100.00
0.00
100.00
0.00
100.00
100-11100-523604
DUES & FEES DISTRICT 1
100.00
0.00
100.00
0.00
100.00
100-11100-523605
DUES & FEES DISTRICT 4
100.00
0.00
100.00
0.00
100.00
100-11100-523606
DUES & FEES DISTRICT 2
100.00
0.00
100.00
0.00
100.00
100-11100-523607
EDUCATION & TRAINING
2,000.00
0.00
2,000.00
1,225.00
2,000.00
100-11100-523702
EDUCATION & TRAINING MAYOR
6,000.00
815.00
6,000.00
3,570.20
6,000.00
100-11100-523703
EDUCATION & TRAINING DISTRICT 5
6,000.00
795.00
6,000.00
3,290.00
6,000.00
100-11100-523704
EDUCATION & TRAINING DISTRICT 3
6,000.00
1,220.00
6,000.00
1,020.00
6,000.00
100-11100-523705
EDUCATION & TRAINING DISTRICT 1
6,000.00
1,184.00
6,000.00
3,443.43
6,000.00
100-11100-523706
EDUCATION & TRAINING DISTRICT 4
6,000.00
920.00
6,000.00
705.00
6,000.00
100-11100-523707
EDUCATION & TRAINING DISTRICT 2
6,000.00
795.00
6,000.00
705.00
6,000.00
100-11100-523911
COUNCIL INITIATIVES MAYOR
5,000.00
1,611.65
5,000.00
1,887.78
5,000.00
100-11100-523912
COUNCIL INITIATIVES DISTRICT 5
5,000.00
12,618.23
5,000.00
17,919.78
5,000.00
100-11100-523913
COUNCIL INITIATIVES DISTRICT 3
5,000.00
1,802.56
5,000.00
1,070.00
5,000.00
100-11100-523914
COUNCIL INITIATIVES DISTRICT 1
5,000.00
291.12
5,000.00
1,718.50
5,000.00
100-11100-523915
COUNCIL INITIATIVES DISTRICT 4
5,000.00
8,152.00
5,000.00
10,756.87
5,000.00
100-11100-523916
COUNCIL INITIATIVES DISTRICT 2
5,000.00
13,383.31
5,000.00
11,272.10
5,000.00
100-11100-531130
OFFICE SUPPLIES
2,500.00
503.16
2,500.00
547.80
3,000.00
100-11100-531700
MISCELLANEOUS EXPENSE
4,000.00
640.24
2,000.00
1,560.51
3,000.00
100-11100-531701
HOSPITALITY/FOOD/BEVERAGE
7,000.00
1,767.02
8,000.00
4,223.87
10,000.00
100-11100-531747
CIVIC EVENTS
15,000.00
5,495.43
9,000.00
3,369.23
10,000.00
100-11100-531748
YOUTH ADVISORY COUNCIL
21,500.00
8,154.57
0.00
0.00
0.00
100-11100-531750
UNIFORMS
400.00
0.00
400.00
0.00
400.00
100-11100-531751
UNIFORMS MAYOR
400.00
0.00
400.00
118.38
400.00
100-11100-531752
UNIFORMS DISTRICT 5
400.00
1,147.70
400.00
0.00
400.00
100-11100-531753
UNIFORMS DISTRICT 3
400.00
335.00
400.00
0.00
400.00
100-11100-531754
UNIFORMS DISTRICT 1
400.00
0.00
400.00
0.00
400.00
100-11100-531755
UNIFORMS DISTRICT 4
400.00
0.00
400.00
0.00
400.00
100-11100-531756
UNIFORMS DISTRICT 2
400.00
0.00
400.00
0.00
400.00
Division: 11100 – GOVERNING BODY Total:
595,128.48
240,667.90
569,326.00
399,738.91
916,413.80
EXECUTIVE
Account Number
Account Description
FY 2024 BUDGET
FY 2024 ACTUAL
FY 2025 APPROVED
FY 2025 YTD
FY 2026 PROPOSED
100-13000-511100
REGULAR EMPL. SALARIES
530,170.83
168,486.51
556,680.00
201,740.30
616,722.00
100-13000-511113
VEHICLE ALLOWANCE
12,000.00
4,000.00
6,000.00
500.00
900.00
100-13000-511300
OVERTIME
500.00
222.33
500.00
0.00
500.00
100-13000-512100
GRP INSRC MEDICAL/DENTAL
80,818.14
53,375.08
80,819.00
46,177.01
45,521.62
100-13000-512110
GROUP INSURANCE LIFE
3,000.00
626.79
3,000.00
638.11
528.84
100-13000-512111
GROUP INSURANCE VISION
1,000.00
269.37
1,000.00
279.73
1,000.00
100-13000-512200
MEDICARE 1.45%
6,000.00
2,454.27
6,000.00
2,885.66
8,950.00
100-13000-512400
PENSION
4,200.00
1,708.85
4,200.00
31,752.09
50,000.00
100-13000-512401
RETIREMENT CONTRIBUTION
40,000.00
5,748.83
40,000.00
6,781.10
21,200.00
100-13000-512600
UNEMPLOYMENT INSURANCE
2,500.00
0.00
2,500.00
0.00
3,000.00
100-13000-512700
WORKER’S COMPENSATION
3,000.00
771.62
0.00
0.00
0.00
100-13000-512800
EMPLOYEE ASSISTANCE PROG.
500.00
0.00
500.00
0.00
0.00
100-13000-512850
HRA REIMBURSEMENT
8,000.00
421.86
8,000.00
0.00
12,000.00
100-13000-521201
PROFESSIONAL SERVICES
10,000.00
58,698.60
10,000.00
6,205.00
10,000.00
100-13000-522341
COPIER RENTAL
1,100.00
610.00
0.00
0.00
0.00
100-13000-523400
PRINTING & BINDING
500.00
705.98
1,200.00
627.13
2,000.00
100-13000-523500
TRAVEL
7,000.00
2,719.45
7,000.00
4,836.64
15,000.00
100-13000-523600
DUES & FEES
7,000.00
1,836.67
7,000.00
2,989.49
8,000.00
100-13000-523700
EDUCATION & TRAINING
7,000.00
2,849.00
7,000.00
764.00
10,000.00
100-13000-531130
OFFICE SUPPLIES
2,500.00
1,472.87
2,500.00
1,653.80
3,000.00
100-13000-531140
SUPPLIES & MATERIALS
0.00
0.00
0.00
3,460.03
4,000.00
100-13000-531700
MISCELLANEOUS EXPENSE
5,000.00
1,958.62
5,000.00
4,530.84
5,000.00
100-13000-531701
HOSPITALITY/FOOD/BEVERAGE
5,000.00
169.11
7,500.00
432.00
7,000.00
100-13000-579000
CONTINGENCIES
43,359.03
18,455.00
35,000.00
141,58.72
882,560.35
Division: 13000 – EXECUTIVE Total:
781,148.00
327,560.81
791,399.00
356,985.39
1,706,882.81
CITY CLERK DEPARTMENT
Account Number
Account Description
FY 2024 BUDGET
FY 2024 ACTUAL
FY 2025 APPROVED
FY 2025 YTD
FY 2026 PROPOSED
100-11300-511100
REGULAR EMPL. SALARIES
221,089.49
73,002.47
232,144.00
167,024.43
241,961.00
100-11300-511300
OVERTIME
0.00
0.00
0.00
0.00
0.00
100-11300-512100
GRP INSRC MEDICAL/DENTAL
40,409.07
23,984.43
40,409.00
29,477.39
37,265.53
100-11300-512101
FEES GRP INS
1,500.00
0.00
1,500.00
0.00
1,500.00
100-11300-512110
GROUP INSURANCE LIFE
900.00
317.34
900.00
606.90
728.26
100-11300-512111
GROUP INSURANCE VISION
1,000.00
117.31
1,000.00
201.78
1,000.00
100-11300-512200
MEDICARE 1.45%
3,000.00
1,039.74
3,000.00
2,388.72
3,508.44
100-11300-512400
PENSION
32,000.00
13,019.70
32,000.00
25,401.69
32,000.00
100-11300-512600
UNEMPLOYMENT INSURANCE
2,000.00
0.00
2,000.00
0.00
500.00
100-11300-512700
WORKER’S COMPENSATION
2,000.00
514.40
0.00
0.00
0.00
100-11300-512800
EMPLOYEE ASSISTANCE PROG.
500.00
0.00
500.00
0.00
500.00
100-11300-512851
HRA DEDUCTIBLE
6,000.00
0.00
6,000.00
2,000.00
9,000.00
100-11300-521101
OFFICIAL/ADMINISTRATIVE
14,000.00
0.00
14,000.00
9,212.70
20,000.00
100-11300-523301
CODIFICATION
10,000.00
0.00
10,000.00
1,397.00
3,000.00
100-11300-523310
PUBLIC NOTICES
5,000.00
732.00
3,000.00
1,397.00
3,000.00
100-11300-523400
PRINTING & BINDING
1,000.00
706.72
1,000.00
676.14
1,000.00
100-11300-523500
TRAVEL
9,000.00
1,820.59
9,000.00
6,622.09
9,000.00
100-11300-523600
DUES & FEES
1,500.00
65.00
1,500.00
251.97
2,000.00
100-11300-523700
EDUCATION & TRAINING
6,500.00
64.65
6,500.00
2,544.88
6,500.00
100-11300-523940
POSTAGE
500.00
80.00
500.00
55.96
500.00
100-11300-531120
ELECTION EXPENSE
6,000.00
7,462.30
32,000.00
252.00
32,000.00
100-11300-531130
OFFICE SUPPLIES
2,500.00
89.61
2,500.00
685.88
2,500.00
100-11300-531132
COMMITTEE EXPENSES
0.00
0.00
3,000.00
92.00
3,000.00
100-11300-531140
SUPPLIES & MATERIALS
2,500.00
179.83
2,500.00
337.57
2,500.00
100-11300-531600
SMALL EQUIPMENT – NON CAPIT
1,000.00
0.00
1,000.00
149.98
1,000.00
100-11300-531701
HOSPITALITY/FOOD/BEVERAGE
0.00
828.28
3,000.00
282.71
3,000.00
100-11300-531725
PROMOTIONAL ITEMS
3,000.00
0.00
3,000.00
614.29
3,000.00
100-11300-531747
MUNICIPAL DINNERS
0.00
0.00
6,000.00
374.40
8,000.00
100-11300-531748
YOUTH COUNCIL
0.00
0.00
21,500.00
12,034.17
31,900.00
100-11300-531750
UNIFORMS
750.00
461.39
750.00
0.00
750.00
100-11300-542400
COMPUTER SOFTWARE
7,000.00
2,500.00
5,000.00
5,500.00
6,000.00
Division 11300 – CITY CLERK Total:
380,648.56
126,985.76
445,203.00
277,397.35
527,522.23
FINANCE ADMINISTRATION
Account Number
Account Description
FY 2024 BUDGET
FY 2024 ACTUAL
FY 2025 APPROVED
FY 2025 YTD
FY 2026 PROPOSED
100-15100-511100
REGULAR EMPL. SALARIES
575,778.65
138,431.95
898,942.00
491,487.78
1,014,787.57
100-15100-511300
OVERTIME
200.00
229.54
400.00
0.00
0.00
100-15100-512100
GRP INSRC MEDICAL/DENTAL
134,696.90
47,947.70
134,697.00
120,346.64
211,919.00
100-15100-512110
FEES GRP INS
2,500.00
1,044.00
2,500.00
2,587.50
3,000.00
100-15100-512111
GROUP INSURANCE LIFE
1,875.00
639.76
1,875.00
1,716.95
2,920.00
100-15100-512111
GROUP INSURANCE VISION
1,250.00
192.43
1,250.00
867.96
1,250.00
100-15100-512200
MEDICARE 1.45%
7,500.00
1,976.89
7,500.00
6,997.08
14,715.00
100-15100-512400
PENSION
59,000.00
24,005.05
59,000.00
46,834.29
66,000.00
100-15100-512600
UNEMPLOYMENT INSURANCE
5,250.00
3,285.00
5,250.00
0.00
5,300.00
100-15100-512700
WORKER’S COMPENSATION
5,000.00
1,286.02
5,000.00
0.00
2,000.00
100-15100-512800
EMPLOYEE ASSISTANCE PROG.
24,000.00
1,036.15
24,000.00
0.00
20,000.00
100-15100-512851
HRA DEDUCTIBLE
10,000.00
0.00
10,000.00
0.00
0.00
100-15100-521100
CONSULTANT FEES
50,000.00
0.00
70,000.00
12,331.86
100,000.00
100-15100-521100
PAYROLL FEES
10,000.00
17,443.80
25,000.00
64,728.74
33,000.00
100-15100-522220
AUTO & TRUCK REPAIR
0.00
164.55
0.00
23.00
0.00
100-15100-522230
RENTAL OF EQUIP & VEHICLE
400.00
0.00
400.00
0.00
500.00
100-15100-522341
COPIER RENTAL
4,000.00
2,232.00
4,000.00
0.00
0.00
100-15100-523240
AT&T CLUB SERVICE
10,000.00
8,855.23
10,000.00
0.00
0.00
100-15100-523246
TELECOMMUNICATION
22,000.00
8,773.78
24,000.00
1,318.80
3,000.00
100-15100-523500
TRAVEL
500.00
958.44
2,500.00
1,534.00
6,000.00
100-15100-523600
DUES & FEES
2,000.00
1,369.00
8,000.00
2,238.00
15,000.00
100-15100-523700
EDUCATION & TRAINING
10,000.00
0.00
10,000.00
0.00
70,000.00
100-15100-523850
INTERN HELP
0.00
90,112.04
0.00
0.00
7,000.00
100-15100-523900
BANK CHARGES
5,000.00
501.21
16,000.00
22,822.08
35,000.00
100-15100-523905
COLLECTION FEE HENRY COUNTY
0.00
1,773.31
3,500.00
5,892.38
8,000.00
100-15100-523909
CREDIT CARD EXPENSES
15,000.00
17,234.24
20,000.00
25,792.13
0.00
100-15100-523940
POSTAGE
2,500.00
779.69
2,500.00
1,811.29
2,500.00
100-15100-531140
SUPPLIES & MATERIALS
3,000.00
3,460.18
5,000.00
509.47
6,000.00
100-15100-531700
MISCELLANEOUS EXPENSE
500.00
171.58
500.00
44.57
1,000.00
100-15100-531701
HOSPITALITY/FOOD/BEVERAGE
750.00
0.00
750.00
1,112.48
3,000.00
100-15100-531750
UNIFORMS
500.00
0.00
500.00
829.13
1,000.00
100-15100-541406
STORM WATER/PROPERTY TAX
20,000.00
0.00
20,000.00
902.89
20,000.00
100-15100-542300
FURNITURE & FIXTURES
500.00
0.00
1,000.00
0.00
1,000.00
100-15100-542400
COMPUTER SOFTWARE
20,000.00
0.00
0.00
345.21
0.00
100-15100-542500
EQUIPMENT
500.00
0.00
500.00
14,000.00
15,000.00
Division: 15100
Financial Administration Total:
1,074,325.55
375,208.73
1,399,439.00
942,155.08
1,818,891.57
BUSINESS SERVICES
Account Number
Account Description
FY 2024 BUDGET
FY 2024 ACTUAL
FY 2025 APPROVED
FY 2025 YTD
FY 2026 PROPOSED
100-15160-511100
REGULAR SALARIES
155,014.32
46,014.93
162,766.00
113,630.24
192,920.00
100-15160-511300
OVERTIME
0.00
33.98
0.00
588.76
0.00
100-15160-512100
GRP INSRC MEDICAL/DENTAL
40,409.07
18,103.60
40,409.00
28,331.10
22,760.81
100-15160-512110
GROUP INSURANCE LIFE
850.00
247.74
850.00
452.37
186.68
100-15160-512111
GROUP INSURANCE VISION
1,000.00
93.78
1,000.00
192.78
405.36
100-15160-512200
MEDICARE 1.45%
1,800.00
622.84
1,800.00
1,584.85
2,797.34
100-15160-512240
PENSION
18,750.00
7,628.70
18,750.00
14,883.75
12,946.78
100-15160-512260
UNEMPLOYMENT INSURANCE
2,000.00
0.00
0.00
0.00
0.00
100-15160-512270
WORKER’S COMPENSATION
3,000.00
771.62
3,000.00
0.00
1,618.02
100-15160-512285
HRA DEDUCTIBLE
6,000.00
2,000.00
6,000.00
0.00
6,000.00
100-15160-521201
PROFESSIONAL FEES
0.00
0.00
5,000.00
0.00
5,000.00
100-15160-521310
SOFTWARE
2,700.00
2,700.00
0.00
1,928.94
0.00
100-15160-523341
COPIER RENTAL
1,800.00
1,650.00
0.00
0.00
2,000.00
100-15160-523400
PRINTING & BINDING
1,500.00
248.78
3,000.00
1,085.90
3,500.00
100-15160-523500
TRAVEL
1,700.00
228.24
3,000.00
2,109.60
5,000.00
100-15160-523600
DUES & FEES
1,000.00
0.00
2,000.00
1,232.50
2,000.00
100-15160-523700
EDUCATION & TRAINING
1,000.00
0.00
2,000.00
0.00
3,000.00
100-15160-531140
SUPPLIES & MATERIALS
2,000.00
476.18
5,000.00
2,657.96
7,000.00
100-15160-531600
SMALL EQUIPMENT – NON CAPITAL
900.00
0.00
1,200.00
0.00
4,500.00
100-15160-531750
UNIFORMS
300.00
0.00
500.00
700.73
1,000.00
Division: 15160
Business Services Total:
242,673.39
81,279.45
257,125.00
171,372.36
275,634.99
NON DEPARTMENTAL
Account Number
Account Description
FY 2024 BUDGET
FY 2024 ACTUAL
FY 2025 APPROVED
FY 2025 YTD
FY 2026 PROPOSED
100-15110-521100
CONSULTANT FEES
80,000.00
0.00
80,000.00
0.00
80,000.00
100-15110-521217
LEGAL, OTHER
350,000.00
107,975.00
150,000.00
68,925.25
200,000.00
100-15110-521218
SHREDDING
2,000.00
581.69
2,000.00
1,626.86
2,000.00
100-15110-522250
AUTO & TRUCK REPAIR (ADMIN. VEHICLE)
3,000.00
899.16
3,000.00
2,579.98
3,000.00
100-15110-522320
RENTAL OF EQUIP & VEHICLE
200.00
7,943.25
0.00
1,690.68
7,000.00
100-15110-523300
ADVERTISEMENT
200.00
105.00
400.00
0.00
0.00
100-15110-523945
WEBSITE
15,000.00
24,985.00
30,000.00
29,970.00
30,000.00
100-15110-523946
SEE CLICK FIX SOFTWARE
3,000.00
0.00
3,000.00
6,154.46
3,000.00
100-15110-531140
SUPPLIES & MATERIALS (CITY HALL)
10,000.00
2,692.04
12,000.00
3,708.98
12,000.00
100-15110-531710
CHRISTMAS DECORATIONS
0.00
0.00
0.00
0.00
0.00
100-15110-542402
AGENDA SOFTWARE
8,000.00
15,169.98
20,000.00
12,866.84
20,000.00
100-15110-542403
CITY-WIDE DIGITAL SOFTWARE CONVER
25,000.00
8,369.10
25,000.00
7,533.00
25,000.00
100-15110-542404
APP SOFTWARE
10,000.00
0.00
10,000.00
0.00
0.00
100-15110-542526
OPENGOV
50,000.00
30,529.18
50,000.00
10,176.39
50,000.00
100-15110-571000
ABATEMENT PROGRAM
15,000.00
0.00
15,000.00
0.00
15,000.00
100-15110-579000
CONTINGENCIES
0.00
0.00
1,039,057.00
34,184.33
50,000.00
Division: 15110
NON-DEPARTMENTAL Total:
736,400.00
226,104.24
1,814,457.00
471,737.27
1,027,000.00
GOVERNMENTAL BUILDINGS
Account Number
Account Description
FY 2024 BUDGET
FY 2024 ACTUAL
FY 2025 APPROVED
FY 2025 YTD
FY 2026 PROPOSED
100-15650-511100
REGULAR EMPL. SALARIES
179,588.88
53,854.48
179,999.00
145,786.59
215,711.28
100-15650-511300
OVERTIME
15,000.00
2,507.31
15,000.00
10,827.87
25,000.00
100-15650-512100
GRP INSRC MEDICAL/DENTAL
40,409.07
27,772.55
40,409.00
25,509.61
40,000.00
100-15650-512110
GROUP INSURANCE LIFE
1,500.00
252.79
1,500.00
437.90
1,500.00
100-15650-512111
GROUP INSURANCE VISION
1,000.00
138.80
1,000.00
218.70
1,000.00
100-15650-512200
MEDICARE 1.45%
2,200.00
800.15
2,200.00
2,249.86
3,490.32
100-15650-512400
PENSION
30,000.00
12,205.95
30,000.00
2,381.40
3,000.00
100-15650-512700
WORKER’S COMPENSATION
2,500.00
643.03
2,500.00
0.00
6,000.00
100-15650-512851
HRA
6,000.00
0.00
6,000.00
0.00
10,000.00
100-15650-521200
PROFESSIONAL FEES
10,000.00
0.00
10,000.00
3,004.42
10,000.00
100-15650-521230
ENGINEERING FEES
5,000.00
0.00
5,000.00
0.00
5,000.00
100-15650-522210
MAINTENANCE AGREEMENTS
50,000.00
34,163.60
55,000.00
16,097.98
55,000.00
100-15650-522219
LANDSCAPING
330,000.00
261,318.59
330,000.00
189,522.00
330,000.00
100-15650-522220
MAINTENANCE & CLEANING
5,000.00
0.00
5,000.00
2,768.25
5,000.00
100-15650-522224
EQUIPMENT REPAIRS
10,000.00
197.62
10,000.00
925.20
20,000.00
100-15650-522230
AUTO & TRUCK REPAIR
1,000.00
120.00
1,000.00
0.00
3,500.00
100-15650-522310
Rental of Land and Building
1,000.00
0.00
1,000.00
(6,000.00)
1,200.00
100-15650-522318
FACILITY CLEANING POLICE DEP
25,200.00
25,200.00
31,000.00
18,866.11
31,000.00
100-15650-522319
FACILITY CLEANING PW ADMIN
8,520.00
8,520.00
10,000.00
0.00
12,000.00
100-15650-522320
RENTAL OF EQUIP & VEHICLE
1,000.00
0.00
1,000.00
0.00
0.00
100-15650-522321
FACILITY CLEANING CITY HALL
30,240.00
33,740.00
38,000.00
35,160.74
38,000.00
100-15650-522322
FACILITY CLEANING MMC
37,200.00
42,900.00
48,000.00
23,477.51
38,000.00
100-15650-522323
FACILITY CLEANING TSCC
8,520.00
8,520.00
10,000.00
5,200.00
8,500.00
100-15650-522324
FACILITY CLEANING MUNICIPAL
10,692.00
10,692.00
15,000.00
7,769.18
15,000.00
100-15650-522325
FACILITY CLEANING PW ADMIN
7,680.00
7,680.00
10,000.00
7,800.00
10,000.00
100-15650-522326
FACILITY CLEANING WTP
7,680.00
7,680.00
9,000.00
5,200.00
9,000.00
100-15650-522330
EQUIPMENT REPAIRS CITY HALL
10,000.00
4,290.96
10,000.00
11,169.45
25,000.00
100-15650-522334
EQUIPMENT REPAIRS MMC
5,000.00
1,531.71
10,000.00
4,585.00
15,000.00
100-15650-522335
EQUIPMENT REPAIRS MAINTENANCE
3,000.00
755.00
3,000.00
358.29
5,000.00
100-15650-522336
EQUIPMENT REPAIRS TSCC
10,000.00
0.00
10,000.00
1,562.00
10,000.00
100-15650-522337
EQUIPMENT REPAIRS MUNICIPAL
5,000.00
353.80
5,000.00
0.00
5,000.00
100-15650-522338
EQUIPMENT REPAIRS WTP
1,000.00
113.50
1,000.00
5,102.65
7,000.00
100-15650-522339
EQUIPMENT REPAIRS PW ADMIN
5,000.00
0.00
5,000.00
11,127.00
15,000.00
100-15650-522340
EQUIPMENT REPAIRS POLICE DEP
5,500.00
2,203.49
5,500.00
10,096.54
15,000.00
100-15650-523100
PUBLIC NOTICES
100.00
0.00
100.00
0.00
200.00
100-15650-523500
TRAVEL
2,500.00
850.47
2,500.00
622.76
3,000.00
Division: 15650
GOVERNMENTAL BUILDINGS/PROPER
1,012,529.95
672,373.30
1,073,708.00
700,090.02
1,291,101.60
MUNICIPAL COURT
Account Number
Account Description
FY 2024 BUDGET
FY 2024 ACTUAL
FY 2025 APPROVED
FY 2025 YTD
FY 2026 PROPOSED
100-25000-511140
JUDGE
68,200.00
27,083.35
68,600.00
48,749.99
65,000.00
100-25000-511141
SOLICITOR
30,000.00
0.00
30,000.00
0.00
30,000.00
100-25000-511142
COURT CLERK & ASSISTANTS
201,392.00
58,320.02
211,462.00
131,034.68
240,647.00
100-25000-511300
OVERTIME
0.00
30.15
250.00
916.42
2,000.00
100-25000-512100
GRP INSRC MEDICAL/DENTAL
40,409.07
50,752.05
40,409.00
75,598.61
105,515.95
100-25000-512110
GROUP INSURANCE LIFE
2,000.00
294.48
2,000.00
546.12
830.50
100-25000-512111
GROUP INSURANCE VISION
1,000.00
277.60
1,000.00
447.12
1,000.00
100-25000-512200
MEDICARE 1.45%
3,000.00
1,190.21
3,000.00
2,582.47
4,460.89
100-25000-512400
PENSION
23,000.00
9,357.90
23,000.00
18,257.49
23,000.00
100-25000-512600
UNEMPLOYMENT INSURANCE
2,000.00
0.00
2,000.00
0.00
0.00
100-25000-512700
WORKER’S COMPENSATION
6,000.00
1,543.24
6,000.00
0.00
6,000.00
100-25000-512851
HRA, DEDUCTIBLE
3,000.00
0.00
3,000.00
0.00
0.00
100-25000-512221
LEGAL – INDIGENT
2,000.00
2,000.00
3,300.00
29,700.00
40,000.00
100-25000-512225
INTERPRETER
1,000.00
1,000.00
3,000.00
720.95
3,000.00
100-25000-512310
COURT SOFTWARE
21,685.00
13,375.59
35,000.00
22,043.75
35,000.00
100-25000-512335
SHREDING
900.00
406.85
1,400.00
840.70
2,000.00
100-25000-512341
COPIER RENTAL
3,000.00
3,249.00
0.00
0.00
0.00
100-25000-5123220
GEORGIA TECHNOLOGY AUTH.
150.00
150.00
150.00
77.91
0.00
100-25000-5123310
PUBLIC NOTICES
0.00
0.00
200.00
0.00
200.00
100-25000-5123400
PRINTING & BINDING
3,450.00
552.00
3,000.00
686.32
3,000.00
100-25000-5123500
TRAVEL
1,700.00
1,130.00
4,000.00
1,428.10
4,000.00
100-25000-5123600
DUES & FEES
1,040.00
413.04
1,500.00
460.00
1,500.00
100-25000-5123700
EDUCATION & TRAINING
2,000.00
0.00
2,000.00
520.00
3,000.00
100-25000-5123850
PERSONNEL SERVICE
0.00
900.00
1,000.00
3,600.00
11,800.00
100-25000-5123851
INTERN HELP
0.00
0.00
3,500.00
2,928.00
10,500.00
100-25000-5123940
POSTAGE
1,500.00
1,016.78
2,500.00
1,500.66
3,000.00
100-25000-5123940
OFFICE SUPPLIES
2,000.00
834.62
2,000.00
871.98
2,000.00
100-25000-5123940
NTRL GAS,4545 MUNI COURT
2,700.00
615.65
1,800.00
1,088.04
1,800.00
100-25000-5123940
GA PWR,4602 MUNICIPAL CRT
5,550.00
3,997.39
7,000.00
13,803.77
15,000.00
100-25000-5123940
HOSPITALITY/FOOD/BEVERAGE
250.00
250.00
0.00
111.38
500.00
100-25000-5123940
UNIFORMS
300.00
0.00
750.00
0.00
750.00
100-25000-5124200
SITE IMPROVEMENTS
94,736.00
7,317.00
0.00
73,471.66
550.00
100-25000-5124200
FURNITURE & FIXTURES
0.00
0.00
5,000.00
3,109.78
5,000.00
100-25000-5123940
BRAIN & SPINAL INJURY
1,000.00
272.44
1,400.00
1,379.16
1,400.00
100-25000-5123940
STATE PROBATION SYS FUND
200.00
50.00
200.00
125.00
200.00
100-25000-573003
FINES 10% JAIL
32,000.00
18,879.07
50,000.00
31,747.29
50,000.00
100-25000-573004
VICTIMS ASSIST. FUND
16,000.00
9,302.95
25,000.00
15,872.59
25,000.00
100-25000-573005
BOND REFUND
0.00
0.00
50,000.00
0.00
50,000.00
100-25000-573006
GA CRIME VICTIM’S FUND
208.00
78.00
250.00
182.00
250.00
100-25000-573007
CTY DRUG ABUSE TR AND EDU
2,900.00
1,071.15
2,900.00
1,890.74
2,900.00
100-25000-573008
P. O. A&B FUND
40,000.00
19,926.82
55,000.00
39,831.40
55,000.00
100-25000-573009
P. O. TRAINING FUND
32,000.00
18,521.34
50,000.00
30,850.71
50,000.00
100-25000-573010
INDIGENT DEFENSE FUND
30,000.00
18,547.16
50,000.00
31,724.21
50,000.00
100-25000-573011
DRIVERS ED/TRAINING FUND
0.00
3,790.84
6,700.00
8,304.25
10,000.00
100-25000-573020
WITNESS FEES
0.00
0.00
1,000.00
0.00
1,000.00
Division: 25000 – MUNICIPAL COURT Total:
637,233.07
274,246.69
754,271.00
597,003.25
916,804.34
Police Department
Account Number
Account Description
FY 2024 BUDGET
FY 2024 ACTUAL
FY 2025 APPROVED
FY 2025 YTD
FY 2026 PROPOSED
100-32100-511100
REGULAR EMPL SALARIES
4,876,012.03
1,506,824.85
5,703,520.00
3,548,608.33
6,503,520.00
100-32100-511200
TEMPORARY EMPLOYEES
91,000.00
7,710.41
91,000.00
78,458.62
120,000.00
100-32100-511300
HDTA OVERTIME
140,000.00
14,499.88
230,000.00
298,598.55
230,000.00
100-32100-512100
GRP INSRC MEDICAL/DENTAL
1,442,650.00
499,888.58
1,442,650.00
867,399.80
1,525,418.54
100-32100-512110
GROUP INSURANCE LIFE
18,150.00
6,614.65
18,150.00
13,419.59
19,043.96
100-32100-512111
GROUP INSURANCE VISION
7,800.00
2,275.91
7,800.00
5,537.54
7,800.00
100-32100-512120
MEDICARE 1.45%
62,000.00
23,105.88
62,000.00
56,377.54
125,910.75
100-32100-512400
PENSION
111,500.00
45,365.45
111,500.00
88,508.97
111,500.00
100-32100-512600
Unemployment Insurance
0.00
0.00
0.00
0.00
0.00
100-32100-512700
WORKER’S COMPENSATION
73,700.00
18,956.12
0.00
0.00
0.00
100-32100-512851
HRA DEDUCTIBLE
4,500.00
0.00
0.00
0.00
0.00
100-32100-512101
PROFESSIONAL FEES
4,500.00
0.00
0.00
0.00
0.00
100-32100-512135
SHREDDING
0.00
0.00
0.00
0.00
0.00
100-32100-512200
REPAIRS & MAINTENANCE
12,500.00
572.17
12,500.00
3,444.36
12,500.00
100-32100-512210
MAINTENANCE AGREEMENTS
41,000.00
1,296.64
30,000.00
5,139.75
0.00
100-32100-512250
AUTO & TRUCK REPAIR
43,000.00
31,490.00
50,000.00
61,523.14
210,000.00
100-32100-512320
RENTAL OF EQUIP & VEHICLE
4,000.00
5,592.66
14,600.00
657.96
2,000.00
100-32100-512341
COPIER RENTAL
5,100.00
5,011.00
0.00
0.00
0.00
100-32100-512310
LIABILITY INSURANCE
15,000.00
0.00
15,000.00
12,801.40
15,000.00
100-32100-512220
GEORGIA TECHNOLOGY AUTH.
325.00
550.00
0.00
0.00
0.00
100-32100-512340
PRINTING & BINDING
550.00
1,406.16
2,000.00
2,352.18
6,650.00
100-32100-512350
TRAVEL
30,750.00
678.02
30,750.00
30,779.63
45,000.00
100-32100-512360
DUES & FEES
6,500.00
2,387.37
7,000.00
6,810.66
10,000.00
100-32100-512370
EDUCATION & TRAINING
85,000.00
20,227.00
85,000.00
29,551.38
100,000.00
100-32100-512380
LICENSES
2,500.00
0.00
1,500.00
0.00
0.00
100-32100-512855
CONTRACT SERVICES
10,000.00
10,000.00
20,000.00
161,936.28
350,000.00
100-32100-512386
P O SALARIES – EXTRA DUTY
68,000.00
0.00
68,000.00
0.00
0.00
100-32100-512392
PRE-EMPLOYMENT SCREENING
7,000.00
6,976.16
10,000.00
23,576.25
30,000.00
100-32100-512393
DRUG TESTING, VACCINES
4,000.00
4,000.00
0.00
7,532.00
0.00
100-32100-512394
POSTAGE
1,000.00
673.00
1,000.00
871.54
17,500.00
100-32100-512130
OFFICE SUPPLIES
10,000.00
2,500.96
10,000.00
10,300.98
15,000.00
100-32100-512140
SUPPLIES & MATERIALS
42,000.00
36,861.47
45,000.00
40,816.86
55,000.00
100-32100-512122
NTRL GAS, 4545 MUNI COURT
3,900.00
1,816.24
5,500.00
3,550.82
5,500.00
100-32100-512127
GA POWER ELECTRICITY
12,300.00
6,571.04
25,500.00
22,019.97
40,000.00
100-32100-512190
CABLE
1,920.00
74,777.82
250,000.00
152,504.80
250,000.00
100-32100-512160
SMALL EQUIPMENT
45,000.00
937.91
25,000.00
0.00
0.00
100-32100-512166
K-9 SUPPLIES & SERVICES
0.00
3,500.00
3,000.00
5,416.85
5,000.00
100-32100-512170
MISCELLANEOUS EXPENSE
15,000.00
5,014.13
10,000.00
1,497.22
5,000.00
100-32100-512171
HOSPITAL/FOOD/BEVERAGE
6,000.00
984.85
11,000.00
5,474.33
15,000.00
100-32100-512175
PROMOTIONAL ITEMS
10,000.00
1,205.00
10,000.00
7,120.39
10,000.00
100-32100-512174
TIRE EXPENSE
6,000.00
6,000.00
15,000.00
0.00
0.00
100-32100-531750
UNIFORMS
50,000.00
61,192.76
60,000.00
50,226.63
112,500.00
100-32100-531780
COMMUNITY DONATIONS – POLICE
0.00
7,553.83
0.00
6,529.68
15,000.00
100-32100-542200
VEHICLES
125,000.00
216,718.00
0.00
0.00
0.00
100-32100-542300
FURNITURE & FIXTURES
5,000.00
188.15
25,000.00
2,431.61
5,000.00
100-32100-542400
COMPUTER SOFTWARE
131,342.97
94,899.68
135,000.00
86,830.20
5,000.00
100-32100-542500
EQUIPMENT
375,000.00
29,066.28
5,000.00
46,275.60
130,000.00
100-32100-573008
P. O. A&B FUND
16,000.00
3,600.00
22,000.00
11,060.00
35,300.00
100-32100-573013
LEGAL DEFENSE FUND
7,000.00
6,264.50
7,000.00
6,264.50
8,245.00
Division: 32100 – POLICE ADMINISTRATION Total:
Total:
8,200,000.00
2,859,419.85
8,685,290.00
5,782,002.24
10,182,808.25
Public Works
Account Number
Account Description
FY 2024 BUDGET
FY 2024 ACTUAL
FY 2025 APPROVED
FY 2025 YTD
FY 2026 PROPOSED
100-42200-511100
REGULAR EMPL SALARIES
1,166,892.33
373,961.45
1,225,237.00
789,400.41
1,600,000.00
100-42200-511300
OVERTIME
35,000.00
9,419.81
35,000.00
37,118.37
50,000.00
100-42200-512100
GRP INSRC MEDICAL/DENTAL
332,863.00
166,820.92
332,863.00
346,810.89
479,024.75
100-42200-512110
GROUP INSURANCE LIFE
13,500.00
1,822.27
13,500.00
3,786.23
4,627.74
100-42200-512111
GROUP INSURANCE VISION
4,500.00
784.31
4,500.00
2,054.97
4,500.00
100-42200-512200
MEDICARE 1.45%
20,400.00
5,476.07
20,400.00
11,758.85
23,952.00
100-42200-512400
PENSION
300,000.00
122,059.55
300,000.00
238,140.63
300,000.00
100-42200-512600
UNEMPLOYMENT INSURANCE
15,000.00
0.00
15,000.00
0.00
0.00
100-42200-512700
WORKER’S COMPENSATION
62,000.00
16,046.77
0.00
0.00
0.00
100-42200-512851
HRA, DEDUCTIBLE
40,000.00
3,128.77
4,000.00
2,673.26
40,000.00
100-42200-512201
PROFESSIONAL
25,000.00
22,500.00
25,000.00
0.00
25,000.00
100-42200-512230
ENGINEERING FEES
25,000.00
22,500.00
3,000.00
216.00
5,000.00
100-42200-522000
ROW LANDSCAPING
400,000.00
305,532.00
400,000.00
197,295.02
400,000.00
100-42200-522150
SURVEILLANCE CAMERAS
13,500.00
0.00
5,000.00
616.00
5,000.00
100-42200-522210
MAINTENANCE AGREEMENTS
5,000.00
1,232.00
3,000.00
2,043.20
3,000.00
100-42200-522220
MAINTENANCE & CLEANING
3,000.00
3,000.00
75,000.00
54,244.52
200,000.00
100-42200-522241
TRAFFIC SIGNAL MAINTENANCE
35,000.00
26,057.34
35,000.00
23,991.05
50,000.00
100-42200-522242
LMIG S013642-PRC,3 STRTS
288,000.00
36,104.00
300,000.00
17,655.81
50,000.00
100-42200-522250
AUTO & TRUCK REPAIR
15,000.00
4,143.92
15,000.00
18,437.21
25,000.00
100-42200-522320
RENTAL OF EQUIP & VEHICLE
2,500.00
10,361.70
2,500.00
0.00
2,500.00
100-42200-522341
COPIER RENTAL
5,000.00
2,881.00
5,000.00
0.00
5,000.00
100-42200-522345
TELECOMMUNICATIONS
5,000.00
5,414.47
5,000.00
0.00
5,000.00
100-42200-523100
PUBLIC NOTICES
100.00
0.00
100.00
0.00
100.00
100-42200-523500
PRINTING & BINDING
3,500.00
2,287.92
3,500.00
605.26
7,000.00
100-42200-523600
TRAVEL
1,000.00
0.00
1,000.00
534.58
1,000.00
100-42200-523700
DUES & FEES
7,500.00
2,421.70
7,500.00
0.00
20,000.00
100-42200-523850
PERSONNEL SERVICE
80,000.00
80,000.00
100,000.00
19,867.05
100,000.00
100-42200-523930
UTILITY PROTECTION SERV.
5,000.00
0.00
5,000.00
0.00
0.00
100-42200-523960
DRUG TESTING, VACCINES
1,000.00
1,000.00
2,500.00
0.00
2,500.00
100-42200-531130
OFFICE SUPPLIES
1,000.00
638.24
1,000.00
454.40
1,000.00
100-42200-531140
SUPPLIES & MATERIALS
15,000.00
9,744.38
15,000.00
14,744.43
18,000.00
100-42200-531142
HAND TOOLS & SMALL EQUIP.
15,000.00
4,658.64
15,000.00
4,633.38
20,000.00
100-42200-531145
MOSQUITO SPRAYING
1,500.00
625.00
1,500.00
255.00
1,500.00
100-42200-531211
NTRL GAS,4545 MUNI COURT
9,000.00
2,755.15
9,000.00
5,379.14
9,000.00
100-42200-531222
GA POWER ELECTRICITY
21,000.00
12,571.34
21,000.00
27,510.60
40,000.00
100-42200-531233
STREET LIGHTS, OUTSIDE
750,000.00
259,507.33
750,000.00
636,796.06
900,000.00
100-42200-531270
ENERGY-GASOLINE/DIESEL
45,000.00
19,058.88
50,000.00
45,787.58
65,000.00
100-42200-531700
CHRISTMAS DECORATIONS
2,500.00
0.00
2,500.00
860.66
2,500.00
100-42200-531710
SIGNS
15,000.00
0.00
15,000.00
0.00
30,000.00
100-42200-531740
TIRE EXPENSE
7,500.00
815.47
7,500.00
6,239.72
7,500.00
100-42200-531750
UNIFORMS
11,000.00
14,027.82
15,000.00
9,137.55
20,000.00
100-42200-541403
PAVING
25,000.00
0.00
0.00
0.00
0.00
100-42200-541404
SIDEWALKS
300,000.00
297,125.00
0.00
0.00
0.00
100-42200-541408
HC IGA 2025 PAVING PROJECT
0.00
0.00
0.00
110,000.00
0.00
100-42200-542200
VEHICLES
240,000.00
0.00
0.00
0.00
0.00
100-42200-542400
COMPUTER SOFTWARE
5,500.00
5,111.21
35,000.00
24,266.86
35,000.00
100-42200-542500
EQUIPMENT
200,000.00
194,407.06
0.00
0.00
0.00
Division: 42200 – PUBLIC WORKS Total:
4,611,855.33
2,057,774.39
3,906,200.00
2,659,219.26
4,900,804.49
Parks
Account Number
Account Description
FY 2024 BUDGET
FY 2024 ACTUAL
FY 2025 APPROVED
FY 2025 YTD
FY 2026 PROPOSED
100-62200-522151
SURVEILLANCE CAMERAS-REEVES CREEK TRAIL
5,500.00
0.00
0.00
0.00
0.00
100-62200-522152
SURVEILLANCE CAMERAS-MEMORIAL PARK
37,500.00
0.00
0.00
0.00
0.00
100-62200-522153
SURVEILLANCE CAMERAS-CLARK PARK
37,500.00
0.00
0.00
0.00
0.00
100-62200-522154
SURVEILLANCE CAMERAS-GARDNER PARK
27,500.00
0.00
0.00
0.00
0.00
100-62200-522224
FOUNTAIN MAINTENANCE
15,000.00
966.52
15,000.00
7,504.06
15,000.00
100-62200-522225
BRIDGE MAINTENANCE
5,000.00
0.00
5,000.00
0.00
5,000.00
100-62200-522230
EQUIPMENT REPAIRS
6,000.00
3,962.22
0.00
8,750.00
6,000.00
100-62200-522250
AUTO & TRUCK REPAIR
0.00
0.00
0.00
0.00
0.00
100-62200-523220
GEORGIA TECHNOLOGY AUTH.
600.00
300.00
1,000.00
451.15
0.00
100-62200-523240
AT&T CLUB SERVICE
4,500.00
4,762.53
0.00
(600.00)
15,000.00
100-62200-531140
SUPPLIES & MATERIALS
13,400.00
5,879.78
20,000.00
10,931.93
20,000.00
100-62200-531142
HAND TOOLS & SMALL EQUIP.
3,500.00
0.00
5,000.00
3,507.38
4,000.00
100-62200-531222
GA POWER ELECTRICITY
25,000.00
53,373.19
155,000.00
110,385.20
180,000.00
100-62200-531209
MISCELLANEOUS EXPENSE
0.00
1,325.00
4,500.00
85.00
200.00
100-62200-542400
IMPROVEMENTS
0.00
0.00
5,500.00
0.00
0.00
100-62200-542500
COMPUTER SOFTWARE
0.00
0.00
0.00
0.00
0.00
100-62200-542502
EQUIPMENT
0.00
0.00
10,000.00
3,547.46
10,000.00
100-62200-542502
MISCELLANEOUS
0.00
0.00
0.00
0.00
0.00
Division: 62200 – PARKS Total:
181,000.00
70,569.24
221,000.00
144,562.18
255,200.00
City Events
Account Number
Account Description
FY 2024 BUDGET
FY 2024 ACTUAL
FY 2025 APPROVED
FY 2025 YTD
FY 2026 PROPOSED
100-61900-511100
REGULAR EMPL. SALARIES
0.00
0.00
0.00
0.00
677,758.10
100-61900-511300
OVERTIME
0.00
0.00
0.00
0.00
10,000.00
100-61900-512100
GRP INSRC MEDICAL/DENTAL
0.00
0.00
0.00
0.00
198,043.52
100-61900-512110
GROUP INSURANCE LIFE
0.00
0.00
0.00
0.00
2,950.00
100-61900-512111
GROUP INSURANCE VISION
0.00
0.00
0.00
0.00
0.00
100-61900-512200
MEDICARE 1.45%
0.00
0.00
0.00
0.00
9,827.50
100-61900-512400
PENSION
0.00
0.00
0.00
0.00
60,000.00
100-61900-512600
Unemployment Insurance
0.00
0.00
0.00
0.00
10,000.00
100-61900-512700
WORKER’S COMPENSATION
0.00
0.00
0.00
0.00
0.00
100-61900-52851
HRA REIMBURSEMENT
0.00
0.00
0.00
0.00
20,000.00
100-61900-523231
CELL PHONES
0.00
0.00
0.00
0.00
0.00
100-61900-523245
Telecommunications
0.00
0.00
0.00
0.00
0.00
100-61900-523300
ADVERTISING
30,000.00
0.00
35,000.00
23,072.99
35,000.00
100-61900-531701
HOSPITALITY
1,500.00
636.00
1,500.00
526.24
5,000.00
100-61900-531705
CHRISTMAS DECORATIONS
40,000.00
8,715.48
40,000.00
9,760.50
40,000.00
100-61900-531710
SIGNS
10,000.00
0.00
15,000.00
0.00
15,000.00
100-61900-531720
MEMORIAL DAY MARCH
3,000.00
2,946.65
5,000.00
4,331.44
5,000.00
100-61900-531727
PRETTY IN PINK
25,000.00
16,175.00
37,500.00
11,477.46
45,000.00
100-61900-531733
CAREER FAIRS
1,500.00
458.93
2,000.00
1,220.00
2,000.00
100-61900-531734
9/11 CEREMONY
0.00
360.00
4,500.00
450.00
4,500.00
100-61900-531736
BRIDGEFEST
120,000.00
44,430.00
150,000.00
17,573.42
150,000.00
100-61900-531737
FOOD TRUCKS
40,000.00
29,839.01
40,000.00
14,573.42
40,000.00
100-61900-531738
VETERAN’S DAY PARADE
10,000.00
0.00
15,000.00
3,490.35
15,000.00
100-61900-531757
BACK TO SCHOOL
13,000.00
1,150.00
15,000.00
4,053.82
15,000.00
100-61900-531758
JULY 4TH EVENT
140,000.00
50,870.00
150,000.00
194,013.71
170,000.00
100-61900-531759
JUNETEENTH EVENT
120,000.00
42,680.00
140,000.00
120,955.22
120,000.00
100-61900-531760
VOLUNTEER GALA
12,000.00
1,442.86
15,000.00
(2,000.00)
0.00
100-61900-531761
HISPANIFEST
0.00
0.00
0.00
0.00
15,000.00
100-61900-542200
VEHICLES
0.00
0.00
0.00
0.00
0.00
Division: 61900 – CITY EVENTS Total:
570,000.00
199,703.93
670,000.00
404,161.07
1,669,579.12
PLANNING AND ZONNING
Account Number
Account Description
FY 2024 BUDGET
FY 2024 ACTUAL
FY 2025 APPROVED
FY 2025 YTD
FY 2026 PROPOSED
100-74100-511100
REGULAR SALARIES
386,526.47
107,248.82
460,000.00
256,137.74
456,630.00
100-74100-512100
GRP INSRC MEDICAL/DENTAL
67,348.45
11,884.95
67,348.00
25,614.59
85,000.00
100-74100-512110
GROUP INSURANCE LIFE
3,300.00
299.64
3,300.00
652.68
1,300.00
100-74100-512111
GROUP INSURANCE VISION
1,000.00
114.50
1,000.00
276.66
1,000.00
100-74100-512200
MEDICARE 1.45%
3,600.00
1,505.63
3,600.00
3,598.84
6,621.00
100-74100-512400
PENSION
61,800.00
25,144.25
61,800.00
49,056.93
61,800.00
100-74100-512600
UNEMPLOYMENT INSURANCE
12,000.00
0.00
12,000.00
0.00
12,000.00
100-74100-512700
WORKER’S COMPENSATION
12,000.00
3,086.48
0.00
0.00
12,000.00
100-74100-512851
HRA DEDUCTIBLE
10,000.00
0.00
10,000.00
54.19
10,000.00
100-74100-521150
ZONING BOARD STIPEND
4,100.00
275.00
5,600.00
875.00
5,600.00
100-74100-521200
PROFESSIONAL FEES
11,034.07
(13,282.42)
100,000.00
0.00
200,000.00
100-74100-521300
TECHNICAL SERVICES
2,695.93
0.00
3,000.00
975.00
5,000.00
100-74100-522110
SOFTWARE
13,770.00
12,270.00
0.00
8,765.96
0.00
100-74100-522250
MAINTENANCE AGREEMENTS
0.00
0.00
0.00
0.00
0.00
100-74100-522341
COPIER RENTAL
1,000.00
4,731.20
0.00
0.00
0.00
100-74100-523300
ADVERTISEMENT
4,000.00
376.00
5,000.00
2,988.00
5,000.00
100-74100-523400
PRINTING & BINDING
4,000.00
2,331.90
4,000.00
2,427.94
5,000.00
100-74100-523500
TRAVEL
4,500.00
0.00
10,000.00
59.91
10,000.00
100-74100-523501
ZONING ADVISORY BOARD TRAVEL
0.00
0.00
2,000.00
0.00
2,000.00
100-74100-523600
DUES & FEES
775.00
0.00
2,250.00
48.60
3,000.00
100-74100-523700
EDUCATION & TRAINING
3,500.00
3,500.00
6,000.00
1,074.71
10,000.00
100-74100-523850
ZONING ADVISORY BD ED & TRAINING
400.00
0.00
1,000.00
250.00
1,000.00
100-74100-523851
PERSONNEL SERVICES
0.00
0.00
25,000.00
0.00
25,000.00
100-74100-523851
INTERN HELP
0.00
0.00
3,500.00
0.00
5,000.00
100-74100-523940
POSTAGE
500.00
0.00
2,500.00
93.98
2,500.00
100-74100-531100
SUPPLIES & MATERIALS
3,500.00
620.11
3,500.00
3,829.18
5,000.00
100-74100-531270
ENERGY-GASOLINE/DIESEL
1,000.00
0.00
1,500.00
0.00
2,000.00
100-74100-531400
BOOKS & PERIODICALS
0.00
0.00
1,200.00
46.00
1,200.00
100-74100-531600
SMALL EQUIPMENT – NON-CAPITAL
750.00
0.00
2,500.00
0.00
8,000.00
100-74100-531701
HOSPITALITY/FOOD/BEVERAGE
300.00
1,140.59
2,000.00
788.76
5,000.00
100-74100-531750
UNIFORMS
400.00
71.20
1,500.00
498.34
1,500.00
100-74100-542200
VEHICLES
0.00
0.00
0.00
280.00
100,000.00
100-74100-542300
FURNITURE & FIXTURES
0.00
0.00
3,500.00
235.22
3,500.00
100-74100-542400
COMPUTER SOFTWARE
0.00
0.00
0.00
0.00
0.00
Division: 74100 – PLANNING & ZONING Total:
614,199.92
161,317.85
806,598.00
358,877.83
1,053,651.00
PERMITTING- COMMUNITY DEVELOPMENT
Account Number
Account Description
FY 2024 BUDGET
FY 2024 ACTUAL
FY 2025 APPROVED
FY 2025 YTD
FY 2026 PROPOSED
100-72000-511100
REGULAR EMPL. SALARIES
402,686.01
73,419.66
422,821.00
229,581.32
383,094.40
100-72000-511300
OVERTIME
0.00
127.10
0.00
3,067.72
0.00
100-72000-512100
GRP INSRC MEDICAL/DENTAL
26,939.38
33,085.47
26,940.00
77,063.10
108,930.10
100-72000-512110
GROUP INSURANCE LIFE
550.00
346.34
550.00
930.90
1,781.97
100-72000-512111
GROUP INSURANCE VISION
1,000.00
122.73
1,000.00
448.87
1,000.00
100-72000-512200
MEDICARE 1.45%
1,000.00
1,022.63
1,000.00
3,393.47
5,554.87
100-72000-512400
PENSION
20,000.00
8,137.30
20,000.00
15,876.00
20,000.00
100-72000-512600
UNEMPLOYMENT INSURANCE
2,000.00
0.00
2,000.00
0.00
0.00
100-72000-512700
WORKER’S COMPENSATION
2,000.00
514.40
0.00
0.00
0.00
100-72000-512851
HRA DEDUCTIBLE
3,000.00
0.00
3,000.00
0.00
0.00
100-72000-521200
PROFESSIONAL FEES
10,000.00
0.00
5,000.00
0.00
5,000.00
100-72000-521202
CONSULTING SERVICES – BSD
294,600.00
198,833.35
0.00
0.00
0.00
100-72000-521203
CONSULTING SERVICES – ENG.
54,000.00
33,250.00
100,000.00
30,000.00
100,000.00
100-72000-521310
SOFTWARE
17,600.00
17,544.00
110,000.00
74,871.82
110,000.00
100-72000-522210
MAINTENANCE AGREEMENT
(1,500.00)
0.00
0.00
0.00
0.00
100-72000-522250
AUTO & TRUCK REPAIR
1,000.00
365.44
5,000.00
55.00
6,000.00
100-72000-522341
COPIER RENTAL
600.00
0.00
0.00
0.00
0.00
100-72000-523400
PRINTING & BINDING
500.00
169.24
500.00
0.00
1,500.00
100-72000-523500
TRAVEL
1,000.00
0.00
6,000.00
980.00
15,000.00
100-72000-523600
DUES & FEES
500.00
0.00
5,000.00
170.00
5,000.00
100-72000-523700
EDUCATION & TRAINING
1,000.00
0.00
0.00
0.00
15,000.00
100-72000-523850
PERSONNEL SERVICES
34,300.00
9,184.53
36,000.00
4,412.98
112,000.00
100-72000-523851
INTERN HELP
0.00
0.00
3,500.00
8,164.00
7,500.00
100-72000-523940
POSTAGE
100.00
0.00
2,000.00
0.00
2,000.00
100-72000-531100
GEN SUPPLIES & MAT
500.00
0.00
1,500.00
476.32
3,000.00
100-72000-531140
SUPPLIES AND MATERIALS
500.00
0.00
2,500.00
257.49
3,000.00
100-72000-531270
ENERGY-GASOLINE/DIESEL
3,000.00
807.68
4,000.00
1,471.77
4,000.00
100-72000-531701
HOSPITALITY/FOOD/BEVERAGE
0.00
0.00
0.00
163.16
0.00
100-72000-531750
UNIFORMS
700.00
0.00
1,000.00
546.52
5,000.00
100-72000-542200
VEHICLES
0.00
0.00
0.00
0.00
0.00
100-72000-542300
FURNITURE & FIXTURES
7,000.00
6,098.84
3,000.00
0.00
7,000.00
Division: 72000 – PERMITTING DEVELOPMENT Total:
884,575.39
383,028.71
762,311.00
452,620.44
921,361.34
ECONOMIC DEVELOPMENT
Account Number
Account Description
FY 2024 BUDGET
FY 2024 ACTUAL
FY 2025 APPROVED
FY 2025 YTD
FY 2026 PROPOSED
100-75100-511100
REGULAR SALARIES
146,280.12
47,538.08
153,595.00
168,599.67
278,160.14
100-75100-511300
OVERTIME
0.00
424.12
0.00
2,587.53
0.00
100-75100-512100
GRP INSRC MEDICAL/DENTAL
40,409.07
17,525.65
40,409.00
26,189.65
60,930.91
100-75100-512110
GROUP INSURANCE LIFE
1,650.00
187.63
1,650.00
610.70
1,121.12
100-75100-512111
GROUP INSURANCE VISION
3,000.00
84.40
3,000.00
169.29
3,000.00
100-75100-512200
MEDICARE 1.45%
3,300.00
695.49
3,300.00
2,426.43
4,033.33
100-75100-512400
PENSION
30,900.00
12,572.15
30,900.00
24,528.51
30,900.00
100-75100-512600
UNEMPLOYMENT INSURANCE
6,000.00
0.00
6,000.00
0.00
6,000.00
100-75100-512700
WORKER’S COMPENSATION
6,000.00
1,543.24
0.00
0.00
0.00
100-75100-512851
HRA DEDUCTIBLE
6,000.00
0.00
6,000.00
0.00
6,000.00
100-75100-5121200
PROFESSIONAL SERVICES
20,000.00
22,804.00
30,000.00
4,018.00
30,000.00
100-75100-521310
SOFTWARE
0.00
0.00
0.00
1,376.00
0.00
100-75100-522341
COPIER RENTAL
1,000.00
0.00
0.00
0.00
0.00
100-75100-523240
AT&T CLUB SERVICE
3,000.00
0.00
0.00
0.00
0.00
100-75100-523400
PRINTING & BINDING
1,000.00
0.00
500.00
0.00
500.00
100-75100-523500
TRAVEL
5,000.00
(173.64)
5,000.00
725.35
6,000.00
100-75100-523600
DUES & FEES
2,000.00
1,280.00
2,000.00
975.67
2,000.00
100-75100-523700
EDUCATION & TRAINING
5,000.00
0.00
5,000.00
60.00
5,000.00
100-75100-523708
ED INCENTIVES
50,000.00
0.00
25,000.00
0.00
35,000.00
100-75100-523851
INTERN HELP
4,500.00
2,081.25
3,500.00
0.00
3,500.00
100-75100-523940
POSTAGE
500.00
0.00
250.00
11.58
250.00
100-75100-531140
SUPPLIES & MATERIALS
1,500.00
427.47
1,500.00
1,296.11
1,500.00
100-75100-531701
HOSPITALITY/FOOD/BEVERAGE
3,000.00
443.50
2,500.00
881.92
2,500.00
100-75100-531750
UNIFORMS
250.00
0.00
250.00
0.00
250.00
100-75100-542400
COMPUTER SOFTWARE
10,200.00
5,256.00
10,200.00
6,445.50
10,200.00
Division: 75100 – ECONOMIC DEVELOPMENT Total:
350,489.19
112,689.34
330,554.00
240,901.91
486,845.50
MAIN STREET
Account Number
Account Description
FY 2024 BUDGET
FY 2024 ACTUAL
FY 2025 APPROVED
FY 2025 YTD
FY 2026 PROPOSED
100-75500-511100
REGULAR SALARIES
127,083.51
33,622.21
133,438.00
77,833.36
133,438.00
100-75500-511300
OVERTIME
0.00
0.00
500.00
1,710.00
1,000.00
100-75500-512100
GRP INSRC MEDICAL/DENTAL
26,939.38
12,112.73
26,939.00
17,327.62
26,939.00
100-75500-512110
GROUP INSURANCE LIFE
620.00
158.88
620.00
323.80
620.00
100-75500-512111
GROUP INSURANCE VISION
1,000.00
63.01
1,000.00
119.88
1,000.00
100-75500-512200
MEDICARE 1.45%
1,500.00
525.67
1,500.00
1,123.28
1,934.85
100-75500-512400
PENSION
20,000.00
8,137.30
20,000.00
15,876.00
20,000.00
100-75500-512600
UNEMPLOYMENT INSURANCE
600.00
0.00
600.00
0.00
600.00
100-75500-512700
WORKER’S COMPENSATION
1,200.00
308.63
0.00
0.00
0.00
100-75500-512851
HRA, DEDUCTIBLE
4,000.00
0.00
4,000.00
0.00
4,000.00
100-75500-521200
PROFESSIONAL FEES
5,000.00
2,056.89
5,000.00
7,715.00
6,000.00
100-75500-522341
COPIER RENTAL
1,700.00
1,671.00
0.00
0.00
0.00
100-75500-523240
AT&T CLUB SERVICE
3,000.00
2,592.47
0.00
0.00
0.00
100-75500-523400
PRINTING & BINDING
2,500.00
493.46
2,000.00
367.92
2,000.00
100-75500-523500
TRAVEL
5,000.00
282.75
5,000.00
4,538.82
7,000.00
100-75500-523520
MAIN STREET BOARD TRAVEL
3,500.00
309.00
3,500.00
0.00
2,000.00
100-75500-523600
DUES & FEES
1,300.00
0.00
1,300.00
869.88
1,300.00
100-75500-523700
EDUCATION & TRAINING
3,050.00
75.00
3,000.00
2,941.48
4,000.00
100-75500-523720
MAIN STREET BOARD EDUCATION & T
3,575.00
0.00
3,500.00
630.00
2,500.00
100-75500-523851
INTERN HELP
2,000.00
4,515.00
2,000.00
0.00
3,500.00
100-75500-523940
POSTAGE
200.00
0.00
200.00
0.00
100.00
100-75500-523945
WEB SITE
4,000.00
1,188.00
4,000.00
4,000.00
4,000.00
100-75500-531140
SUPPLIES & MATERIALS
2,000.00
186.57
2,000.00
59.64
1,000.00
100-75500-531227
GA PWR, MAIN STREET
5,000.00
2,528.50
6,000.00
4,871.06
0.00
100-75500-531701
HOSPITALITY/FOOD/BEVERAGE
5,000.00
471.53
3,000.00
646.22
3,000.00
100-75500-531707
ENTERTAINMENT
5,000.00
1,917.53
5,000.00
4,728.00
5,000.00
100-75500-531724
DOWNTOWN BEAUTIFICATION
2,000.00
0.00
2,000.00
0.00
2,000.00
100-75500-531725
PROMOTIONAL SUPPLIES
2,500.00
299.31
2,500.00
300.00
1,000.00
100-75500-531750
UNIFORMS
845.00
0.00
1,000.00
51.00
1,000.00
100-75500-542300
FURNITURE & FIXTURES
0.00
0.00
0.00
0.00
0.00
Division: 75500 – Main Street Program Total:
238,612.89
73,515.44
240,097.00
146,217.96
240,931.85
GIS PLANNING
Account Number
Account Description
FY 2023 ACTUAL
FY 2024 BUDGET
FY 2024 ACTUAL
FY 2025 APPROVED
FY 2025 YTD
FY 2026 PROPOSED
100-75700-511100
REGULAR EMPLOYEE SALARIES
58,801.23
68,393.00
24,989.80
71,813.00
44,468.46
75,404.00
100-75700-512100
GRP INSUR MEDICAL / DENTAL
11,018.99
13,469.69
5,793.91
13,470.00
5,843.66
247.52
100-75700-512110
GROUP INSURANCE LIFE
480.57
300.00
289.62
300.00
379.48
0.00
100-75700-512111
GROUP INSURANCE VISION
66.22
1,000.00
24.08
1,000.00
13.32
1,000.00
100-75700-512200
MEDICARE 1.45%
851.33
1,000.00
357.83
1,000.00
640.91
1,093.36
100-75700-512400
PENSION
4,896.24
6,500.00
2,644.60
6,500.00
5,159.70
6,500.00
100-75700-512600
UNEMPLOYMENT INSURANCE
0.00
700.00
0.00
700.00
0.00
0.00
100-75700-512700
WORKERS’ COMPENSATION
252.69
500.00
128.59
2,000.00
0.00
2,000.00
100-75700-512851
HRA DEDUCTIBLE
0.00
2,000.00
0.00
2,000.00
0.00
0.00
100-75700-521200
PROFESSIONAL SERVICES
0.00
0.00
0.00
10,000.00
1,883.33
15,000.00
100-75700-521300
Technical Services
5,380.00
5,700.00
0.00
0.00
0.00
0.00
100-75700-521310
SOFTWARE
0.00
4,235.00
4,235.00
8,000.00
8,690.58
15,000.00
100-75700-523410
COPIER RENTAL
1,609.44
1,700.00
1,610.00
0.00
0.00
0.00
100-75700-523400
PRINTING & BINDING
1,442.69
2,000.00
42.76
1,500.00
823.30
2,000.00
100-75700-523500
TRAVEL
0.00
1,200.00
0.00
1,500.00
0.00
3,000.00
100-75700-523600
DUES & FEES
0.00
250.00
0.00
700.00
0.00
700.00
100-75700-523700
EDUCATION & TRAINING
0.00
1,500.00
0.00
0.00
0.00
2,500.00
100-75700-531110
COMPUTER EXPENSE
22,941.00
0.00
0.00
0.00
0.00
0.00
100-75700-531140
SUPPLIES & MATERIALS
1,742.00
3,000.00
0.00
2,500.00
680.86
3,000.00
100-75700-531725
PROMOTIONAL ITEMS
0.00
0.00
0.00
300.00
0.00
300.00
100-75700-531750
UNIFORMS
20.49
200.00
0.00
300.00
0.00
8,000.00
100-75700-541100
LAND ACQUISITIONS / SITES
0.00
0.00
0.00
0.00
0.00
0.00
Division: 75700 – GIS/PLANNING Total:
102,334.14
116,512.69
40,116.19
123,083.00
68,583.60
135,744.88
OTHER FINANCING USES
Account Number
Account Description
FY 2022 BUDGET
FY 2022 ACTUAL
FY 2023 BUDGET
2026 Payments
100-90000-611276
TRANSFER GF AND CEMETERY
20,000.00
10,775.89
10,000.00
100-90000-611300
TRANSFER GF AND SDDA
45,000.00
0.00
90,000.00
100-90000-611650
TRANSFER TO/FROM URA
120,521.88
120,521.87
1,208,355.50
100-90000-612020
TRANSFER TO/FROM PFA FUND
188,042.00
301,456.26
2,943,804.26
100-90000-612030
TRANSFER TO/FROM SPLOST V
0.00
0.00
0.00
100-90000-612040
TRANSFER TO/FROM AMPHITHEATER OPERATING
0.00
0.00
0.00
Division: 90000 – OTHER FINANCING USES Total:
182,753.29
929,493.74
4,252,159.76
variance
PFA Series C – Maturity Date 08/01/2036
2026 Payments
9,910,000.00
1,030,000.00
14,865,000.00
1,265,000.00
25,805,000.00
1,265,000.00
632,500.00
URA Series 2005B, 2006A and 2006C – Maturity Date 02/01/2031
2026 Payments
17,125,000.00
1,055,033.00
5,000,000.00
311,812.25
7,330,000.00
447,306.25
4,795,000.00
295,914.50
34,250,000.00
2,110,066.00
158,987.00
Principal Payment Due every February 1 Interest Payment Due every August 1
PROPERTY EVIDENCE
Account Number
Account Description
FY 2023 BUDGET
FY 2024 BUDGET
FY 2025 APPROVED
FY 2026 PROPOSED
211-15100-523901
BANK CHARGES
0.00
0.00
0.00
0.00
Division: 15100 – FINANCIAL ADMINISTRATION Total:
0.00
0.00
0.00
0.00
211-32100-573000
PROPERTY & EVIDENCE F
0.00
5,998.00
0.00
0.00
Division: 32100 – POLICE ADMINISTRATION Total:
0.00
5,998.00
0.00
0.00
Fund: 211 – PROPERTY AND EVIDENCE FUND Total:
0.00
5,998.00
0.00
0.00
CONFISCATED ASSETS
Account Number
Account Description
FY 2023 BUDGET
FY 2024 BUDGET
FY 2025 APPROVED
FY 2026 PROPOSED
210-15100-523901
BANK CHARGES
0.00
0.00
0.00
0.00
Division: 15100 – FINANCIAL ADMINISTRATION Total:
0.00
0.00
0.00
0.00
Fund: 210 – CONFISCATED ASSETS FUND Total:
0.00
0.00
0.00
0.00
ARPA
Account Number
Account Description
FY 2023 BUDGET
FY 2024 BUDGET
FY 2025 APPROVED
FY 2026 PROPOSED
230-15100-512200
MEDICARE 1.45%
0.00
0.00
0.00
0.00
230-15100-512900
INCENTIVE PROGRAM
0.00
49,559.26
0.00
0.00
230-15100-512901
EMPLOYEE RETENTION PROGRAM
0.00
0.00
0.00
0.00
230-15100-531110
COMPUTER EXPENSE
0.00
0.00
0.00
0.00
Division: 15100 – FINANCIAL ADMINISTRATION Total:
0.00
49,559.26
0.00
0.00
230-15650-531143
SECURITY UPGRADE
0.00
0.00
0.00
0.00
230-15650-541143
FACILITIES SECURITY EQUIPMENT
0.00
0.00
0.00
0.00
230-15650-541200
SITE IMPROVEMENTS
0.00
27,585.94
0.00
0.00
Division: 15650 – GOVERNMENT BUILDINGS/PROPERTY Total:
0.00
27,585.94
0.00
0.00
230-32100-541492
POLICE BUILDING CONSTRUCTION
0.00
0.00
0.00
0.00
230-32100-541493
TECHNOLOGY
0.00
0.00
0.00
0.00
230-32100-542200
VEHICLES
0.00
0.00
0.00
0.00
230-32100-542500
EQUIPMENT
0.00
0.00
0.00
0.00
Division: 32100 – POLICE ADMINISTRATION Total:
0.00
0.00
0.00
0.00
230-42500-521230
ENGINEERING FEES – STORMWATER
0.00
0.00
0.00
0.00
230-42500-541490
STORMWATER CONSTRUCTION
0.00
41,354.72
0.00
0.00
230-42500-542510
STORMWATER REPAIR
0.00
0.00
0.00
0.00
Division: 42500 – STORMWATER Total:
0.00
41,354.72
0.00
0.00
230-43300-521200
PROFESSIONAL SERVICES – SEWER
0.00
0.00
0.00
0.00
230-43300-521230
ENGINEERING FEES – SEWER
0.00
0.00
0.00
0.00
230-43300-541489
SEWER CONSTRUCTION
0.00
448,454.83
0.00
0.00
Division: 43300 – SEWER Total:
0.00
448,454.83
0.00
0.00
230-44200-521200
PROFESSIONAL SERVICES – WATER
0.00
0.00
0.00
0.00
230-44200-521230
ENGINEERING FEES – WATER
0.00
0.00
0.00
0.00
230-44200-541491
WATER CONSTRUCTION
0.00
79,870.00
0.00
0.00
Division: 44200 – WATER Total:
0.00
79,870.00
0.00
0.00
230-61900-522328
BLDG & FACILITY REPAIRS MMC
0.00
7,336.33
0.00
0.00
Division: 61900 – CITY EVENTS Total:
0.00
7,336.33
0.00
0.00
230-75100-523950
ED CITYWIDE MARKETING
46,231.35
2,500.00
0.00
0.00
230-75100-523951
BOOTH
4,750.00
3,877.87
0.00
0.00
230-75100-523952
ED CONNECTION CENTER OUTFITTING & OPERATIONS
15,000.00
0.00
0.00
0.00
230-75100-523953
ED SB ENTREPRENEURSHIP PROGRAM
0.00
0.00
0.00
0.00
230-75100-523954
ED SB EVENTS & MEETINGS PROGRAM
15,000.00
0.00
0.00
0.00
230-75100-523955
ED WORKFORCE DEVELOPMENT
10,000.00
0.00
0.00
0.00
230-75100-523956
ED PUBLIC ARTS PROGRAM
20,000.00
4,500.00
0.00
0.00
230-75100-523957
ED DTWN RED & ED STRATEGY IMPLEMENTATION
3,464.00
0.00
0.00
0.00
230-75100-523958
ED DTWN BANNER PROGRAM
5,270.00
0.00
0.00
0.00
230-75100-523959
ED RESTAURANT WEEK REWARDS PROGRAM
10,000.00
0.00
0.00
0.00
230-75100-523961
ED DOWNTOWN BUSINESS ASSISTANCE
20,970.00
0.00
0.00
0.00
230-75100-523962
ED KEEP STOCKBRIDGE BEAUTIFUL
10,000.00
0.00
0.00
0.00
230-75100-523963
ED SB FACADE & BLDG IMPROVEMENT PROGRAM
30,000.00
21,050.00
0.00
0.00
230-75100-523964
ED STOCKBRIDGE BUSINESS PARTNERSHIP
10,000.00
0.00
0.00
0.00
230-75100-523965
ED STOCKBRIDGE WAYFINDING
551,104.00
0.00
0.00
0.00
Division: 75100 – ECONOMIC DEVELOPMENT Total:
751,789.35
31,927.87
0.00
0.00
Fund: 230 – ARPA – LOCAL FISCAL RECOVERY FUND Total:
751,789.35
686,088.95
0.00
0.00
GRANTS ADMINISTRATION
Account Number
Account Description
FY 2024 BUDGET
FY 2024 BUDGET
FY 2025 APPROVED
FY 2026 PROPOSED
255-15100-531700
MISCELLANEOUS EXPENSE
1,000,000.00
0.00
0.00
0.00
Division: 15100 – FINANCIAL ADMINISTRATION Total:
1,000,000.00
0.00
0.00
0.00
255-32100-511100
REGULAR EMPL. SALARIES – POLICE GRANT
0.00
233,686.83
420,000.00
420,000.00
255-32100-512100
GRP INSRC MEDICAL/DENTAL – POLICE GRANT
0.00
101,566.48
101,567.00
101,567.00
255-32100-512110
GROUP INSURANCE LIFE – POLICE GRANT
0.00
843.33
844.00
844.00
255-32100-512200
GROUP INSURANCE VISION – POLICE GRANT
0.00
534.25
535.00
535.00
255-32100-512700
MEDICARE 1.45% – POLICE GRANT
0.00
3,100.98
3,101.00
3,101.00
255-32100-521100
WORKER’S COMPENSATION – POLICE GRANT
0.00
0.00
0.00
0.00
255-32100-521105
2022 LEMHWA CONSULTANT FEES
0.00
63,960.00
63,960.00
100,000.00
255-15110-521202
GRANTS MATCH
0.00
0.00
572,261.00
800,000.00
255-32100-523500
2022 LEMHWA TRAVEL
0.00
1,089.38
0.00
0.00
255-32100-523846
LEMHWA
0.00
0.00
0.00
0.00
255-32100-531140
2022 LEMHWA SUPPLIES & MATERIAL
0.00
2,999.00
0.00
0.00
255-32100-531145
ASSIST/MENTAL HLTH
0.00
0.00
0.00
0.00
255-32100-531150
SUPPLIES & MATRL. CRIMINAL JUSTICE
0.00
0.00
0.00
0.00
255-32100-531155
COORD. CNCL PRG
0.00
11,797.94
0.00
0.00
255-32100-531600
SMALL EQUIP – PUB. SFTY & VIOLENT CRIME GRANT
0.00
22,130.00
0.00
0.00
255-32100-531700
2022 LEMHWA MISCELLANEOUS EXPENSE
0.00
0.00
0.00
0.00
255-32100-531750
UNIFORMS – BULLETPROOF VEST GRANT
0.00
0.00
0.00
0.00
255-32100-542500
EQUIPMENT – CRIMINAL JUSTICE COORD.
0.00
12,161.00
0.00
0.00
255-32100-542505
CNCL PRG GRANT
0.00
227,800.00
0.00
0.00
255-32100-551100
2022 DE MINIMIS 10% LEMHWA INDIRECT COST
0.00
1,800.00
0.00
0.00
Division: 32100 – POLICE ADMINISTRATION Total:
0.00
683,469.19
1,162,268.00
1,426,047.00
255-42200-522243
LMIG
0.00
373,698.20
0.00
500,000.00
255-42200-541490
LMIG 2024
0.00
0.00
0.00
0.00
255-42200-541491
LMIG 2025
0.00
0.00
305,815.00
0.00
Division: 42200 – PUBLIC WORKS Total:
0.00
373,698.20
305,815.00
500,000.00
Division: 43300 – SEWER Total:
255-74100-523847
LCI 2021 BICYCLE CONNECTIVITY
0.00
0.00
0.00
Division: 74100 – PLANNING & ZONING Total:
0.00
0.00
0.00
Fund: 255 – GRANT FUND Total:
1,000,000.00
1,057,167.39
1,468,083.00
HOTEL/MOTEL
Account Number
Account Description
FY 2023 BUDGET
FY 2024 BUDGET
FY 2024 APPROVED
FY 2026 PROPOSED
275-15100-523300
ADVERTISING
0.00
0.00
0.00
0.00
275-15100-523310
PUBLIC NOTICES
0.00
800.00
0.00
800.00
275-15100-523400
PRINTING & BINDING
0.00
0.00
0.00
0.00
275-15100-523600
DUES & FEES
0.00
2,000.00
0.00
2,000.00
275-15100-531700
MISCELLANEOUS EXPENSE
0.00
0.00
0.00
0.00
275-15100-531709
CITY REBRANDING INITIATIVE
0.00
0.00
0.00
0.00
275-15100-531710
RSVP Program for Main Street
0.00
0.00
0.00
0.00
275-15100-531713
PROMOTIONAL SUPPLIES – MAIN STREET
7,719.11
7,000.00
0.00
5,000.00
275-15100-531714
PROMOTIONAL SUPPLIES – ECO DELVP
2,896.00
3,000.00
0.00
2,000.00
275-15100-531717
PROMOTIONAL SUPPLIES – MERLE
0.00
5,000.00
0.00
2,000.00
275-15100-531718
ADVERTISEMENT – MERLE
0.00
20,000.00
0.00
10,000.00
275-15100-531719
ADVERTISEMENT – TED
0.00
5,000.00
0.00
3,000.00
275-15100-531720
CITY QUARTERLY NEWSLETTER
12,765.01
20,000.00
0.00
10,000.00
275-15100-531726
CITY EVENT, Food Trucks
0.00
0.00
0.00
0.00
275-15100-531730
TOURISM
44,426.53
107,200.00
4,231.54
80,000.00
275-15100-531731
CITY EVENT, SOUNDS OF SUMM
0.00
0.00
0.00
0.00
275-15100-531732
CITY EVENT, CITIES WEEK
0.00
0.00
0.00
0.00
275-15100-531733
CITY EVENT, MEMORIAL MARCH
0.00
0.00
0.00
0.00
275-15100-531736
CITY EVENT, STARS OVER STO
0.00
0.00
0.00
0.00
275-15100-531737
VETERAN’S DAY PARADE
0.00
0.00
0.00
0.00
275-15100-531738
VETERANS DAY DINNER
0.00
0.00
0.00
0.00
275-15100-531739
MAYORS BIKE RIDE
0.00
0.00
0.00
0.00
275-15100-531743
CITY EVENT, CIRCUS
0.00
0.00
0.00
0.00
275-15100-531495
BEAUTIFICATION
45,991.00
0.00
0.00
0.00
275-15100-542500
OTHER – WAYFINDING SIGNAGE
3,257.96
10,000.00
0.00
10,000.00
275-15100-572000
H.C. CHAMBER 2% / 3.5% 8/1/2015
444,532.16
195,000.00
74,906.51
300,000.00
275-15100-611251
TRANSFER TO/FROM GEN.FUND
0.00
0.00
0.00
0.00
Division: 15100 – FINANCIAL ADMINISTRATION Total:
561,587.77
375,000.00
79,138.05
275-90000-611251
TRANSFER TO/FROM GEN.FUND
–
–
–
–
Division: 90000 – OTHER FINANCING USES Total:
–
–
–
Fund: 275 – HOTEL/MOTEL TAX Total:
561,587.77
375,000.00
79,138.05
SPLOST V
Account Number
Account Description
FY 2023 ACTUAL
FY 2024 BUDGET
FY 2025 APPROVED
FY 2026 PROPOSED
320-15100-523901
BANK CHARGES
0.00
0.00
0.00
0.00
Division: 15100 – FINANCIAL ADMINISTRATION Total:
0.00
0.00
0.00
0.00
320-15650-542300
POLICE STATION – FURNITURE
140,676.31
0.00
0.00
0.00
Division: 15650 – GOVERNMENT BUILDINGS/PROPERTY
140,676.31
0.00
0.00
0.00
320-42200-522241
LMIG ROAD PAVING
2,464,885.63
0.00
(29,556.35)
540,000.00
320-42200-541404
SIDEWALKS-SPOST V
104,120.90
0.00
165,879.10
0.00
Division: 42200 – PUBLIC WORKS Total:
2,569,006.53
0.00
136,322.75
540,000.00
320-43300-541108
WTP CAPACITY REVIEW
16,200.00
0.00
46,807.50
284,500.00
320-43300-541405
WALTER WAY LIFT STATION
0.00
0.00
0.00
0.00
320-43300-541483
WWTP IMPROVEMENTS
128,500.00
0.00
326,583.78
0.00
Division: 43300 – SEWER Total:
144,700.00
0.00
373,391.28
284,500.00
320-44200-523849
CONTRACT LABOR – WATER IN
0.00
0.00
272,282.50
180,900.00
320-44200-531140
SUPPLIES & MATERIALS – WATER
114,600.00
0.00
0.00
0.00
320-44200-542511
WATER METER REPLACEMENT
63,845.48
0.00
0.00
0.00
Division: 44200 – WATER Total:
178,445.48
0.00
272,282.50
180,900.00
320-62200-521220
PROFESSIONAL SERVICES
123,906.56
0.00
94,259.72
680,802.91
Division: 62200 – PARKS Total:
123,906.56
0.00
94,259.72
680,802.91
320-90000-612020
TRANSFER TO/FROM GENERAL
2,946,323.50
0.00
0.00
0.00
Division: 90000 – OTHER FINANCING USES Total:
2,946,323.50
0.00
0.00
0.00
Stormwater
77,163.00
Fund: 320 – SPOST V FUND Total:
6,103,058.38
0.00
876,256.25
1,763,365.91
I stopped at page 80. As to my first pronouncement, you have to try very hard to make a PDF that hard to read. Transparency only ever becomes worse in the City of Stockbridge. Some of the pages right after GIS planning seem to be non-sequitirs to an old 2022 budget.
As news cameras focus on Councilman Elton Alexander’s attempts at municipal cleanup, citizens and independent watchdogs must look past the superficial photo opportunity and toward the financial chasm consuming Stockbridge, Georgia. A performance of civic duty, such as picking up trash, will not conceal the widespread financial malfeasance, systemic ethical failures, and documented pattern of retaliation that has cost taxpayers millions and led to calls for a racketeering investigation.
The city’s financial wreckage far from being a simple administrative “failure of process” is a compounding crisis stemming from pervasive Management Oversight.
The public relations narrative of a city getting its house in order sharply contradicts the cold reality of official financial audits and public records:
Massive Budget Shortfalls: The City Council had to amend its budget by $32.9 million to account for documented “mismanagement” of funds. The city’s finance director confirmed the severity of the crisis, publicly stating that the council was relying on flawed data: “We misled you.”
Amphitheater as the Epicenter: The Stockbridge Amphitheater, designed to be self-sufficient, has consistently operated at a loss. Its expenses reportedly soared from 2 million to 8.1 million. Audit findings repeatedly flagged significant adjustments needed to the General and Amphitheater Funds due to improper expenditure recording and a lack of missing supporting documentation and approvals. The following notes from the 2024 audit that was released in October, aren’t part of this year’s previous $32,900,000 budget amendment of 2022-2023 shortfalls into the 2024 budget. We’ll have to amend the 2025 budget to address this year’s $2,000,000 amphitheater shortfall. We haven’t built the soundbooth yet, in four years time. The booth will be another $400K.
Revenue & Receivables Management (Finding 2024-001): Significant adjustments were required across multiple funds (General, ARPA, Grants, SPLOST V, Solid Waste, Conference Center, Hotel/Motel Tax) to correctly state revenue, receivables, unearned revenue and allowances for doubtful accounts. The total impact was substantial.
Interfund Activity (Finding 2024-002): Interfund receivables, payables, and transfers were improperly stated requiring adjustments across many funds including General, ARPA, Grants, City-wide Capital Projects, Downtown Development, City-wide Development, Public Facilities Authority, Stormwater, Conference Center, Cemetery, SPLOST IV, and Urban Redevelopment.
Prepaid Assets & Expenses (Finding 2024-003): Adjustments were needed in General, ARPA, City-wide Development, Water/Sewer, Stormwater, Solid Waste, Conference Center, Amphitheater, and Hotel/Motel Tax funds to properly record prepaid assets and expenses.
Inventory (Finding 2024-004): The Water & Sewer Fund required an adjustment due to a lack of reconciliation between the general ledger and physical inventory counts.
Amphitheater Expenditures (Finding 2024-006): Significant adjustments were needed to the General and Amphitheater Funds due to improper expenditure recording, lack of approvals, and missing supporting documentation. This was a major finding with large dollar amounts.
Accrued Liabilities (Finding 2024-007): Adjustments were required in the SPLOST IV fund for improperly stated accrued liabilities.
Depreciation (Finding 2024-008): Depreciation was incorrectly recorded in the General Fund, which is not appropriate under modified accrual accounting.
Capitalization of Assets (Finding 2024-009): Capital items were excluded from capital asset details in both governmental and business-type activities.
CSLFRF Reporting (Finding 2024-010): Multiple quarterly financial reports for the COVID-19 Coronavirus State and Local Fiscal Recovery Fund Grants were submitted late.
COPS Grant Reporting (Finding 2024-011): Multiple quarterly and semiannual reports for Public Safety Partnerships and Community Policing Grants were submitted late, improperly supported, or contained incorrect expenditure reporting.
Prior Year Findings: Most of the findings from the 2023 audit (001, 002, 003, 004, 005, 006) remain Unresolved or Partially Resolved as of December 31, 2024.
Click here for PDFs of the 2022-2024 FAC.GOV Financial Statement Findings & proof of late filing.
Despite all this, the city decided to spend tax money on hundreds of comped tickets to an amphitheater show. It was a $180,000 loss scheduled purposefully to coincide with the early voting stage of the election.
Concealment of Funds: Records suggest a pattern of deliberate concealment of amphitheater expenses, with costs shifted to unrelated funds “without the City Council’s knowledge or approval.” as the city has put it. This idea fails under scrutiny when you realize a councilperson, Barber has been asking for the Mauldin & Jenkins financial report for years. I know fac.gov audits are supposed to be filed yearly. And yet they weren’t, a fact noticed by hundreds of Stockbridge citizens. Finally, I find it hard to believe these people didn’t know huge catered parties they attended for four years cost tens of millions of dollars. Nor does Fox5’s Kaitlyn Pratt’s producer’s boss, evidently.
Any attempt to recast Councilman Alexander as a responsible public servant must confront his history of alleged misconduct and the resulting burden placed on Stockbridge taxpayers.
In 2021, the city’s insurer paid a massive 1.7 million settlement to Arick Whitson, owner of Georgie Championship Barbecue Co. The settlement resolved a federal lawsuit alleging deprivation of constitutional rights and retaliation. The dispute began in May2016 after Alexander allegedly visited the restaurant, ordered 60 worth of food, and then refused to pay. When asked for payment, Alexander allegedly told Whitson, “I thought you wanted to do business with the city?” before leaving without paying.
Whitson claimed that after this interaction, Alexander initiated a year-long vendetta. This harassment campaign included code enforcement officials frequently visiting the restaurant, and Whitson facing difficulties obtaining a liquor license or sign permit. Furthermore, Alexander was accused of escalating the harassment by filing false complaints and making false claims that Whitson was on the National Sex Offender Registry. Alexander even admitted in a 2019 deposition that he had used fake names online to criticize his opponents.
This scandal was so damaging that Mayor Anthony Ford and council members LaKeisha Gantt and John Blount publicly called for Alexander’s resignation, stating that the $1.725 million settlement had “brought shame to the city of Stockbridge”. Alexander, who does not support the settlement, has been subject to a “continuous pattern of disciplinary actions,” including being censured twice and facing six different ethics investigations since January 2016. More recently, he was reported to be “posted up at Merle Manders polling place bothering the mayor elect.”
The Failure of the Fourth Estate: Atlanta’s PR Machine
The focus by outlets like Fox 5 on a non-story like trash pickup, while ignoring the verifiable trail of financial devastation and alleged corruption, is a symptom of a larger regional crisis in accountability journalism.
This trend is epitomized by media that operate as little more than public relations conduits. For example, Game Changers Media Network, which promoted the Mayor’s narrative of steady governance, has demonstrable links to city officials: the proprietor’s wife holds a real estate license at METRO BROKERS INC, the same realty firm where Councilperson Elton Alexander holds his license.
This dynamic ensures that instead of conducting essential, in-depth investigations into the blatant concealment of public funds, the systematic evasion of procurement law, and the pattern of alleged extortion and retaliation that demands a racketeering inquiry, too much of the Atlanta-area media is focused on crafting PR to rehabilitate unlikable candidates with bad records. The financial facts and the systemic ethical rot in Stockbridge are the real story, not a manufactured photo opportunity meant to scrub the reputation of an official accused of long-term misconduct.
This applies to all houses on Bryant St. between East Atlanta Rd. and Lee St.
Speaking for myself very plainly. Trespassers on my property will be dealt with accordingly. This is the second and last time I’ve warned the city that unless they’re buying it, don’t fucking touch it because it’s not yours to touch. Si vis pacem, para bellum.
Councilmember Alexander inquired about the city’s Parks Master Plan, […] the East Atlanta Rd./Lee Street sidewalk project.
Mr. Aaron noted the Master Park Plan has been completed; and noted there is no official vote to move forward with the East Atlanta Road to Lee Street sidewalk project. Councilmember Alexander noted the project has been designed by Falcon Design and is appropriate to move forward as part of the Trail Plan.
Councilmember Barber noted the proposed sidewalk project is in City Council District 4,
and that she has asked for all tasks orders associated with the PATH Foundation; and asked why Falcon Design was tasked with any design associated with the Master Trail Plan.
Mr. Aaron noted the East Atlanta to Lee Street project is not part of the Master Trail Plan, noting it is a sidewalk project and the task order for the design to widen East Atlanta Rd. to Lee Street from 5’ to 10’, was signed by the former City Manager, Frederick Gardiner, and was not brought to the City Council for approval, noting it was not part of the Master Trail Plan.
Councilmember Barber requested the Minutes where the sidewalk project was approved, considering the City has approved a Master Trail Plan. Mr. Aaron stated the project was not presented to the City Council, noting the task order was in the City Manager’s signing authority for the design.
Councilmember Barber stated the city has approved a Master Trail Plan and is unclear as to why there is a separate project, specifically in Council District 4, that was not approved by the City Council; and asked where she could see the funding for the Parks Master Plan.
Mr. Aaron noted the Parks Master Plan funding is in SPLOST and is in the city’s CIP (Capital Improvement Plan). Councilmember Barber asked when the Parks Master Plan will roll out and asked for the schedule.
Mr. Aaron noted he would send the proposed schedule out that was prepared by TSW. Councilmember Alexander stated the East Atlanta Rd./Lee Street sidewalk project preceded the PATH Foundation Plan, noting Falcon Design had already been paid, and there was not a need to then pay the PATH Foundation, stating Mr. Ganther is aware that this portion of N. Henry Blvd. is going to be completed, noting they are experts at what they do, and they support the city’s trail plan; noted the idea is to form a complete circle around City Hall for total connection and to close the gap, and to continue working with the PATH Foundation, who he brought to the city, and is a member of one of their boards, and suggested Mr. Aaron and Mr. Edmondson bring the sidewalk project to the City Council ‘s next meeting for approval with the estimate ready for review at that time; noting former City Manager has paid for the task order, and there is funding in SPLOST V, SPLOST VI, Bonds, for the project and noted there is $20 million dollars for trails; and asked for the status of the Brush Creek Trail project
The narrative put forth in the article titled “Forward Focus: Mayor Anthony S. Ford on the Future of Stockbridge and the $32 Million Question” attempts to paint a portrait of steady governance and immediate financial remediation. Yet, an examination of public records, independent audits, and statements to council from staff reveals that the message of transparency disseminated by the Mayor is contradicted by systemic financial dysfunction, repeated administrative failures, and troubling entanglements between the administration and its chosen media partners.
The Source of the Spin: A Network of Convenience
The source of the Mayor’s defense, Game Changers Media Network, operates less as an independent news outlet and more as a public relations conduit. Further investigation into the network reveals potential conflicts of interest reaching directly into City Hall.
According to Georgia Real Estate Commission and Appraisers Board records dated October 20, 2025, Tabitha Jamison Mallard, the proprietor’s wife of Game Changers Media Network (License #377757), maintains an Active Status Salesperson license at METRO BROKERS INC. Crucially, this is the very same realty firm where Councilperson Elton Alexander holds his own Active Status Salesperson license (License #373521). This connection places the Mayor’s chief media ally in shared professional orbit with a sitting council member.
Game Changer’s Media Network poses with Stockbridge City’s PIO, Shana Thornton at the amphitheater.
Game Changers Media Network previously benefited from access related to the controversial VyStar Amphitheater. This is the same facility whose manager, Harold Young, was subsequently terminated amid the financial maelstrom. Public allegations and Finance Director Frank Milazi’s last appearance before council assert that no competitive sealed bid process was conducted for vendors or naming rights for the Amphitheater from 2021 through 2024, despite city requirements for procurements over $50,000 to be bid on, and despite Georgia State procurement law stating any public works project over $100,000 must be bid in the Georgia Procurement Registry.
Click here for: PDF transcript of Mr. Milazi’s September 30 Stockbridge City Council Budget Update & forthcoming amendment presentation
The Reckoning: Audit Findings vs. PR Claims
Mayor Ford contends that the $32 million issue was merely a “failure of process” that they “fixed,” assuring citizens that transfers between accounts “won’t happen again” and that “the books are corrected”. However, the detailed audit findings released publicly demonstrate that these “failures of process” were pervasive and persistent:
The city’s independent audits for fiscal years 2022 and 2023 have revealed persistent systemic financial weaknesses, with recurring fundamental failures identified repeatedly as “unresolved” from previous years (2011-2023). These serious deficiencies include repeated failure to properly capitalize millions in city assets, such as over $1.5 million in Amphitheater construction costs in 2022 alone, persistent mismanagement of receivable and revenue accounts, and chronic failures related to interfund activity.
Game Changer’s Media Networks story, published on September 30th, precedes the fac.gov 2024 Annual Financial Comprehensive Report published on October 7th. Here are my notes on the 2024 Financial Statement Findings and Questioned Costs.
Revenue & Receivables Management (Finding 2024-001): Significant adjustments were required across multiple funds (General, ARPA, Grants, SPLOST V, Solid Waste, Conference Center, Hotel/Motel Tax) to correctly state revenue, receivables, unearned revenue and allowances for doubtful accounts. The total impact was substantial.
Interfund Activity (Finding 2024-002): Interfund receivables, payables, and transfers were improperly stated requiring adjustments across many funds including General, ARPA, Grants, City-wide Capital Projects, Downtown Development, City-wide Development, Public Facilities Authority, Stormwater, Conference Center, Cemetery, SPLOST IV, and Urban Redevelopment.
Prepaid Assets & Expenses (Finding 2024-003): Adjustments were needed in General, ARPA, City-wide Development, Water/Sewer, Stormwater, Solid Waste, Conference Center, Amphitheater, and Hotel/Motel Tax funds to properly record prepaid assets and expenses.
Inventory (Finding 2024-004): The Water & Sewer Fund required an adjustment due to a lack of reconciliation between the general ledger and physical inventory counts.
Amphitheater Expenditures (Finding 2024-006): Significant adjustments were needed to the General and Amphitheater Funds due to improper expenditure recording, lack of approvals, and missing supporting documentation. This was a major finding with large dollar amounts.
Accrued Liabilities (Finding 2024-007): Adjustments were required in the SPLOST IV fund for improperly stated accrued liabilities.
Depreciation (Finding 2024-008): Depreciation was incorrectly recorded in the General Fund, which is not appropriate under modified accrual accounting.
Capitalization of Assets (Finding 2024-009): Capital items were excluded from capital asset details in both governmental and business-type activities.
CSLFRF Reporting (Finding 2024-010): Multiple quarterly financial reports for the COVID-19 Coronavirus State and Local Fiscal Recovery Fund Grants were submitted late.
COPS Grant Reporting (Finding 2024-011): Multiple quarterly and semiannual reports for Public Safety Partnerships and Community Policing Grants were submitted late, improperly supported, or contained incorrect expenditure reporting.
Prior Year Findings: Most of the findings from the 2023 audit (001, 002, 003, 004, 005, 006) remain Unresolved or Partially Resolved as of December 31, 2024.
Overall Cause: The root cause of nearly all findings is identified as Management Oversight.
Click here for PDFs of the 2022-2024 FAC.GOV Financial Statement Findings & proof of late filing.
The alleged accounting errors appear to have been instrumental in masking the Amphitheater’s staggering overruns, with practices identified specifically for concealing expenses by improperly shifting costs to unrelated funds, such as the “citywide projects” fund. Despite the Mayor’s assertion that the Amphitheater construction cost was “paid off” in August. As recently as the financial update at the Sep. 30 city council meeting, in the documents & video of Mr. Milazi above, the finance department acknowledged an upcoming budget amendment to cover a $1.6 million amphitheater shortfall for 2025, with only $1 million collected against its budgeted revenue of $2.6 million for the year. As previously discussed on this site there’s a plan to build the missing $390,000 sound booth. If you owe for $390,000 in construction on an unfinished project then the amphitheater, by no measure of logic, is payed off.
$390,000 Amphitheater Soundbooth Proposal
The scale of misinformation provided to elected officials prior to these 2022-2024 corrections was confirmed by the City’s current finance director. In a public statement on September 30, 2025, Mr. Milazi stated plainly that the council was relying on flawed data: “There were two sets of reports that were being made, and the reports that were being given to you to make wise decisions were not. So we misled you.”
Amphitheater as the economic driver of downtown
As Game Changer’s says “amphitheaters rarely mint profits, but they do fuel downtown restaurants, hotels, and small businesses.” And where they quote Mayor Ford as saying “Break-even is a win when you count the spillover.” The coming budget amendment for the amphitheater & the sound booth will be ~$2,000,000. You’ll have to judge for yourself whether 2 restaurants constitutes a “Break-even” cost.
The city’s own advisory firm, KBA wrote on page 46 in the Economic Development 2024 Update, “While partially due to the disconnect between the amphitheater and downtown retail, the absence of sustaining day-time and night-time users leaves a critical gap in revitalization efforts. Investment in Downtown Stockbridge should become more focused on activation and engagement with a renewed focus on “live-work” aspects. The city has made a promising step forward by incorporating municipal office space along Main Street. While the office market continues to evolve following the 2020 pandemic, attracting co-working or providing incubator spaces downtown can increase foot traffic and interest. Given the changing landscape of office users, increasing residential is a critical goal to realizing vibrancy in the heart of Stockbridge.”
The Price of Accountability: Departures in the Executive Office
The current administrative turmoil follows directly from the financial recklessness of previous management, a period characterized by reckless spending and a palpable fear of legal repercussions among staff. It was during a period of unbudgeted spending and improper fiscal activity that then-City Manager Frederick Gardiner warned the council about the severe consequences of their actions, cautioning against activity that could lead to legal action against him personally: “um as I mentioned to you guys at the last city council meeting Frederick don’t look good in jumpsuit I ain’t 6’5 350 LBS to fight so I ain’t going to jail.”
The city manager who publicly stated he wasn’t willing to risk incarceration for the city’s financial decisions, Frederick Gardiner, submitted the proposed FY 2025 budget memorandum dated November 4, 2024, but later departed the city’s employ. His departure occurred amidst a period of immense scrutiny, following his time in a management role that was seemingly caught between council demands and legal compliance.
The evidence suggests that the narrative of simple “process failure” is a gross understatement aimed at shielding the administration from accountability. The audit findings reveal ongoing operational neglect, and the public statements made by former and current staff highlight the severe consequences of operating outside legal and fiscal guardrails, consequences that ultimately drove leadership changes at the highest levels of the city. The facts, laid bare in the official record, stand in sharp contradiction to the public relations spin provided by the Mayor’s favored media outlet.
Why? Marion has gone down the long road through the courts like I did. Between me and her, you can call any politician you want now. You can repost things on facebook and the cops won’t come harass you as they once did Dr. Flynn over the Eagle’s Landing cityhood. Finally, mayhap you find yourself reading the dissent in Marion’s battle against a false TPO. I won’t name names, but will say that dissent was written by someone with a vested monetary interest in this county. I think, if what our dissenter wrote was true. Then you wouldn’t find Marion sitting in the front row with me or supporting Conserve Henry, who are left leaning despite the moniker, but I digress. I’m willing to work with anyone who understands, regardless of party, we’re being buried under a pile of debt to pay the local, powerful law firm that is profiting from amphitheater construction. There are many accounts of Ms. Calhoun working directly with the homeless, fearless as she is. We’ve heard not one word from the seated council on a plan for these people.
I will recognize the Mayor and Sheriff just volunteered for the Carter Foundation on a housing project 1 mile from here. And you must recognize the Sheriff’s image is tarnished by the many preventable deaths in his jail. While 3 or more deputies covered the many amphitheater shows. In retrospect, I think we can recognize those deputies had bigger priorities than covering a treasury draining music venue. I remember after the Eagle’s Landing cityhood battle, the Carter Foundation came behind the initial “journalist” in the hit job on me. Once I proved them wrong, Christie Ethridge now Diez became a “Carter Mental Health” fellow. It will suffice to say, philanthropy doesn’t serve the the surface purpose they present. Their role has become skewing public perception, to rehabilitate the image of candidates and PR people they perceive to be in the cocktail philanthropy circuit they’re on together.
Mr. Willie Carter? Because Mr. Cloud is a tacit incumbent. I’ve seen Mr. Willie Carter at every meeting asking pertinent questions in seeking the truth. I saw him sit thru monotonous ethics meeting where nothing happened. While giving his comment at these meetings I’ve seen Mr. Carter be forewarned “no campaigning” before he could utter a word. Meanwhile, Antwan is taking pictures with a city nametag. Elton Alexander is wearing an Antwan Cloud shirt at the candidates forum. So, rather than vote for what the city & people like El Mahdi want to endorse, I’d vote for Willie. I’ve watched this man do the work in an example below. This is one of ~50 times Willie has spoken. I’ve never seen Antwan at a meeting.
Pardon me, that meeting was the 13th. Link in bio.
The person I’ll be voting for for mayor is Jayden. However, this comes with a warning that if you take up the responsibility of the city’s redevelopment plan. I’ll invoke your name aside the loss of my home. Forever, if I have to. Until the idea sticks that you have to pay to acquire private property, rather than “tap it with the blight stick” and take it, while handing me a bill for the egregious violation “dangerous blight.”
To those who don’t live in downtown and have to put up with the noise from the amphitheater. Do us a solid here, folks. So we can have the amphitheater drive business without bothering 1500 people and running the city into the ground. Let’s stop doing favors for certain Eagle’s Landing residents & “non-profit” partners.
It’s time to build out the downtown. This is not, nor ever will be a paid endorsement. Yes, I do live downtown.