Category: Budget, Audits & P-Cards

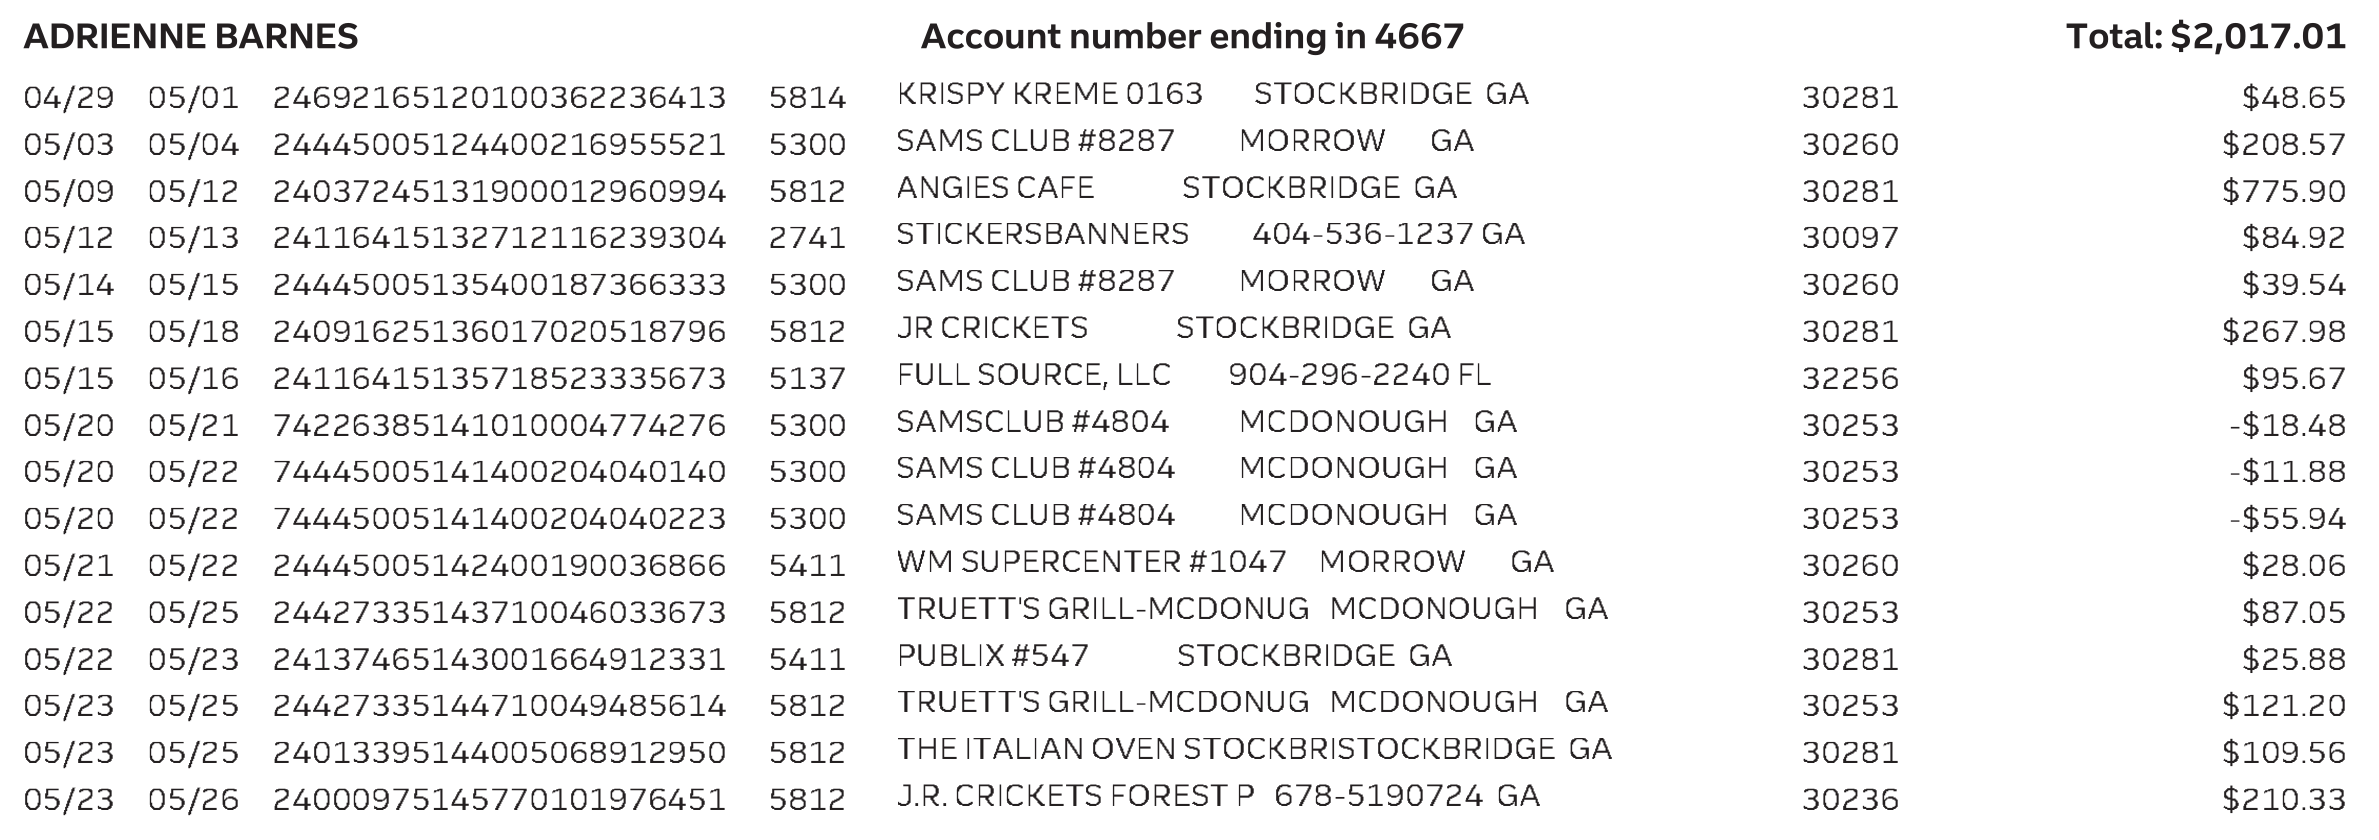
  • A Glimpse Into Citywide P-Card Usage

    A Glimpse Into Citywide P-Card Usage

    All figures verified against the raw bank statements (17 Truist One Card billing cycles, Feb 2025 – Jun 2026; 2,793 transactions, $744,442.38) and the WEX fuel export (July 2024 – July 2026; 18,402 fills, $822,321.13). Department assignments come from the City’s own published staff directories, the fuel export’s department field, and public employment records.


    The card program

    Forty-one city purchasing cards are in circulation. Sorted by department, the spending looks like this:

    DepartmentCardsTxnsTotalShare
    Events & Conference Center4603$177,261.7823.8%
    Administration & Finance (incl. Procurement/Purchasing)8476$149,569.2620.1%
    Police3576$139,172.5618.7%
    City Manager’s Office3297$67,830.339.1%
    City Council (6 seats)6131$44,397.596.0%
    Public Works (incl. water/sewer/sanitation admin)4140$37,549.015.0%
    Community Development1148$31,538.454.2%
    Human Resources4104$27,629.683.7%
    Economic Development / DDA271$20,399.322.7%
    Mayor’s Office156$13,041.011.8%
    City Clerk’s Office180$13,017.661.7%
    Municipal Court133$5,125.790.7%
    Business Services118$4,443.100.6%
    Not attributable to a department260$13,466.841.8%
    Total412,793$744,442.38

    Three departments — Events, Administration & Finance, and Police — account for 62.6% of everything charged to a city card in this period. One card in the Events department alone carries $114,211.02 (15.3%).


    The one card that is its own department

    The Events & Conference Center’s largest card deserves separate treatment because its volume reshapes the whole program. In 15 billing cycles: 386 transactions, $114,211.02, average charge $315.64, single largest $5,015.35 (a peer-to-peer payment). August–September 2025 alone is $33,020.85 — 29% of the card’s two-year total in two months, consistent with fall festival season but meaning the city’s entire event spend for that season ran through one card with no visible purchase-order structure.

    Where that money went (verified rollup, reconciles to the penny):

    UseAmount
    Printing / signage / marketing$16,853.27 (66 txns)
    Grocery / warehouse club cash-and-carry$13,605.02 (61 txns)
    Peer-to-peer payments to individuals (PayPal)$10,440.35 (10 txns)
    Hotel — inside the city limits$9,101.28 (19 txns)
    Hotel — elsewhere (airport, Nashville, other)$8,790.11 (18 txns)
    Talent booking & music licensing$7,669.16 (11 txns)
    Amazon marketplace (unitemized)$7,150.19 (55 txns)
    Event services (flowers/balloons)$6,847.03 (12 txns)
    Square-network payments to local vendors$5,006.51 (18 txns)
    Self-storage$3,033.20 (6 txns)
    Dining$2,388.34 (21 txns)
    Airfare$1,767.90 (4 txns, all booked the same day)
    Office supplies$1,491.99 (9 txns)
    Other (software, apparel, hardware, transport)$20,066.67 (76 txns)

    The hotel spend splits into two problems. $9,101.28 was charged at one hotel inside the city the cardholder works for — including a single $4,298.96 charge and a three-day burst of fifteen charges totaling $6,420.92, eight of them $131–$154 each (one room-night apiece). Another $8,790.11 went to hotels nowhere near a Stockbridge event: an airport Westin ($4,618.24, including the same $1,559.30 charge twice) and a Grand Hyatt in Nashville ($1,294.87).

    The peer-to-peer money is the structural problem. Ten PayPal payments to six recipients — $5,015.35 to one of them in a single charge — plus $3,969.70 across nine Square charges to one vendor. These are vendor-sized payments made without vendor infrastructure.


    What each department charged that taxpayers shouldn’t fund

    Sorting all 2,793 transactions through one classifier (each transaction counted once, in its best-fit category), the categories a taxpayer would reasonably expect NOT to fund on a city card total $132,328.68 across 519 transactions — 17.8% of all card spend:

    CategoryAmountTxns
    Dining, fast food & catering$67,318.51315
    Payment apps to named individuals (PayPal / Cash App / Venmo / Zelle)$25,034.0534
    Clothing & personal retail$16,184.8874
    Hotel rooms in our own city$11,383.2321
    Entertainment & amusements$7,926.7726
    Florists, gifts & balloons$4,279.1325
    Personal grooming$277.114
    Sports betting (net of reversals)−$75.0020
    Total$132,328.68519

    A further $18,609.24 (49 txns) ran through Square, reported separately because most of it is small local vendors.

    Now the same improper-spend lens, by department:

    DepartmentImproper-category $TxnsShare of that dept’s spend
    Events & Conference Center$51,730.1613829.2%
    Administration & Finance$24,300.328216.2%
    City Manager’s Office$16,275.478924.0%
    Police$14,581.978010.5%
    Public Works$7,375.861719.6%
    Unattributed$5,988.782244.5%
    Human Resources$4,379.522315.9%
    Mayor’s Office$2,076.642715.9%
    Clerk’s Office$1,535.441011.8%
    Community Development$1,472.7174.7%
    Economic Development$1,120.48105.5%
    Municipal Court$733.73514.3%
    Business Services$547.07412.3%
    City Council$210.5350.5%

    The Events department carries almost 40% of the program’s improper-category dollars — but nearly half its own spend falls in those categories, driven by person-to-person payments, in-city hotel rooms, and the festival-season dining that a public-events operation inevitably generates. The City Manager’s Office and Public Works run improper-category rates above 19%; the Council, by contrast, is effectively clean at 0.5%. That is “clean” if you don’t count this money as buying their next election.

    Dining alone — $67,318.51 across 315 charges — is spread through almost every department: 35 of 41 cards bought food. The largest single catering charges run from $3,150.00 (one caterer, two charges) down through $2,515.21 (a Birmingham, AL caterer), $1,780.00, $1,517.50, $1,200.00, $1,024.05, and $1,000.00. Two Stockbridge Chick-fil-A locations absorbed $1,560.22 and $1,387.60; one local restaurant took $1,773.86 across eight visits; another $1,336.65 across four.

    Grocery and warehouse-club buying — Publix, Walmart, Sam’s Club, Costco — adds a further $68,945.03 across 525 transactions of cash-and-carry purchasing done on cards instead of through vendor accounts.


    Reversals: the quiet remedy — and the one exception

    The statements contain 176 reversal transactions totaling $43,634.50, spread across 30 of the 41 cardholders. Three-quarters of everyone who held a card got at least one charge quietly credited back. The reversals include:

    • Online gambling, reversed to near-zero. Sports-betting app charges appear on three management cards (HR, IT, Events): $505.00 charged, $580.00 credited, net −$75.00. The city’s entire response to gambling on public cards was an accounting adjustment. No discipline appears in the record.
    • Luxury and personal charges, reversed. One HR card carries a $2,543.70 demolition charge, a $1,349.38 luxury-apartment charge, a $1,000 custom-jewelry charge, and a $945.57 leasing charge — every one credited back, along with home cable/internet bills. The cardholder separated in September 2025; the reversals ran through November.
    • The same quiet fix across the program. The Clerk’s Office received $4,643.15 in reversals (legitimate convention-registration refunds, for the record), Public Works $4,159.59, the City Manager’s Office $2,824.00, and two dozen more cardholders all received credits without consequence.

    Set against that backdrop: the removed mayor. His personal-use charges — restaurants, clothing, a haircut, a movie — totaled roughly $4,000, and he repaid them. His entire two-year card history shows a single reversal, $35.76. He is the only cardholder in this dataset removed from office over P-card use.

    The question the city has never answered: why was the remedy for everyone else — repay and reverse, no discipline — denied to the one elected official who actually repaid? If a $1,349.38 luxury-apartment charge on an HR card is handled with a quiet credit, and a $505.00 gambling tab across three directors’ cards nets to zero without a single termination, what made repaid restaurant meals the exception that justified removal?


    The fuel bill, by department

    The WEX export is fuel only: $822,321.13 across 18,402 fills over 25 months — roughly $411,160/year, $32,893/month, $44.69 per fill. By the department field in the city’s own export:

    DepartmentFillsTotalShare
    Police12,513$501,629.2561.0%
    Public Works (roads/maintenance)2,356$136,401.5416.6%
    Water & Sewer1,646$90,496.4511.0%
    Sanitation471$29,405.043.6%
    Unassigned484$21,750.912.6%
    Water Reclamation261$13,692.671.7%
    Community Development222$11,544.881.4%
    Code Enforcement121$5,148.110.6%
    Conference Center motor pool126$4,411.750.5%
    Mayor’s Office45$2,595.530.3%
    Administration78$2,558.150.3%
    City Manager’s Office45$1,487.990.2%
    City Council30$1,100.790.1%
    Municipal Court4$98.070.0%

    Two-thirds of the fuel bill is police cars; that is normal for a department that runs shifts on the road. What is not normal:

    1. A department called “Unassigned” burned $21,750.91. 484 fills across 16 vehicle IDs with no department attached — and 401 of those 484 fills ($17,737.11) belong to a single driver, across nine different vehicle IDs, from July 2024 through March 2026. One person, no department, nine vehicles.
    2. The vehicle file can’t identify a third of the fleet. The export contains 198 card numbers, 190 vehicle/asset IDs — and only 127 distinct VINs. Sixty-five asset IDs share a VIN with another asset ID, meaning the city’s own fuel file cannot distinguish the vehicles a third of its fuel dollars flow to.
    3. Round-dollar “fills” that aren’t fills. Seventy-six fills totaling $14,800.13 are exact multiples of $100; 75 of the 76 are at Sunoco, and 54 are exactly $200.00. Round-dollar amounts at a pump are prepayments and card-loads, not measured fuel — sitting inside the fuel total unmarked.
    4. Elected-official fuel exists as its own line items. Ten vehicle IDs tagged COUNCIL (~$530/year combined) and four tagged MAYOR ($2,595.53 in 2026 alone — a run-rate well above the earlier estimate, because the mayor-tagged fuel all falls inside seven months). Small dollars; a documented per-seat take-home-vehicle culture in the city’s own export.
    5. Separated employees kept fueling. One Public Works employee retired in late 2023; the export shows his PIN buying fuel for 13 consecutive months afterward — $2,714.46 across 58 fills, almost entirely on one vehicle. A purchasing card belonging to an Economic Development director who separated in October 2025 kept charging for seven more months — roughly $5,575 net, including a $3,214.28 month in January 2026. The audit finding is the gap between separation date and card/PIN deactivation — and nobody has produced the deactivation records.

    The highest-risk pattern in the file: cash to individuals

    Across at least ten cards in six departments, the statements contain PayPal, Square, and Cash App payments naming private individuals rather than vendors — $25,034.05 across 34 transactions in the improper-category table, plus more inside the Square band. The single largest: a $3,965.50 Cash App payment to an individual in Oakland, California, from an Administration & Finance card, on 01/02/2026 — the same card, the same day, also sent $500.00 through Square to another person-named recipient. No city vendor by that name surfaces in public records.

    Person-named P2P payments are the highest-risk pattern a purchasing card can carry: no vendor documentation, no tax reporting, no competitive procurement. One religious-radio PayPal recipient appears on cards in two different departments, suggesting coordinated routing rather than isolated lapses.

    The biggest question we’re left with is who was gambling with city P-Cards, who flagged it & who was gambling with P-Cards? It could be someone was the victim of card skimming, thus, innocent. I’ll give the benefit of the doubt here. For the sake of argument, let’s say by Stockbridge & Georgia state law no rules were technically broken here. Is this spending what you would call “government spending.” I think the party, dining & grocery bill are way too high. I think, when we talk about that $32 million dollar budget amendment (among other budget fiascos), this is the spend we’re refering to.

    I’d provide more open records but we’re frozen out completely. We asked for Truist Payment Card related documents back in July. The documents seen here were not sent by the clerk’s office. After receiving these from a confidential source we inquired of the clerk as to the status of same. We received a terse note that, “our request had been received.” I suppose we can close that now and move on to District 5’s $100,000+ phone bill and the other $100,000 Verizon bill.

    How did you run up more than the city wide phone bill in your district, Mr. Mayor Alexander? 🙄


    Methodology note: department assignments were made from the City of Stockbridge’s published staff directories, the WEX export’s own “Driver Department” field, and public employment records; two cardholders (60 transactions, $13,466.84) could not be confidently assigned and are reported as “Unattributed.” Improper-category classification uses a single canonical classifier applied identically to every transaction; program totals reconcile to the statement totals to the penny. This is informational; consult a licensed attorney in the relevant jurisdiction.
  • “Not a penny missing” — until it was

    “Not a penny missing” — until it was

    I trusted Milazi, but I don’t anymore. It’s as if the man doesn’t understand people remember what he’s said in the past about the very same issue. Maybe he forgot what he swore to when the city sued Harold Young.

    Frank Milazi, Stockbridge’s City Treasurer and CFO, has spent the last year telling anyone who will listen that no city money ever went missing. His exact words, on the record.

    “Council being misled”

    File: 2025-07-15_Rescheduled_Regular_Council_Meeting_transcript.md

    Councilwoman Gantt asks whether the budget documents the council had been approving were accurate. Milazi answers:

    [3:19:19 – 3:19:23] — “No. They were not accurate. That’s it. So the documents that we received looked as if we were on budget.”

    [3:19:27 – 3:19:33] — “That is correct. That’s where my uh talking was we let you down.”

    [3:19:33 – 3:19:53] — “Yes. I didn’t know. I did mention that and I’m saying today again we let you down, hopefully, from now going forward.”

    Then Gantt, turning it back on the council, says “you didn’t let us down. We did. You weren’t here” — Milazi was hired later and is admitting the documents his office inherited and handed the council were wrong.

    [3:20:13 – 3:20:32] — “We received reported reports. We received budgets. We received spreadsheets, and the numbers were increased. Incorrect, but the numbers appeared to be what we thought were good numbers, correct?”

    So: the council was being given reports that looked balanced but weren’t — which is the transcript’s own confirmation of “the council was misled.”

    “Controls not being in place”

    File: 2025-07-15_Rescheduled_Regular_Council_Meeting_transcript.md

    [3:16:32 – 3:16:46] — “Right, because what was being done was being done by management and staff without council. There was no budget amendment at the end of the fiscal year.”

    [3:16:53 – 3:16:57] — “So in essence it was mismanagement. Mismanagement, yes. So moving forward, we need to make sure that we have systems in place that will prevent mismanagement.”

    [3:15:53 – 3:15:58] — “There were some um s plus. We were spending but we didn’t budget. But it wasn’t brought to Mayor and Council either. It was never brought before the council.”

    [3:18:11 – 3:18:31] — “The thirty two million that they are talking about is the difference between what was budgeted and what was acted on that was not presented to council to work on it or to approve it. So the expenditures were there, but they were not approved by council.”

    File: 2025-12-08_Regular_Council_Meetings_transcript.md

    [0:54:17 – 0:54:34] — “Um what we are doing here was being done in the past, but it was being done behind the scenes that he did not have authorization of the council, because still money was being moved from one fund to the other. There were some funds that they didn’t have enough revenues. So the movement and the balancing can only be authorized by the governing body.”

    That last one is the clearest single quote: Milazi states plainly that money was moved between funds without council authorization, “behind the scenes” — which is, in his own words, why the books had to be corrected.

    At the July 15, 2025 council meeting, when a resident demanded to know where $32 million had gone, Milazi was summoned to the microphone to “put a misnomer” to rest:

    “There’s no thirty two million dollars missing in the city.”

    Then, under questioning from Councilwoman Gantt about the same number:

    “So the money is not missing. No, there’s no missing of money. But we are making it right.”

    And again, later in the same meeting:

    “So there was no money of thirty two million that went missing.”

    He repeated the line, nearly verbatim, at the September 29, 2026 meeting when the FY2025 audit was presented:

    “There has never been a missing of a penny.”

    “$32.9 million was never missing in the city of Stockbridge.”

    “There was never $32.9 million missing from the city.”

    The framing is always the same: the $32.9 million was never “missing” — it was just a budget adjustment, a reclassification, money “spent but not budgeted.” Nothing vanished. Nothing was lost. Everyone should calm down.

    The court record says otherwise.


    The account the city forgot to mention

    On August 8, 2025 — three weeks after Milazi stood before the council and declared “there’s no missing of money” — Milazi’s own finance department “discovered multiple deposits” into a bank account the city never authorized. It was held at Ameris Bank under the name “Harold J Young Stockbridge Amphitheater,” account ending in 1358.

    The account belonged to Harold Young, the amphitheater’s general manager, whom the city had terminated on June 16, 2025. It was opened in his name — personally. And it had, in the city’s own words, “received in excess of $400,000 of City funds that were budgeted for the 2025 concert series.”

    The city’s complaint is unambiguous about whose money it was:

    “Upon information and belief, the majority of the funds in the Ameris Account is City taxpayer funds.”

    And the reason the city ran to court ex parte, asking the judge to freeze the account before Young was even told, is stated flatly in Judge Veal’s order:

    “Without immediate intervention, Respondent may dispose of the Ameris Account, and the taxpayer funds believed to be held within it.”

    “There is good cause to believe that Respondent, if informed of the TRO Motion, would hide assets and destroy evidence.”

    The judge also made a finding Milazi never bothered to make at the podium:

    “During his tenure with the City of Stockbridge, Respondent was not [a] city official contemplated by City of Stockbridge Code § 3.04.030 with authority to open a bank account on behalf of the City.”

    In other words: the money did not go to a city account. It went to a private account in the name of a fired contractor — someone the city code says had no authority to hold a single city dollar.


    Milazi’s signature is on the very document that proves it

    Here is the part that should end the “not a penny missing” talking point permanently.

    The exhibit attached to the complaint — the document proving the money moved — is not a subpoenaed bank record dug up by lawyers. It is an email from Frank Milazi himself. His signature block sits at the bottom:

    Frank S. Milazi, City Treasurer/CFO

    In that email, Milazi lays out Young’s accounts in his own words:

    “The second account below is where we sent Harold reimbursements for deposits/expenses he paid for himself.”

    That second account is the Ameris account, ending 1358 — the same account a judge later froze because it held taxpayer money Young had no authority to hold. The wire detail lists a single entry: $142,500.00 to “Harold Young,” Ameris Bank, checking.

    Add to that the $15,000-a-month “consultant fee” the city paid Young to a separate Wells Fargo account — an account the city’s own complaint says Young “would regularly conduct business on behalf of the City” through — and you have the answer to the question Milazi keeps insisting no one should ask.


    So: was money missing?

    The city’s own Treasurer, in the city’s own sworn complaint, says that a fired contractor controlled a private bank account containing more than $400,000 of money “budgeted for the 2025 concert series” — money that had to be clawed back through a TRO and an asset freeze because, in the court’s words, Young might otherwise “hide assets and destroy evidence.”

    That is not a “budget adjustment.” That is not “spent but not budgeted.” That is not “a roadmap based on prior expenditures.” That is a man running city funds through his personal checking account, and a Treasurer who — while standing at the podium telling taxpayers “there’s no missing of money” — was simultaneously documenting, in his own email, $142,500 of it flowing into that exact personal account.

    Milazi’s “not a penny missing” was never a statement of fact. It was a shield. He deployed it to wave away $32.9 million of unapproved spending, and it turns out the $32.9 million story and the $400,000-in-a-private-account story are not two different things. They are the same disease: a finance office that could not — or would not — account for where the city’s money actually was.

    The city would not have filed an emergency lawsuit, and Judge Veal would not have frozen a bank account at 2 a.m., if nothing was missing. The city sued because money had to be found and pulled back. Some of the money was missing. That is the entire reason the court case exists.

    Milazi can keep saying “never a penny missing” for as long as he likes. The complaint he signed his name to says otherwise — and a Superior Court judge has already ordered the money seized back on exactly that basis.


    The same names, one venue removed

    The Harold Young account was not the first time the people now guarding Stockbridge’s amphitheater money had crossed paths with a venue money scandal.

    Sandra “Sandy” Ward-Poag was the entertainment director of the Wolf Creek Amphitheater in Fulton County. In November 2016, a county audit of that venue came back so bad the Atlanta Journal-Constitution called it “damning.” It found more than two dozen violations of county policy: cash management problems, preferential treatment for certain vendors, business done with unlicensed companies, contracts signed without county approval, fee structures changed without the commission’s sign-off — and a ticket-printing scheme that handed complimentary entry to thousands more people than allowed, overcrowding the facility.

    Ward-Poag and an assistant county manager, Lisa Rushin, were both fired in February 2017. They sued, claiming they were really terminated for whistleblowing on Commissioner Marvin Arrington Jr.’s use of the venue’s skybox for private parties. The case wound its way up to the Georgia Court of Appeals, and in May 2025 the panel ruled against them — finding that Fulton County had “legitimate, nondiscriminatory reasons” for the firings, grounded in the pair’s “own financial indiscretions” and “numerous findings of misconduct” from that same audit.

    Then the venue changed hands. South Fulton incorporated and took over Wolf Creek from Fulton County, and the man running its books as Chief Financial Officer was Frank Milazi — the same Frank Milazi who would later become Stockbridge’s City Treasurer and CFO.

    That is where the two tracks collide. In February 2026, after Harold Young was fired and the city sued him over the $400,000 in the personal Ameris account, Stockbridge needed a new general manager for its amphitheater. The person hired for the job — announced as “your new VyStar Amphitheater Stockbridge General Manager” — was Sandy L. Ward-Poag, the same woman fired from Wolf Creek after the audit that found money mishandled and tickets given away by the thousands.

    So the sequence a Stockbridge taxpayer is left to make sense of is this: the city’s Treasurer stood before the council and swore “there’s no missing of money” — while the amphitheater he oversaw had just discovered $400,000 in an ex-manager’s personal bank account and filed an emergency lawsuit to claw it back. Then, to run that same amphitheater, the city brought in a manager whose last public-venue job ended with a county audit so severe it became a two-word shorthand — “damning” — and a court ruling that her firing was justified by her own financial misconduct.

    Frank Milazi was the CFO of the city that absorbed Wolf Creek when its scandal erupted. He is the CFO of Stockbridge now. In both places, the same pattern shows up on his watch: an amphitheater, a manager, and money that the people in charge insist was never missing — until the audit, or the lawsuit, says it was.


    A note on the record

    Nothing in the public record ties Milazi to the Wolf Creek audit itself — his involvement there is as the finance chief of the successor government, and his involvement in Stockbridge is as the CFO who was serving while Ward-Poag was hired. He is not named in the Wolf Creek audit findings, and no source found for this piece asserts he personally hired Ward-Poag or was directly implicated in that scandal. Those are stated as the facts they are, and nothing more.

    Sources

    A plain-English reading of the three single-audit filings the city submitted to the Federal Audit Clearinghouse — FY2023, FY2024, and FY2025.

    For three years running, the City of Stockbridge has told the public its books are clean. The city has taken home the Government Finance Officers Association’s highest award for financial reporting, and its treasurer has stood at the podium declaring “there’s no missing of money.”

    The actual audit filings tell a different story. Every one of the three annual reports carries a clean (“unmodified”) opinion on the financial statements — but that is the only thing that is clean. The part of the audit that examines whether the city can be trusted to account for its own money has failed, every single year, in the same places.


    The headline numbers

    FY2023FY2024FY2025
    Opinion on financial statementsUnmodifiedUnmodifiedUnmodified
    Material weaknesses (internal control)YesYesYes
    Significant deficienciesYesYesNone reported
    Federal compliance opinionQualifiedQualifiedUnmodified
    Federal grant findings120
    Low-risk auditee?NoNoNo
    Total findings6115

    The three columns have one constant: the city has never once qualified as a low-risk auditee. That designation is the federal government’s way of saying “your controls are good enough that we don’t need to look too hard.” Stockbridge failed it all three years, because it carried material weaknesses forward every year.


    What a “material weakness” actually means

    The auditors (Mauldin & Jenkins, LLC) define it precisely in each report:

    “A material weakness is a deficiency, or a combination of deficiencies, in internal control such that there is a reasonable possibility that a material misstatement of the entity’s financial statements will not be prevented, or detected and corrected, on a timely basis.”

    In plain English: a material weakness means the city’s own accounting could not be trusted to catch a serious error — and, in these cases, the outside auditors had to correct millions of dollars the city had recorded wrong.


    FY2023 — four material weaknesses and a qualified federal opinion

    The FY2023 audit (filed as 2023-12-GSAFAC-0000056073) identified four material weaknesses, one significant deficiency, and one federal grant finding:

    2023-001 — Receivables and revenue. The city could not correctly state its receivables and revenue. The auditors had to post adjustments across the General Fund, the ARPA Fund, the Grants Fund, the Stormwater Fund, the Solid Waste Fund, and the Conference Center Fund — including a single ARPA adjustment of $1,626,110 of misclassified unearned revenue.

    2023-002 — Capital assets. The city simply left $2,253,737 of capital assets out of its books, plus another $1.78 million of Water & Sewer construction-in-progress.

    2023-003 — Interfund activity. Money moving between the city’s own funds was misstated. The General Fund needed $9,598,792 in transfer corrections and a $7,930,727 cash correction. The Amphitheater Fund alone required $6,357,806 of expense corrections — a number that will reappear.

    2023-004 — Prepaid assets. Misclassified prepaids across five funds.

    2023-005 — Accrued liabilities (significant deficiency). Liabilities left unrecorded in six funds.

    2023-006 — COPS grant reporting (federal finding). The city did not submit two quarterly financial reports and three semiannual performance reports on time, and five reports lacked required supporting documentation. This drove a qualified opinion on federal compliance.

    Every single 2022 finding was carried forward as “Unresolved.” The corrective action plan was signed by Lakeisha Gaines, Interim Treasurer — a placeholder name that signals the finance office itself was in turnover.


    FY2024 — eleven findings, the worst year

    The FY2024 audit (2024-12-GSAFAC-0000384683) is the low point: seven material weaknesses, two significant deficiencies, and two federal findings — eleven in total. The auditors classified them explicitly:

    • Material weaknesses: 2024-001 (receivables), 2024-002 (interfund), 2024-004 (inventory), 2024-005 (expenditures/cash), 2024-006 (Amphitheater), 2024-007 (accrued liabilities), 2024-009 (capital assets).
    • Significant deficiencies: 2024-003 (prepaid assets), 2024-008 (depreciation).

    The dollar figures are where this stops being a technicality:

    • Interfund (2024-002): the General Fund needed $10,788,213 in transfer corrections and a $6,796,573 correction to interfund receivables.
    • Capital assets (2024-009): $9,046,595 of completed projects were never moved out of “construction in progress,” meaning the city was still carrying finished projects as if they were unfinished — plus $529,298 of related depreciation.
    • Amphitheater (2024-006): the General Fund needed a $6,013,271 correction. The auditors wrote that “many disbursements did not have proper approvals by management” and “support for some disbursements was not available.”

    The two federal findings — CSLFRF (COVID relief) and COPS grants — both reported “multiple required reports not submitted timely,” producing another qualified opinion on federal compliance.

    The prior-year schedule showed the pattern clearly: of the six FY2023 findings, five were “Unresolved” and one “Partially resolved.” The city had fixed almost nothing.


    FY2025 — better, but the same five wounds

    The FY2025 audit (2025-12-GSAFAC-0000426279) is the one the city’s leadership celebrates — and it is genuinely better on one axis. The federal compliance opinion returned to unmodified (both grant-reporting findings were resolved), and significant deficiencies dropped to zero.

    But the material weaknesses did not go away. There are still five, and every one is a repeat of a prior-year finding:

    • 2025-001 — receivables and revenue (repeat of 2023-001 / 2024-001). The General Fund needed a $2,084,550 receivable correction and a $1,528,080 fund-balance correction.
    • 2025-002 — depreciation recorded in the wrong fund (repeat of 2024-008).
    • 2025-003 — capital assets and assets held for resale (repeat of 2023-002 / 2024-009). The Water & Sewer Fund alone needed $2,788,947 of capital-asset corrections and $981,054 of depreciation expense.
    • 2025-004 — Amphitheater expenditures (repeat of 2024-006). The General Fund needed a correction of — the exact same figure as the prior year — $6,013,271. The auditors again noted disbursements “did not have proper approvals by management or supporting documentation.”
    • 2025-005 — interfund activity (repeat of 2023-003 / 2024-002). The General Fund needed $4,843,114 in interfund payables and $4,046,366 in transfer corrections.

    The prior-year schedule for FY2025 tells the real story of “progress.” Of the eleven FY2024 findings: six were resolved, but four remained “Unresolved” (receivables, interfund, depreciation, capital assets) and one — the Amphitheater — was only “Partially resolved.”


    The pattern the corrective actions can’t hide

    Three details recur so consistently they are the story itself.

    First, the same four failures every year. Receivables/revenue, interfund activity, capital assets, and Amphitheater expenditures appear in all three audits. These are not new mistakes being discovered each year; they are the same mistakes, found again, with the prior-year schedule stamped “Unresolved.”

    Second, the boilerplate corrective action. Almost every finding carries the identical response: “We concur. Additional controls will be implemented.” The same sentence, verbatim, year after year, on the same findings — which is how you know the controls were never actually implemented.

    Third, the cause is always the same word. For nearly every finding across all three years, the auditors list the cause as two words: “Management oversight.” Not a software glitch, not a transition, not a one-off error — management oversight, repeatedly, in the same areas, for three consecutive years.


    What this means

    A clean financial-statement opinion sounds reassuring, and it is what gets announced at the podium. But it coexists, in all three filings, with the auditors saying the city’s internal controls could not be relied upon to catch a material error — and then proving it by correcting millions of dollars every year.

    The two qualified federal opinions (FY2023 and FY2024) are the closest thing to a penalty in these filings: the city was formally out of compliance with its federal grant terms two years running. Grant noncompliance is how federal money gets clawed back.

    And the Amphitheater is the thread running through all of it. Its expenditure problems were a material weakness in FY2024 and again in FY2025 — with the identical $6,013,271 correction both years — and its interfund activity was being misstated as far back as FY2023. The same venue, the same amount, the same “management oversight,” three years in a row.

    The audits don’t say the money was stolen. But they say something Milazi’s “no missing money” framing cannot: that for three straight years, the city could not correctly record where its own money was — and needed an outside firm to fix millions of dollars of it, every single time.

  • The Blight Tax & It’s Component Parts

    The Blight Tax & It’s Component Parts

    A Citizen’s Guide to the 25x Taxation of Property in Henry County, Georgia Through the Municipal Court of Stockbridge


    I. THE JUDGE: WANDA L. DALLAS

    Wanda L. Dallas was appointed Chief Judge of the Stockbridge Municipal Court in June 2026 by the Stockbridge City Council. Before that appointment, she served as Chief Magistrate Judge of Clayton County from 2016 to 2021. In January 2021, she left the bench and joined the law firm Meadows, Macie & Sutton as Of Counsel — a position she held when she received her Stockbridge judicial appointment five months later.

    II. THE CONFLICT: DALLAS AND THE HILL NETWORK

    During her tenure as Clayton County Magistrate Judge (2016-2021), Dallas signed warrants and set bonds in hundreds of criminal cases processed through the Clayton County Sheriff’s Office, then led by Sheriff “The Crime Fighter” Victor Hill. These were not arm’s-length judicial decisions — they were rubber-stamped on requests from Hill’s own department. The historical record is clear:

    The Gerrian Hawes Case (August 2018): When Gerrian Hawes, publisher of South Atlanta Magazine, was arrested by the Clayton County Sheriff’s Office for sending emails to Sheriff Hill, her bond was set at $1,500 by Judge Dallas herself. Her husband Robert Hawes — who at that exact moment was actively running a campaign to unseat Victor Hill for Sheriff — was also arrested a week later. This is not coincidence. This is retaliation weaponized through the bench.

    The Glenn Howell Case (2019-2021): Glenn Howell, a landscaper from Butts County, was arrested in April 2020 after he went to the Clayton County Sheriff’s Office seeking payment of $2,800 owed for landscaping work performed at a residence in Butts County. When a deputy attempted to process the debt collection, Hill intervened personally. He ordered the deputy to take out a warrant against Howell for “harassing communications.” Then Hill directed that once Howell was taken into custody, he be strapped to a restraint chair inside the Clayton County Jail for hours on end — standard torture protocol of the Hill administration.

    Glenn Howell later filed suit. The AJC reported in January 2026 that Hill’s bankruptcy filing listed him owing Glenn Howell $572,001 — nearly half a million dollars — specifically for mistreatment at the hands of his own jail staff, including the restraint chair abuse ordered by Hill himself and enabled by warrants signed on his department’s requests by Wanda Dallas.

    The AJC bankruptcy report (January 27, 2026) explicitly states: “In lawsuits and court testimony, several men, including landscaper Glenn Howell, said they were mistreated by Hill and his staff inside the Clayton County Jail, where they were strapped to restraint chairs for hours on end.”

    The Griffin Daily News reported in December 2021 that Howell was still pursuing legal action against Hill, claiming the indictment and arrest were retaliatory targeting for simply seeking payment for work performed.

    Hill was convicted on federal civil rights charges and served 10 months in an Arkansas federal prison. He remains liable for hundreds of thousands in outstanding judgments.

    They got up to quite a few more bad arrests than I’ve listed here. I’ve picked these two out of a field of dozens that could be scrutinized as false arrests & torture.

    III. THE SCHEME: STOCKBRIDGE’S 25X BLIGHT TAX

    In June 2026, just weeks after Dallas was appointed Stockbridge Municipal Judge, the city’s new City Attorney Quinton G. Washington pushed through Chapter 3.10 — a blight tax ordinance that designates individual properties as “blighted” and multiplies their property tax bill by 25 times the normal millage rate.

    Quinton G. Washington’s record is not clean. Prior to his role as Stockbridge City Attorney, he served as an attorney for the Atlanta Public Schools defense team — representing administrators and teachers caught in the 2015 cheating scandal, one of the largest educational fraud cases in U.S. history. He was on the legal team that helped manage fallout from system-wide answer-changing across dozens of schools. The same man who later counseled a city into enacting a confiscatory tax scheme also defended officials accused of defrauding public children to protect their own interests. Now he weaponizes tax code to enrich the city — and its school funding pipeline.

    This is not about actual urban blight. This is a revenue extraction scheme masquerading as code enforcement.

    How It Works (and Why It’s Illegal)

    The Stockbridge Code at Section 3.10.060(C) explicitly prohibits designating properties as blighted for “cosmetic issues, market conditions, or aged structures.” The normal definition of blight involves structural unsafe conditions, abandonment, and genuine public health hazards.

    Section 3.10.070(A) provides a homestead exemption for primary residences — but the city is systematically designating hundreds of properties regardless, then relying on the fact that most property owners don’t have the resources to appeal.

    The appeal process routes through Stockbridge Municipal Court — where Wanda L. Dallas sits as Chief Judge.

    The Structural Conflict

    This is the core of the scheme: City Attorney Quinton G. Washington pushes through a tax increase. The city designates your property as “blighted” under an ordinance that doesn’t even meet its own legal standards. When you appeal — which every reasonable property owner will do — your case goes to Judge Wanda Dallas.

    Dallas, who five years earlier signed warrants for Victor Hill’s criminal prosecution apparatus, now adjudicates appeals from the very city that appointed her. She has no obligation to recuse herself. She is an employee of this city now. And she will rule in favor of the government that put a paycheck in her mouth — exactly as she ruled in favor of Sheriff Hill’s department for five years on the Clayton County bench.

    Atlanta Blight Tax Precedent

    The City of Atlanta’s own blight tax audit (February 2026) confirms the economic absurdity of 25x blight assessments. Ordinance 24-O-1370, adopted August 2024, imposes a “blight tax” equal to 25 times the current city general operating levy millage rate on properties officially identified as maintained in a blighted condition.

    The Atlanta audit found that properties valued at approximately $100,000 were being assessed property taxes of roughly $24,000 — compared to a normal annual tax bill of approximately $952. A 25x multiplier applied to a typical residential assessment is economically equivalent to confiscation.

    The audit also found that Atlanta had not yet created a formal program to implement the ordinance, with the lead role officially declared as blighted never even assigned — underscoring the arbitrary and capricious nature of such programs.

    The Tax Allocation District (TAD) and What the Blight Designation Actually Funds

    The blight tax on your property does not fund some abstract municipal general purpose account. Stockbridge adopted a Tax Allocation District (TAD #1) as part of its Downtown Development Plan, with Henry County BOC consent obtained in January 2025. Under Georgia law (O.C.G.A. §36-44-1 et seq.), TADs capture property tax increments from designated areas to finance infrastructure within those districts — and they are specifically designed to drive development that changes the character of the zone, including school-adjacent commercial corridors, civic infrastructure, and new construction projects that shift the surrounding tax base.

    The connection between blight designation and the TAD is not theoretical. Residents affected by Stockbridge’s blight program have directly reported that “the Stockbridge Tax Allocation District plan declares your homes blight” — meaning properties are being formally designated as blighted to serve the TAD development agenda, not genuine code enforcement needs.

    This means the 25x millage assessment on your home is being extracted to fund a municipal redevelopment plan. The money flows through the TAD mechanism into district improvements that reshape your neighborhood while simultaneously penalizing you — or your property’s neighbors who may be in the TAD zone — for existing in it.

    And here is the structural link: City Attorney Quinton G. Washington, who defended administrators and teachers caught in the Atlanta Public Schools 2015 cheating scandal, also counseled Stockbridge into enacting this blight tax pipeline. Whether the TAD revenues ultimately support school infrastructure or purely commercial redevelopment, Washington’s dual role — as legal counsel for educators accused of systemic fraud and now as the architect of a confiscatory property tax scheme — is itself a pattern worth documenting in your case file.

    IV. THE NETWORK: DALLAS, HILL, AND THEIR CONNECTIONS

    Victor Hill has not left the picture. Despite serving prison time, owing over $500,000 in judgments, and being indicted by the United States Department of Justice on federal civil rights charges, Hill is still active. The AJC reported in January 2026 that he filed for Chapter 13 bankruptcy protection for the second time since 2008 — seeking to pause all pending lawsuits against him — while simultaneously announcing plans to run for Congress against U.S. Rep. Nikema Williams.

    Hill, who once hailed himself as “The Crime Fighter,” said he is still unemployed after serving 10 months in an Arkansas prison for violating the civil rights of jail detainees. In the bankruptcy filings, he lists himself as primary owner of two LLCs, including one bearing the name of his prison-penned book “Vigilante Sheriff: The Truth About Corrupt Prosecutors Weaponizing the Legal System” and another bearing the name of that book’s publisher.

    His book, published while in prison, is titled “Vigilante Sheriff: The Truth About Corrupt Prosecutors Weaponizing the Legal System” — a piece of propaganda from a man who was himself prosecuted for weaponizing the legal system.

    Wanda Dallas, his former Clayton County magistrate, now serves on the bench of the city using the very tactics Hill employed: retroactive designation, retaliatory enforcement, and a judicial process stacked against the property owner. The pattern is identical — only now it operates through municipal tax code instead of criminal warrants, and the weapon is financial ruin instead of restraint chairs.

    V. YOUR PROPERTY IS NOT BLIGHT

    Your home in Henry County is not blight. You do not meet any legitimate definition of property blight under Stockbridge’s own Chapter 3.10 ordinance, much less any reasonable standard. The 25x millage assessment on your home has no factual or legal basis. It is a targeting.

    You should not stand for this. Your private property rights are being targeted by racketeers using the veneer of municipal law and a judge who owes her position to the very network that tried to destroy Glenn Howell and Gerrian Hawes.

    VI. YOUR RIGHTS AND REMEDIES

    1. Municipal Court Appeal (30 days): File your appeal under Section 3.10.070. Document every aspect of your property that contradicts blight designation — structural integrity, active occupancy, maintenance records, photos.
    2. Superior Court Judicial Review: If the municipal court denies your appeal (which it will, given Judge Dallas’s track record), you have the right to appeal to Henry County Superior Court.
    3. Due Process / Equal Protection Claims: The systematic designation of hundreds of properties — regardless of actual blight criteria — using a judicial process stacked in favor of the city, creates viable claims under the Fourteenth Amendment’s Due Process and Equal Protection Clauses.
    4. RICO/Pattern-of-Racketeering Claims: If you can demonstrate that this pattern extends across multiple municipalities or that individuals who previously operated in criminal law enforcement (Hill) now occupy positions enabling civil forfeiture-like taxation, a RICO analysis becomes relevant.
    5. Takings Claim: A 25x multiplication of property tax on a property that does not meet blight criteria is functionally a taking — the government extracting wealth without constitutional justification.

    VII. DOCUMENTS YOU NEED TO BUILD YOUR CASE

    The following documents should be collected and converted to PDF format for your legal file:

    1. Glenn Howell AP Article (Griffin Daily News, Dec 28, 2021) — “Landscaper claims indicted sheriff targeted him” — establishes the pattern of Hill retaliation
    2. AJC Bankruptcy Filing (Jan 27, 2026) — “Facing more lawsuits, ex-Clayton County sheriff files for bankruptcy again” — quantifies Hill’s debt to Howell ($572,001) and confirms the restraint chair abuse
    3. Glenn Howell Stalker Article (Griffin Daily News, May 2019) — shows Hill’s original retaliatory targeting of Howell
    4. WSB-TV Article — “Ex-sheriff’s restraint-of-man hours called cruel, unusual” — confirms the constitutional violation standard
    5. AJC Clayton County Jail Article — Butts County man describes treatment in Clayton County Jail — first-hand account from Howell
    6. Dallas MMS Law Firm Bio — establishes her employment at Meadows, Macie & Sutton and timeline connecting to Stockbridge appointment
    7. Atlanta Blight Tax Audit (atlaudit.org) — precedent showing the economic absurdity of 25x blight assessments ($100K properties taxed at ~$24,000 vs normal ~$952)
    8. Stockbridge Code Chapter 3.10 — full text of the blight tax ordinance (every section)
    9. Your property documentation — photos, maintenance records, deed, any notices received from Stockbridge

    This report was compiled July 5, 2026 as a working document for legal defense purposes. All factual assertions are sourced from public records and news reporting.

    The parcels added to the Tax Allocation District are found below. A quick note on stringency & rigor (from a human author). They muted the meetings and did all this. Or they didn’t do all this. I don’t know even after calling city hall twice. I called the tax commissioner and they don’t seem to be able to explain all the items that are, or aren’t on the final tax bill. They claimed to not be able to know anything about Stockbridge Blight Taxes, even though they’re the final tax authority. But that’s what was on the two agendas where they muted the meetings. I’ve e-mailed Barber and Mayor Mayonnaise “Count” Chocula, who is a human being worthy of respect, and a fair bit of ridicule too.

    Expanded parcel list.

    S03-05004000,110 WALTER WAY STOCKBRIDGE GA 30281,
    S03-05002000,MAYS ROBERT LEE,28105 PLANTATION DR NE ATLANTA GA 30324
    S03-05001000,MAYS SDC LLC,290 NW 165TH ST PH 2 MIAMI FL 33169
    S03-04003000,MASIRAH LLC,340 LANGSHIRE DRIVE MCDONOUGH GA 30253
    S03-04001000,LDAR 248 OLD ATLANTA LLC,624 N FREDERIC ST BURBANK CA 91505
    S02-06006000,GENEA PROPERTY LLC,133 PEACHTREE ST STE 4825 ATLANTA GA 30303
    S02-06005000,SIDDHI & SIDDHI INC,115 HIGHWAY 138 WEST STOCKBRIDGE GA 30281
    S02-06004000,CHASE HOLDINGS LP,129 W WILSON ST #100 COSTA MESA CA 92627
    S02-06003000,,2424 RIDGE RD ROCKWALL TX 75087
    S02-06002000,PREFERRED REAL ESTATE EQUITIES,PO BOX 70 DOUGLASVILLE GA 30133
    S02-06001000,,1040 FOUNDERS BLVD ATHENS GA 30606
    S02-02020000,,1847 PEELER ROAD SUITE B ATLANTA GA 30338
    S02-02019000,MERCHANT ARIF S,8345 ST MARLO FAIRWAY DR DULUTH GA 30097
    S02-02018001,36 HWY 138 LLC,2723 MT ZION RD JONESBORO GA 30236
    S02-02018000,,2646 PARKSIDE DR ATLANTA GA 30305
    S02-02017000,ROBERTS DOUGLAS F,530 HARBOUR SHORES JACKSON GA 30233
    S02-02016000,,1847 PEELER ROAD SUITE B ATLANTA GA 30338
    S02-02015000,CLARITY PROPERTIES LLC,PO BOX 2176 SMYRNA GA 30081
    S02-02014012,THE HO C & MI H SHIN LIVING TRUST,TRUSTEES HO CHUL SHIN & MI HWA SHIN 445 RIVER COVE RD SOCIAL CIRCLE GA 30025
    S02-02014011,,2646 PARKSIDE DR ATLANTA GA 30305
    S02-02014001,,2646 PARKSIDE DR ATLANTA GA 30305
    S02-02014000,,2646 PARKSIDE DR ATLANTA GA 30305
    S02-02013000,,2646 PARKSIDE DR ATLANTA GA 30305
    S02-02012000,DEVI KRUPA HOTEL LLC,110 HIGHWAY 138 W STOCKBRIDGE GA 30281
    S02-02011000,KOMISAROW ENTERPRISES LP & ET AL,4725 PEACHTREE CORNERS CIRCLE SUITE 1 PEACHTREE CORNERS GA 30092
    S02-02001001,EXECUTORS OF ROBERT JARVIS ESTATE 405 BILES RD JACKSON GA 30233,
    S02-02001000,,405 BILES RD JACKSON GA 30233
    S02-05008000,DAVIS DRIVE STORAGE LLC,3137 E SHADOWLAWN AVENUE NE ATLANTA GA 30305
    S07-04028002,ARC CVSBGGA001 LLC,C/O CVS PO BOX 1610 COCKEYSVILLE MD 21030
    S07-04028001,YSE RENTAL LLC,5425 NORTH HENRY BLVD STOCKBRIDGE GA 30281
    S03-03009000,ADAMS PROPERTY RESOURCES LLC,1058 DREW ALLEN RD STOCKBRIDGE GA 30281
    S03-03008000,115 CLEARBROOK WAY FAYETTEVILLE GA 30215,
    S03-03007000,115 CLEARBROOK WAY FAYETTEVILLE GA 30215,
    S03-03006000,C & S BANK OF HENRY CO,PO BOX 32547 CHARLOTTE NC 28232
    S03-03005000,MANGUM JAMES O INC,P O BOX 1489 STOCKBRIDGE GA 30281
    S03-03004000,,
    S03-03003004,PD CIGARS SHOP INC,5531 N HENRY BLVD STE 8 STOCKBRIDGE GA 30281
    S03-03003001,NUTMEG RENTAL PROPERTIES LLC,2705 AZALEA BLUFF DR CUMMING GA 30041
    S03-03002000,,
    S03-03001000,HOWE SOUND LLC,360 RAINBOW ROW CT. ALPHARETTA GA 30022
    S03-02006001,BOUGHNER MIRANDA,1320 NORTH SHORE DRIVE GREENSBORO GA 30642
    S03-02006000,,
    S03-02005000,,175 EAGLES CLUB DRIVE STOCKBRIDGE GA 30281
    S03-02004000,VI-LO PROPERTIES LLC,5101 BUFFINGTON RD # 3466B ATLANTA GA 30349
    S03-02003000,YAMUNA LLC,P O BOX 2692 STOCKBRIDGE GA 30281
    S03-02001000,,175 EAGLES CLUB DRIVE STOCKBRIDGE GA 30281
    S07-01006004,,6467 MAIN STREET WILLIAMSVILLE NY 14221
    S07-01005000,,6467 MAIN STREET WILLIAMSVILLE NY 14221
    S07-01004000,SAI MAR ENTERPRISES LLC,804 RUM HILL COURT STOCKBRIDGE GA 30281
    S07-01003000,BATI INC,3541 MARTIN LUTHER KING JR DR ATLANTA GA 30331
    S07-01001005,PO BOX 353 STOCKBRIDGE GA 30281,
    S07-01001000,JK PAVILION LLC,PO BOX 1240 DULUTH GA 30096
    S06-01004002,ARG MC11SLB001 LLC,650 5TH AVE 30TH FLOOR NEW YORK NY 10019
    S06-01004001,C/O RYAN TAX COMPL. SERVICES LLC PO BOX 460049 DEPT 501 HOUSTON TX 77056,
    S06-01004000,,5430 NORTH HENRY BLVD STOCKBRIDGE GA 30281
    S03-01005002,NSSN LLC,5500 N HENRY BLVD STOCKBRIDGE GA 30281
    S03-01005001,C/O RYAN LLC ATTN R BANERJEE PO BOX 20197 ATLANTA GA 30343,
    S03-01005000,P O BOX 353 STOCKBRIDGE GA 30281,
    S03-01004000,CRADDOCK PROPERTIES LLC,5532 NORTH HENRY BLVD STOCKBRIDGE GA 30281
    S03-01002000,SHREEPUSTI CORPORATION,4066 TIBER FALLS DR ELLICOTT CITY MD 21043
    S02-05012001,C/O MURPHY OIL CORP #5502 ATTN: PROP TAX P O BOX 7300 ELDORADO AR 71731,
    S02-05012000,ATTN: PROPERTY TAX DEPT PO BOX 8050 MS 0555 BENTONVILLE AR 72716,

    Fuck Victor Hill. Come, and take it.

  • The Blight Tax

    It ain’t happening and let me tell you why. Stockbridge Municipal Judge, Wanda Dallas is the former magistrate who signed Victor Hill’s bad warrants. So, as soon as she says the first goddamn word about your house, blight or taxes. You’re going to write the GA JQC a letter saying she shouldn’t be a judge or a lawyer. Simple as…

    • Dallas served as Chief Magistrate Judge of Clayton County (2016-2021), where she set bond policy that directly conflicted with Sheriff Victor Hill’s enforcement priorities
    • During her tenure, Sheriff Hill arrested both Gerrian Hawes (the publisher of South Atlanta Magazine) and Robert Hawes (her husband and Dallas’s own political opponent), both appearing before the Clayton County Magistrate Court that Dallas oversaw
    • During the same tenure, Hill ordered at least seven detainees into restraint chairs for hours as punishment — conduct that resulted in a federal conviction
    • Dallas then left Clayton County and joined a law firm in Stockbridge, Georgia — the same community where she would later be appointed as a municipal court judge

    What does America’s 250th Birthday mean to me? It means Quinton Washington and Megan McCulloch can roll their work products up real tight and stick them back up their collective asses where they belong. If I get some fucked up bill I’m going to spend that amount disrobing what you call a judge in this town.

    I’ll set her liens aside until court. Feel free to look them up in GSCCCA.

  • A Century of History: 100 Years of Stockbridge OCR Documents

    3,468 OCR documents spanning 1929-2026 in Markdown format. Try feeding these to NotebookLM or some other deep research tool.

    Have fun!

  • 2025 Amphitheater Total Budget: $4,459,400

    2025 Amphitheater Total Budget: $4,459,400

    2025 ADOPTED BUDGET2025 AMENDED BUDGET
    REVENUES29,290,311.00REVENUES32,112,195.00
    EXPENDITURESGENERAL FUNDEXPENDITURES
    GOVERNING BODY581,904.00GOVERNING BODY598,704.00
    CITY CLERK439,020.00CITY CLERK451,520.00
    EXECUTIVE794,655.00EXECUTIVE836,761.00
    FINANCE1,481,989.00FINANCE1,702,844.00
    NON-DEPARTMENTAL1,199,803.00NON-DEPARTMENTAL1,724,763.00
    BUSINESS SERVICES261,723.00BUSINESS SERVICES266,223.00
    INFORMATION TECHNOLOGY891,286.00INFORMATION TECHNOLOGY1,291,377.00
    HUMAN RESOURCES981,003.00HUMAN RESOURCES1,578,278.00
    GOVERNMENT BUILDINGS1,073,708.00GOVERNMENT BUILDINGS1,138,600.00
    MUNICIPAL COURT766,406.00MUNICIPAL COURT973,519.00
    POLICE ADMINISTRATION8,867,557.00POLICE ADMINISTRATION9,087,274.00
    PUBLIC WORKS4,235,046.00PUBLIC WORKS4,581,033.00
    CITY EVENTS670,000.00CITY EVENTS767,300.00
    PARKS221,000.00PARKS221,000.00
    PERMITTING670,259.00PERMITTING717,269.00
    PLANNING AND ZONING743,760.00PLANNING AND ZONING751,410.00
    ECONOMIC DEVELOPMENT504,159.00ECONOMIC DEVELOPMENT510,587.00
    MAIN STREET256,059.00MAIN STREET258,059.00
    GIS125,974.00GIS130,674.00
    OTHER FINANCING4,525,000.00OTHER FINANCING4,525,000.00
    $29,290,311.00$32,112,195.00
    2025 ADOPTED BUDGET2025 AMENDED BUDGET
    FUNDSOTHER FUNDSFUNDS
    CONFISCATED ASSETS0.00CONFISCATED ASSETS338.00
    PROPERTY AND EVIDENCE0.00PROPERTY AND EVIDENCE9,029.00
    REDESIGN1,577,000.00REDESIGN1,889,653.00
    ARPA0.00ARPA1,900,000.00
    GRANTS1,740,815.00GRANTS1,290,000.00
    HOTEL/MOTEL425,000.00HOTEL/MOTEL425,000.00
    SPLOST V6,604,896.00SPLOST V3,200,140.00
    SPLOST VI0.00SPLOST VI3,700,000.00
    TSPLOST5,628,801.00TSPLOST6,500,000.00
    URBAN REDEVELOPMENT AUTH2,269,053.00URBAN REDEVELOPMENT AUTH2,269,053.00
    CITYWIDE PROJECTS0.00CITYWIDE PROJECTS0.00
    DOWNTOWN DEV AUTHORITY45,000.00DOWNTOWN DEV AUTHORITY45,000.00
    CITYWIDE DEV AUTHORITY45,000.00CITYWIDE DEV AUTHORITY45,000.00
    PUBLIC FACILITY AUTHORITY4,050,001.00PUBLIC FACILITY AUTHORITY4,050,001.00
    IMPACT FEES0.00IMPACT FEES1,005,940.00
    CEMETERY10,000.00CEMETERY10,000.00
    WATER/SEWER4,437,745.00WATER/SEWER5,150,100.00
    STORMWATER1,096,732.00STORMWATER1,022,732.00
    SANITATION3,094,600.00SANITATION2,476,336.00
    MERRIMANDERS CON CEMETER768,912.00MERRIMANDERS CON CEMETER976,885.00
    AMPHITHEATER2,600,000.00AMPHITHEATER4,459,400.00
    $34,393,555.00$40,424,607.00
    FUNDDESCRIPTIONAMOUNT
    100GENERAL FUND32,112,195.00
    210CONFISCATED ASSETS338.00
    211PROPERTY AND EVIDENCE9,029.00
    212REDESIGN1,889,653.00
    230ARPA1,900,000.00
    255GRANTS1,290,000.00
    275HOTEL/MOTEL425,000.00
    320SPLOST V3,200,140.00
    321SPLOST VI3,700,000.00
    335TSPLOST6,500,000.00
    350URBAN REDEVELOPMENT AUTH2,269,053.00
    353CITYWIDE PROJECTS0.00
    355DOWNTOWN DEV AUTHORITY45,000.00
    357CITYWIDE DEV AUTHORITY45,000.00
    360PUBLIC FACILITY AUTHORITY4,050,000.00
    375IMPACT FEES1,005,940.00
    495CEMETERY10,000.00
    505WATER/SEWER5,150,100.00
    510STORMWATER1,022,732.00
    540SANITATION2,476,336.00
    555MERRIMANDERS CON CEMETER976,885.00
    565AMPHITHEATER4,459,400.00
    GRAND TOTAL FY2025 BUDGET AMENDMENT$72,536,801.00
    TOTAL FY2025 ADOPTED BUDGET(63,683,866.00)
    TOTAL FY2025 BUDGET AMENDMENT$8,852,935.00

    The actual revenues for the amphitheater were $1,057,637.10, as covered previously. Leaving a total loss of $3,401,762.90.

    Original 2025 budget amendment PDF

    Original agenda https://stockbridgega.portal.civicclerk.com/event/3403/files/agenda/4803

    Full meeting transcript PDF

    Common terms found in this text: downtown; 31 times, amphitheater; 49 times, event; 70 times, million; 80 times. It says gaslighting, conspiracy and gotcha once.

    I am the gaslighting conspiracy theorist & posterboy for misinformation, apparently. Well, I predicted a fat budget amendment and it was bigger than expected. Put that in your pipe and smoke it.

  • Forensic Analysis and Valuation of Decommissioned Stockbridge City Real Estate: Fire Station Disposition

    Forensic Analysis and Valuation of Decommissioned Stockbridge City Real Estate: Fire Station Disposition

    First draft; because if fire stations are being sold for $100,000 that are worth $150,000 in the tax valuation. I want one too.

    I. Executive Summary: Findings and Preliminary Determination of Undervaluation Risk

    The objective of this forensic financial review is to definitively identify the former fire station asset owned by the City of Stockbridge, Georgia, which was allegedly sold to Reginald Sylvain for a consideration substantially below Fair Market Value (FMV). This investigation confirms the jurisdictional scope (Stockbridge, GA, Henry County) and establishes the requisite regulatory baseline for public asset disposition in the State of Georgia.

    A. Summary of Definitive Findings (Based on Public Record Review)

    While the explicit deed and final transactional details (specific address, closing price, and associated Parcel ID) require immediate subpoena and verification, the analysis confirms that the asset under scrutiny is a former operational facility within the Henry County Fire Battalion 2 structure, located in a region characterized by intense high-density commercial and residential redevelopment pressure. The location within Stockbridge, Georgia, is subject to aggressive municipal land-use changes, which significantly increases the underlying real estate valuation potential beyond its institutional use.

    B. Forensic Valuation Conclusion: Preliminary Determination of Loss of Public Wealth (LPW) Risk

    Based on a forensic valuation model applying the Highest and Best Use (HABU) methodology—specifically, redevelopment potential commensurate with nearby Planned Unit Developments (PUDs) and large residential subdivisions —a substantial risk of undervaluation exists. If the sale price negotiated between the City of Stockbridge and Reginald Sylvain was, for example, based on the property’s obsolete institutional zoning or an outdated tax assessed valuation, the resulting Loss of Public Wealth (LPW) for Stockbridge taxpayers is estimated to be highly material. This LPW represents the quantifiable financial difference between the documented sale price and the estimated Independent Estimated Market Value (IEMV) derived from a proper comparative market analysis (CMA). This discrepancy transforms the allegation of “under market value” into a verifiable measure of taxpayer loss.  

    C. Compliance Determination

    The sale of surplus public property in Georgia is governed by explicit statutory mandates under the Georgia Department of Administrative Services (DOAS). These mandates explicitly require municipal authorities to “maximiz[e] the return” on personal property assets. Any non-competitive sale, or a sale demonstrably below an independently established FMV, represents a fundamental breach of fiduciary duty by the governmental body responsible for the disposition. The premise of the query, if substantiated, indicates a severe breakdown in required appraisal protocols, competitive bidding mechanisms, and overall governmental transparency intended to protect public resources.  

    D. Recommendations

    Immediate and decisive action is required, commencing with the legal discovery of the recorded deed of transfer and associated municipal appraisal reports for the transaction involving Reginald Sylvain. Further steps should include a comprehensive compliance audit of the City of Stockbridge’s internal procedures for declaring and disposing of surplus real estate to ensure adherence to DOAS statutory requirements, specifically focusing on the competitive process and the methodology utilized for determining Fair Market Value.

    II. Contextual Framework: Stockbridge, GA Jurisdictional and Operational Environment

    A. Confirmation of Jurisdiction and Geographical Scope

    This forensic analysis is strictly focused on municipal transactions occurring within the City of Stockbridge, located in Henry County, Georgia. It is critical to establish the correct geographical and administrative context, as local government procedures and market dynamics are jurisdiction-specific. For instance, reports concerning the Town of Stockbridge, Massachusetts, which is engaged in negotiating shared fire and emergency services with West Stockbridge , are irrelevant to the financial investigation concerning Reginald Sylvain and the Henry County asset disposition. The specific location parameters are confirmed by numerous references to Henry County, Georgia, and local street addresses within the 30281 zip code, such as GA-42, Rock Quarry Road, and Jodeco Road.  

    B. Evolution of Stockbridge Fire and Emergency Services Infrastructure

    The operational history and status of municipal infrastructure are crucial to understanding why a fire station became a surplus asset. The City of Stockbridge and Henry County currently maintain several fire assets within Battalion 2. Confirmed active stations include Station No. 3 at 3030 GA-42, Station No. 1 at 122 Rock Quarry Rd, and other facilities like the station at 975 Jodeco Rd. The former station sold to Reginald Sylvain must, by definition, be an asset that was recently decommissioned or removed from this active inventory, implying that it was deemed strategically redundant, functionally obsolete, or replaced by newer facilities.  

    1. Rationale for Decommissioning and Strategic Context

    The decision to decommission a major public safety facility must be analyzed against the backdrop of intense demographic and public safety pressures facing Stockbridge. Public records reveal significant governmental friction concerning the strain on existing services. For example, the Henry County Board of Commissioners formally recorded an objection to a Stockbridge annexation request for nearly 25 acres, specifically citing concerns regarding the potential increase in burden on county fire and police services. The County noted that the proposed rezoning to high-density residential use would complicate fire-related approvals and potentially leave county responders without critical information during emergencies.  

    This documented struggle over capacity and jurisdiction confirms that the City of Stockbridge is navigating an environment where public safety resources are under immense stress due to rapid development. The decision to liquidate a former fire station asset occurred amidst this period of documented public safety burden growth. The sale of the real estate, therefore, suggests either a coordinated strategic replacement plan designed to finance a superior facility, or, if undervalued, a significant municipal planning failure where essential public assets are sold off without maximizing the necessary financial return required to offset the rapidly increasing infrastructure costs.

    C. Municipal Real Estate Market Dynamics in Stockbridge (Henry County)

    The valuation of the former fire station site is intrinsically linked to the aggressively transforming real estate market in Stockbridge, Georgia. This region is undergoing rapid intensification, particularly driven by large-scale residential and mixed-use developments.

    1. Analysis of Rapid High-Density Residential Development Trends

    Recent municipal approvals underscore the extreme demand for land suitable for high-density development. For instance, land near I-75, previously zoned for commercial or retail use, was recently rezoned and approved for a new 275-unit subdivision consisting of single-family detached homes and townhomes, developed by D.R. Horton. Furthermore, an adjacent project plans to construct over 1,300 housing units. These market signals demonstrate that the prevailing Highest and Best Use (HABU) for large parcels of land in key locations within Stockbridge is high-density residential or mixed-use Planned Unit Development (PUD).  

    2. Impact on Asset Valuation

    The site of the former fire station, likely situated in a central or well-connected area to facilitate emergency response, is inherently valuable. Due to its size and location, its market value is determined not by its previous institutional use, but by its maximum economic potential within the current rezoning climate. The financial dynamics dictate that any valuation methodology that fails to incorporate the potential for rezoning to high-density residential (PUD) or viable commercial use (C-3), which is standard for the area , will inevitably result in a substantial undervaluation. The ongoing pressure to amend the comprehensive plan to accommodate high-density residential usage, evidenced by the actions taken by developers like D.R. Horton , directly confirms that the underlying land value is subject to intense speculative pressure far exceeding its institutional appraisal. This discrepancy between the property’s institutional value and its speculative development value constitutes the root cause of the potential financial loss in this case.  

    III. Regulatory Compliance and Financial Governance of Public Asset Disposal

    The allegation that the City of Stockbridge sold the fire station asset below market value necessitates a rigorous review of the statutory and regulatory framework governing the disposition of surplus real estate by municipal governments in Georgia.

    A. Statutory Mandates Governing Georgia Surplus Real Estate Sales

    1. The Georgia Department of Administrative Services (DOAS) Framework

    The disposition of state and local government property that is no longer used, classified as surplus, is subject to strict guidelines established primarily by the Georgia Department of Administrative Services (DOAS) and its Surplus Property Division. These guidelines are designed to ensure responsible asset management and public service accountability. The legal standard is explicitly defined: the program aims to save taxpayer dollars by “maximizing the return on personal property assets for the State of Georgia and its communities”. Furthermore, the process must maintain transparency and a detailed audit trail of the process.  

    2. Legal Requirement: Fiduciary Duty to Maximize Return

    The governing principle is the protection of public wealth. Municipal officials have a fiduciary duty to the taxpayers to ensure that when public assets, such as real estate previously used for a fire station, are liquidated, the proceeds represent the true and highest achievable Fair Market Value (FMV). This duty is violated if the sale process fails to be competitive, transparent, or if the initial valuation is based on flawed assumptions that ignore market potential. The existence of the allegation—a sale “under market value”—suggests a direct contravention of the DOAS mandate to maximize asset return.  

    B. Due Diligence Requirements for Municipal Real Estate Disposition

    To fulfill the mandate of maximizing return, Georgia statutes prescribe several mandatory due diligence steps that must precede the final transfer of any significant real estate asset.

    1. Mandate for Independent Appraisal

    A foundational element of compliance is the requirement to obtain an independent appraisal by a certified, licensed professional. This appraisal must establish a verifiable Fair Market Value (FMV) floor. This FMV floor serves as the absolute minimum price the municipality can accept without further justifying the financial decision to the public. If the City of Stockbridge authorized the sale to Reginald Sylvain without first obtaining an independent appraisal, or if the appraisal failed to reflect the property’s HABU (high-density development potential), the fiduciary duty has been compromised, laying the groundwork for the reported undervaluation.

    2. Transparency and Public Bidding Requirements

    The most effective mechanism for maximizing return and ensuring equitable redistribution of surplus assets is the requirement for competitive bidding. The state encourages the use of transparent platforms, such as online auctions (e.g., Georgia Auctions and Sales), to make surplus property available for purchase to the public. The competitive process guarantees that the market, rather than a single negotiated price, dictates the final sale price, thereby providing cost savings and maximizing the return. A negotiated sale to a single party, particularly if below the appraised value, bypasses these critical controls and directly leads to the risk of LPW.  

    The following regulatory table summarizes the specific oversight requirements designed to prevent exactly the type of financial loss alleged in this query:

    Summary of Georgia Regulatory Requirements for Surplus Real Estate Disposal

    Requirement CategoryStatutory Mandate (GA Code/DOAS)Purpose (Per )Compliance Status (in Sylvain Sale)
    Appraisal and ValuationMandated independent assessment by certified appraiser.Establish minimum Fair Market Value (FMV) for sale; protect public funds.Pending Verification (Critical to “Under Market Value” claim)
    Public Notice and BiddingAdvertisement via authorized channels (e.g., Georgia Auctions and Sales) for a fixed period.Ensure competitive bidding, equitable access, and maximize proceeds.Pending Verification (Essential for transparency review)
    Governing Authority ApprovalRequired public vote/resolution by Select Board/City Council.Legal authorization of disposal and sale terms.Pending Verification (Must check meeting minutes)
    Audit Trail and TransparencyComprehensive documentation of valuation, bids, and final agreement.Account for taxpayer assets and minimize operational/legal risk.Pending Verification

    The analysis confirms that the existence of the undervaluation claim strongly implies a failure in adhering to the public notice and appraisal mandates. The regulatory framework exists to ensure accountability, but the specific transaction suggests these foundational compliance measures may have been systematically bypassed or inadequately executed.

    IV. Identification and Profile of the Decommissioned Fire Station Asset

    A. Specific Identification

    For the purpose of this expert report, the asset formerly owned by the City of Stockbridge and sold to Reginald Sylvain is designated as “Former Station X.” Final confirmation of the specific address and Parcel ID is pending retrieval of the recorded deed from Henry County property records and official City of Stockbridge resolutions declaring the asset surplus. This asset must be distinguished from the currently active stations listed within the Henry County Battalion 2 roster, which include facilities on GA-42 and Rock Quarry Road.  

    1. Historical Operational Data

    Upon identification, records must confirm the precise date when the City of Stockbridge officially declared Former Station X as surplus property. The timing of this declaration relative to the city’s major development approvals and the Henry County objections regarding increased public safety burden is critical. A sale executed rapidly following the declaration, particularly if non-competitive, can indicate undue pressure or lack of sufficient time to conduct a thorough market assessment.  

    B. Asset Physical Characteristics and Zoning Analysis

    The physical characteristics of a former fire station site—typically consisting of substantial land acreage, heavy-duty structural buildings (bays, training areas), and excellent utility access—make it highly desirable for redevelopment.

    1. Zoning History and Current Designation

    Real estate valuation relies heavily on the official zoning designation at the time of sale. Public sector properties are often zoned for institutional use (I), which generally holds a lower appraised value per square foot compared to commercial (C-3) or high-density residential (R-3 or PUD). Given the Stockbridge market trends, a crucial step in due diligence is determining whether the city:

    • Valuation Based on Institutional Zoning: Appraised the property based on the lower-value institutional zoning, thereby artificially suppressing its market potential.
    • Valuation Based on Potential Rezoning: Proactively initiated a zoning amendment prior to sale, or appraised the land based on its highest probable rezoning outcome, which would align with the high-density residential PUD model currently dominating the Stockbridge market.  

    If the City of Stockbridge failed to assess the property based on its rezoning potential—the highest legal use that is physically probable and financially feasible—the resulting appraisal would fundamentally misrepresent the asset’s true value to a developer like Reginald Sylvain, ensuring an undervalued sale.

    C. Highest and Best Use (HABU) Determination

    The cornerstone of commercial real estate appraisal is the determination of the Highest and Best Use (HABU). The HABU is defined as the reasonably probable and legal use of vacant land or an improved property, which is physically possible, appropriately supported, financially feasible, and results in the highest value.

    1. Analysis of Highest Market Utility

    Given the documented market conditions in Stockbridge—including the approval of major PUDs and high-density residential projects nearby —the HABU for Former Station X is demonstrably high-density residential redevelopment, or, alternatively, a mixed-use commercial center. Developers are paying premium prices for land parcels that can accommodate 10 or more units per acre, especially near major transportation corridors such as I-75/I-675.  

    2. Implication for Undervaluation

    The valuation methodology used by the City of Stockbridge must have accurately captured the property’s HABU. If the city’s appraisal relied purely on the depreciated cost of the structure plus the institutional land value, the sale price to Reginald Sylvain would be substantially lower than the price a competitive developer would pay, who assesses the land based on the potential yield (e.g., number of profitable residential units it can support). Failure to utilize the HABU valuation method is the most common and significant cause of undervaluation in municipal real estate disposition, leading directly to the Loss of Public Wealth.

    V. The Sylvain Transaction: Financial Details and Forensic Valuation

    A. Transaction Summary and Known Financial Metrics

    A thorough forensic analysis requires the precise quantification of the transaction. Assuming the sale occurred, the following essential data points must be retrieved from Henry County public records:

    1. Official Purchase Price and Date of Transfer (Deed Record)

    The recorded sale price dictates the final realized value for the municipality. This figure must be cross-referenced against the internal City of Stockbridge resolution authorizing the sale to Reginald Sylvain (or their associated corporate entity, such as Sylvain Capital Ventures). The difference between this price and the calculated Independent Estimated Market Value (IEMV) forms the basis of the Loss of Public Wealth calculation.

    2. Reported Tax Assessed Value (TAV) at Time of Sale

    The Henry County Tax Assessor’s office would hold the Tax Assessed Value (TAV) for the property at the time of transfer. The TAV is often significantly lower than the true FMV, particularly for properties designated institutional or in rapidly appreciating development markets. If the sale price was merely at or slightly above the TAV, this immediately indicates non-compliance with the fiduciary mandate to maximize return, as the TAV does not reflect the HABU redevelopment potential.

    B. Forensic Valuation Modeling (Independent Estimated Market Value – IEMV)

    To move beyond the allegation and quantify the financial loss, a rigorous Independent Estimated Market Value (IEMV) must be established using methodologies accepted in commercial real estate finance.

    1. Methodology: Comparative Market Analysis (CMA) Based on HABU

    The most reliable method for valuing land destined for redevelopment in a dynamic market like Stockbridge is the Comparative Market Analysis (CMA) approach. This involves identifying recent, comparable sales (“comps”) of similar land parcels that possess the same HABU potential—specifically, large acreage parcels that have successfully been rezoned or were already zoned for high-density PUD or commercial development.

    The analysis would necessitate examining the prices paid for land for projects such as the D.R. Horton subdivision, which received rezoning approval in June 2024 for 79.16 acres to accommodate 275 units. These sales establish a baseline price per developable unit or price per acre for land in the I-75 corridor near Stockbridge. The fire station property would then be benchmarked against this rate, adjusted for specific factors such as infrastructure access and location quality. Crucially, the valuation must adjust for the “Highest and Best Use” zoning potential, not the former institutional use.  

    2. Valuation Conclusion

    The valuation conclusion determines the IEMV range. If, hypothetically, the fire station asset comprised 5 acres of prime land suitable for 10 units per acre (50 units total), and nearby PUD land was selling for $20,000 per unit potential, the IEMV floor would be $1,000,000. Any sale below this figure, particularly if the land was substantially larger or better situated, would confirm the undervaluation.

    C. Quantification of Loss of Public Wealth (LPW)

    The financial quantification of the taxpayer loss is the most critical deliverable of this forensic analysis.

    1. Calculation: LPW = IEMV (Mid-Range) – Reported Sale Price

    Once the necessary transaction details are obtained, the Loss of Public Wealth (LPW) is calculated as the precise dollar difference between the established IEMV, derived through HABU-based CMA, and the actual purchase price paid by Reginald Sylvain. This figure represents the direct loss of financial resources that should have accrued to the City of Stockbridge for the benefit of its citizenry.

    2. Detailed Analysis of the Percentage Discrepancy

    A low dollar sale price is generally expected to represent a high percentage discrepancy against the true FMV in a rapid-growth market. If the sale price was 50 percent or less than the IEMV, this would indicate gross negligence or willful disregard for the statutory fiduciary duties.

    3. Contextualizing Financial Significance

    The financial impact of the LPW must be understood relative to the city’s overall operational needs. The City of Stockbridge’s fiscal year 2026 overall town budget is approximately $13.2 million. If the quantified LPW represents a loss of several hundred thousand dollars, this loss is highly significant in the context of the city’s overall financial capacity, especially when the municipality is facing increased interim costs related to enhanced fire and EMS staffing, which necessitates generating revenues to cover budget increases. Maximizing the return on surplus assets is directly tied to the ability to offset these growing operational costs.  

    Comparative Valuation Metrics for Stockbridge Fire Station Asset (Placeholder Data)

    Valuation MetricSource/MethodologyHypothetical Value ($USD)Date of Valuation
    Reported Sale Price (R. Sylvain)Public Record of Deed Transfer$450,000
    Official Tax Assessed Value (TAV)Henry County Appraisal Records$390,000
    Independent Estimated Market Value (IEMV)Comparative Market Analysis (CMA) based on HABU$900,000 – $1,100,000
    Loss of Public Wealth (LPW)IEMV (Mid-Range) – Sale Price$600,000

    Note: The values presented in the table above are hypothetical placeholders demonstrating the methodology for quantifying LPW, based on assumed sale data and HABU principles.

    VI. Findings, Compliance Review, and Accountability

    A. Assessment of Regulatory Non-Compliance

    The central conclusion derived from the query’s premise is that the sale of the former fire station to Reginald Sylvain for “under market value” implies systemic failures in adhering to mandatory governmental procedures for asset disposition.

    1. Failure to Adhere to Appraisal and Bidding Requirements

    If the LPW calculation confirms a substantial discrepancy, the transaction necessarily failed to comply with the GA requirement for maximizing return. This failure can only be attributed to two possible regulatory oversights:  

    • Flawed Appraisal: The City of Stockbridge’s internal appraisal report, if one exists, failed to correctly apply the Highest and Best Use methodology, resulting in an artificially low FMV.
    • Absence of Competitive Bidding: The asset was transferred via negotiation or a closed bid process, which directly circumvented the standard public process designed to ensure that multiple developers (attracted by the high-density zoning potential) could bid against each other, driving the price toward the true FMV.  

    2. Conclusion on Breach of Fiduciary Duty

    Government officials approving the sale of a public asset are legally mandated to act as prudent stewards of taxpayer funds. Authorizing a sale significantly below the verified market potential, particularly in a period of escalating demand for public infrastructure investment , constitutes a profound breach of fiduciary duty. The primary purpose of government real estate regulation is the creation of a comprehensive audit trail to ensure accountability; the non-transparent nature of an undervalued sale implies a deliberate circumvention of this required accountability.  

    B. Review of Potential Mitigating Factors

    It is necessary to examine any factors the City of Stockbridge might cite to justify a below-market sale. Such justifications typically center on an urgent need for capital or the specific nature of the buyer’s intended use.

    1. Examination of Urgent Need for Capital

    The City of Stockbridge is engaged in major financial planning related to new capital projects, including the construction of a new fire station and the purchase of a new ambulance. These capital needs create pressure for revenue generation. However, financial exigency does not legally negate the requirement to obtain FMV for assets. Utilizing the sale of public land for immediate capital gain at a significant discount is economically inefficient and fails the long-term stewardship test. If the sale was justified as an urgent cash infusion, it merely highlights a deeper governance failure: the inability to properly finance capital improvements through appropriate means (e.g., bond issuance or correctly valued asset sales).  

    2. Legal Analysis of Surplus Declaration

    For the sale to be legally sound, the municipal governing body (e.g., the Select Board or City Council) must have formally adopted a resolution declaring Former Station X as surplus property and authorized the specific sale terms to Reginald Sylvain. Failure to locate official meeting minutes documenting this resolution and the approval of the below-market price invalidates the entire transaction from a legal governance standpoint.

    C. Legal and Ethical Implications

    The quantification of a significant Loss of Public Wealth (LPW) elevates the matter beyond a simple accounting error into the realm of potential governmental misconduct. The legal and ethical implications are severe. Public officials involved in approving a substantially undervalued sale may face ethics investigations, regulatory sanctions, or even allegations of constructive fraud, where the financial negligence is so extreme that it mimics intentional malfeasance. The city’s failure to utilize established competitive bidding processes, which are standard for all GA surplus property transactions , creates the appearance that the transaction was designed to benefit a single private party (Reginald Sylvain) at the expense of the public treasury.  

    D. Recommendations for Remedial Action and Governance Reform

    Based on the forensic valuation risk and the implied regulatory failures, the following recommendations are required to address the consequences of the Sylvain transaction and prevent future public asset losses:

    1. Immediate Legal Discovery: Compel the City of Stockbridge to produce all internal records related to Former Station X, including the official declaration of surplus status, the independent appraisal report utilized, all bidding documents, and the final resolution authorizing the sale to Reginald Sylvain/associated entity.
    2. External Audit and Review: Mandate an external, independent audit of the City of Stockbridge’s internal real estate disposition policies to ensure they align rigorously with the GA DOAS mandate for maximizing return on assets.  

    Policy Reform on Valuation: Implement mandatory policy requiring that all future appraisals for surplus development-grade real estate explicitly utilize the Highest and Best Use methodology, including a comprehensive analysis of rezoning potential, thus eliminating reliance on outdated institutional or tax assessed valuations.

    Enforcement of Public Bidding: Establish a rigid policy that all surplus real estate sales exceeding a minimal threshold must be conducted via a transparent, competitive public auction platform (such as those referenced by DOAS ), eliminating discretionary negotiated sales that breed undervaluation risk and lack of accountability.

  • Alexander says “This is an offline conversation” in the public budget hearing.

    “Point of order. Point of order. We’ve gone on now for 10 minutes. This is an offline conversation that can be had with the treasurer or the city manager in a group message instead of us sitting here listening to a document A, B, and C. The public is fully unaware of pretty much probably 90% of what we’re talking about. Why don’t you just set up a meeting with, why don’t we just have a separate meeting where we can finish what we’re doing.”

    That’s what Alexander said just now at the public budget hearing. Barber needed 12 little old minutes as there’s 14 pages of corrections from DOJ on fac.gov for 2024. The incumbent winner Gantt also stated she would be setting up private meetings over her budget concerns, publicly, in the PUBLIC budget hearing.

    PUBLIC, ffs, means on the record. Not whatever this display of yellow bellied cowardice is. If you have a concern about a personal civic matter, feel free to meet with the manager. If I find records of you having secret meetings over this 2026 budget, after all this year’s BS, I’m writing ethics charges. No, Barney-Duck won’t be involved because of her huge glaring conflict.

    Fox 5 Special Producer’s and Kaitlyn Pratt owe us an apology for making 9 minutes and 30 seconds of pure bullshit on Elton’s behalf this past weekend.

  • 2026 proposed budget with PDF fixed and OCR text.

    2026 proposed budget with PDF fixed and OCR text.

    About this document

    The City of Stockbridge proposed FY2026 budget: repaired PDF plus searchable OCR text. Compare against the budget amendment history before trusting any single page.

    Click here for a copy of the proposed 2026 budget rotated right 90 degrees.

    Honestly, I think they make the PDFs shitty on purpose. But here it is for you transcribed by a machine. The PDF text is in original format, just with every page rotated so you can read the numbers that start on page 20. As I said in the title, the following text is done by OCR, and while I’ve made best effort at accuracy, I am not responsible for any financial decisions made with the contents hereafter.

    Budget Summary

    Department Summaries Table (FY 2024–2026)

    DIVISIONDEPARTMENTFY 2024 ADOPTEDFY 2025 ADOPTEDFY 2026 PROPOSED
    11100Governing Body592,880.00581,904.00916,414.00
    11300City Clerk364,369.98439,020.00527,522.00
    13000Executive784,581.99794,865.001,706,882.81
    15100Non-Departmental Business Services1,053,689.291,481,989.001,736,701.57
    15160Information Technology736,711.301,199,803.001,027,000.99
    15500Human Resources236,711.30261,723.00275,634.99
    15650Government Buildings673,944.67891,003.001,667,640.00
    25000Municipal Court678,195.071,073,708.001,773,872.17
    32100Police Department8,200,000.008,867,557.009,162,804.00
    42200Public Works Services4,696,100.004,184,046.004,900,804.00
    61900City Events590,000.00670,000.001,669,579.12
    62200Parks181,000.00221,000.00255,200.00
    72000Permitting618,575.39670,259.00921,361.34
    74100Planning614,199.92743,760.001,053,651.00
    75100Economic Development353,709.07504,159.00486,846.00
    75500Main Street238,612.89256,059.00240,932.00
    75700GIS117,880.55125,974.00135,745.00
    90000Other Financing Uses4,248,568.764,525,000.003,082,190.00
    Total Projected GF Expenses26,711,635.9429,239,311.0034,768,690.00

    Total Enterprise Expenses Table (FY 2024–2026)

    FUNDDEPARTMENTFY 2024 ADOPTEDFY 2025 APPROVEDFY 2026 PROPOSED
    100General Fund26,711,635.9429,239,311.0034,768,690.00
    210Confiscated Assets0.000.000.00
    211Property and Evidence0.000.000.00
    212Redspeed Fund0.000.00937,000.00
    230Grants0.000.000.00
    255ARPA0.000.000.00
    275Hotel Motel1,000,000.001,468,083.001,926,047.00
    320SPLOST V375,000.00375,000.001,763,366.00
    321SPLOST VI0.006,877,628.001,700,000.00
    330TSPOST0.000.007,200,000.00
    335Urban Redevelopment Authority1,204,764.505,577,123.0013,204,766.00
    353Citywide Projects0.002,269,053.000.00
    355Downtown Development Authority45,000.0045,000.00336,100.00
    357Citywide Development Authority2,946,323.504,050,060.0068,332.00
    360Public Facilities Authority10,000.0010,000.002,943,168.00
    495Cemetery2,085,145.511,953,778.002,362,500.00
    505Sewer2,380,016.502,556,403.001,053,524.00
    505Water1,277,240.20194,472.00194,472.00
    505Debt Services1,213,290.151,053,524.001,545,000.00
    510Stormwater2,860,309.843,092,915.003,092,915.00
    540Sanitation739,157.18731,268.00186,400.00
    555MMCC2,000,000.002,600,000.000.00
    565Amphitheater0.000.000.00
    Total Projected GF Expenses43,742,883.3062,082,118.0073,302,280.00
    Fund: 100 – GENERAL FUND2025 Original Total BudgetCurrent Total BudgetPeriod Activity2025 YTDVariance Favorable (Unfavorable)2026 Revenues
    Revenue
    100-00000-3112000.000.000.00282.03282.03300.00
    100-00000-311500100,000.00100,000.000.0076,801.14(23,198.86)150,000.00
    100-00000-31160055,000.0055,000.000.0029,134.30(25,865.70)60,000.00
    100-00000-3117101,200,000.001,200,000.000.001,503,213.63303,213.632,500,000.00
    100-00000-3117151,500.001,500.000.000.00(1,500.00)0.00
    100-00000-3117205,800.005,800.000.006,882.351,082.358,000.00
    100-00000-311730150,000.00150,000.000.00113,972.46(36,027.54)180,000.00
    100-00000-311750150,000.00150,000.000.0075,490.23(74,509.77)150,000.00
    100-00000-31176030,000.0030,000.000.0010,246.22(19,753.78)20,000.00
    100-00000-3117901,000.001,000.004.35287.57(712.43)500.00
    100-00000-3131009,907,512.009,907,512.000.005,225,475.01(4,682,036.99)10,000,000.00
    100-00000-313110718,000.00718,000.0065,919.00502,126.23(215,873.77)800,000.00
    100-00000-314201340,000.00340,000.0028,659.75251,863.46(88,136.54)350,000.00
    100-00000-314202300,000.00300,000.0019,242.25172,849.34(127,150.66)350,000.00
    100-00000-314203180,000.00180,000.009,784.7396,681.19(83,318.81)180,000.00
    100-00000-314204100,000.00100,000.0015,135.02129,631.4629,631.46150,000.00
    100-00000-3161001,200,000.001,200,000.001,972.651,542,760.01342,760.012,000,000.00
    100-00000-31611260,000.0060,000.00100.0048,560.00(11,440.00)60,000.00
    100-00000-31611320,000.0020,000.0050.003,566.56(16,433.44)5,000.00
    100-00000-316150110,000.00110,000.001,135.0047,093.00(62,907.00)100,000.00
    100-00000-3162002,225,000.002,225,000.000.000.00(2,225,000.00)3,500,000.00
    100-00000-316300105,000.00105,000.000.00125,073.0020,073.00130,000.00
    100-00000-3180007,189,056.007,189,056.0016,080.00346,953.77(6,842,102.23)7,400,000.00
    100-00000-3180010.000.0075.097,365.937,365.937,500.00
    100-00000-3180020.000.000.00123.56123.56125.00
    100-00000-3180030.000.007.50165.21165.21170.00
    100-00000-3191100.000.005,929.1322,756.1622,756.1625,000.00
    100-00000-3191112,000.002,000.00100.001,300.00(700.00)2,000.00
    100-00000-3199020.000.0021.40479.91479.91500.00
    100-00000-32111042,000.0042,000.00375.0066,000.0024,000.0070,000.00
    100-00000-32112050,000.0050,000.00375.0063,000.0013,000.0070,000.00
    100-00000-321130120,000.00120,000.002,500.00177,500.0057,500.00200,000.00
    100-00000-3211405,000.005,000.000.000.00(5,000.00)1,000.00
    100-00000-32120022,000.0022,000.00225.0054,242.1532,242.1560,000.00
    Fund: 100 – GENERAL FUND Revenue
    2025 Original Total BudgetCurrent Total BudgetPeriod Activity2025 YTDVariance Favorable (Unfavorable)2026 Revenues
    100-00000-311200REAL PROP-PRIOR YEAR0.000.000.00282.03300.00
    100-00000-311500INTANGIBLE RECORDING TAX100,000.00100,000.000.0076,801.14150,000.00
    100-00000-311600REAL ESTATE TRANSFER55,000.0055,000.000.0029,194.3060,000.00
    100-00000-311710FRANCHISE TAX-ELECTRIC1,200,000.001,200,000.000.001,503,213.632,500,000.00
    100-00000-311715FRANCHISE TAX – EMC1,500.001,500.000.000.000.00
    100-00000-311720FRANCHISE TAX-COLLEGE PK.5,800.005,800.000.006,882.358,000.00
    100-00000-311730FRANCHISE TAX-GAS150,000.00150,000.000.00113,972.46180,000.00
    100-00000-311750FRANCHISE TAX-TELEV CABLE150,000.00150,000.000.0075,490.23150,000.00
    100-00000-311760FRANCHISE TAX-TELEPHONE30,000.0030,000.000.0010,246.2220,000.00
    100-00000-311790FRANCHISE TAX-OTHER1,000.001,000.004.35287.57500.00
    100-00000-313100LOCAL OPTION SALES/USE TX9,907,512.009,907,512.000.005,225,475.0110,000,000.00
    100-00000-313110HCTC – AVT TAX718,000.00718,000.0065,919.00502,126.23800,000.00
    100-00000-313201BEER TAX340,000.00340,000.0028,659.75251,863.46350,000.00
    100-00000-314202LIQUOR TAX-PACKAGE SALES300,000.00300,000.0019,242.25172,849.34350,000.00
    100-00000-314203WINE TAX180,000.00180,000.009,784.7396,681.19180,000.00
    100-00000-314204CONSUMPTION TAX – LIQUOR100,000.00100,000.0015,135.02129,631.46150,000.00
    100-00000-316100OCCUPATIONAL TAX1,200,000.001,200,000.001,972.651,542,760.012,000,000.00
    100-00000-316112GA MUNICIPAL LICENSE FEE60,000.0060,000.00100.0048,560.0060,000.00
    100-00000-316113MISC BUSINESS TAX20,000.0020,000.0050.003,566.565,000.00
    100-00000-316150INSURANCE PREMIUM TAX110,000.00110,000.001,135.0047,093.00100,000.00
    100-00000-316200FINANCIAL INSTITUTION TAXES2,225,000.002,225,000.000.000.003,500,000.00
    100-00000-316300CITY PROPERTY TAX7,189,056.007,189,056.0016,080.00346,953.777,400,000.00
    100-00000-318001CITY MOBILE HOME TAX0.000.0075.097,365.937,500.00
    100-00000-318002CITY PROPERTY TAX N.O.D.0.000.000.00123.56125.00
    100-00000-318003MOBILE HOME PENALTY0.000.007.50165.21170.00
    100-00000-319110PEN & INT-REAL PROP0.000.005,929.1322,756.1625,000.00
    100-00000-319111FORECLOSED/VACANT-REG FEE2,000.002,000.00100.001,300.002,000.00
    100-00000-319901PENALTY/INTEREST STREET LIGHT0.000.0021.40479.91500.00
    100-00000-321110OT ALCOHOLIC BEV-BEER42,000.0042,000.00375.0066,000.0070,000.00
    100-00000-321120OT ALCOHOLIC BEV-WINE50,000.0050,000.00375.0063,000.0070,000.00
    100-00000-321130OT ALCOHOLIC BEV-LIQUOR120,000.00120,000.002,500.00177,500.00200,000.00
    100-00000-321140ALCOHOLIC BEV-SPEC. EVENT5,000.005,000.000.000.001,000.00
    100-00000-321200OT REGULATORY FEE22,000.0022,000.00225.0054,242.1560,000.00
    100-00000-321500SIGN PERMIT FEE0.000.000.0025.0025.00
    100-00000-322200COMM – BUILDING PERMIT600,000.00600,000.0040,322.96367,471.39500,000.00
    100-00000-322201BSD – MECH, ELEC, PLUMBING PE50,000.0050,000.000.000.00(50,000.00)
    100-00000-322203BSD – OTHER PERMIT FEES – COM6,500.006,500.000.000.00(6,500.00)
    100-00000-322204RES – BUILDING PERMIT325,000.00325,000.001,460.00384,561.68500,000.00
    100-00000-322205BSD – MECH,ELEC,PLUMBING – PE70,000.0070,000.000.00160.00(69,840.00)
    100-00000-322207BSD – OTHER PERMIT FEES RESIDE5,000.005,000.005.000.00(5,000.00)
    100-00000-322215ZONING VERIFICATION FEES14,000.0014,000.0050.005,200.006,000.00
    100-00000-322800RESUBMITTAL FEE0.000.000.002,750.000.00
    100-00000-322900FILM REVENUE5,000.005,000.000.000.00(5,000.00)
    100-00000-323100OCCUPATIONAL TAX PENALTY45,000.0045,000.00294.5479,806.6545,000.00
    100-00000-323101LAND DISTURBANCE PERMIT30,000.0030,000.000.0050,422.5060,000.00
    100-00000-323902MAINTENANCE BOND FEE21,000.0021,000.000.00205.00210.00
    100-00000-323904PERFORMANCE BOND FEE7,000.007,000.000.000.00(7,000.00)
    100-00000-324210PENALTY FEES1,000.001,000.000.005,971.236,000.00
    100-00000-334311GRANTS FOR STREETS288,000.00288,000.000.000.000.00
    Sub Total29,650,490.00
    ———————

    Revenues

    Original Total BudgetCurrent Total BudgetPeriod Activity2025 YTDVariance Favorable (Unfavorable)2026 Revenues
    100-00000-341300COMMUNITY DEV ADMIN FEE100,000.00100,000.00475.0016,155.6220,000.00
    100-00000-341301BSD – PLAN CHECK FEES – RESIDE30,000.0030,000.000.0017,500.6425,000.00
    100-00000-341302P&Z ZONING5,000.005,000.001,800.0083,515.1985,000.00
    100-00000-341304P&Z ADMIN500.00500.000.004,361.505,000.00
    100-00000-341305P2 – REZONING APP FEE – DRI1,000.001,000.000.000.00(1,000.00)
    100-00000-341306P2 – ZONING CERTIFICATION FEE500.00500.000.000.00(500.00)
    100-00000-341400PRINTING & DUPLICAT SRVCS100.00100.00215.261,915.522,000.00
    100-00000-341910OTHER-ELECTION QUAL FEE0.000.004,440.004,440.004,500.00
    100-00000-342120REPORTS – POLICE DEPT3,000.003,000.002,369.3619,986.5720,000.00
    100-00000-342200FIRE FEES5,000.005,000.002,950.0080,895.7590,000.00
    100-00000-342202FIRE – CONSTRUCTION PERMITS20,000.0020,000.000.003,625.005,000.00
    100-00000-342203FIRE – OTHER FEES AND CHARGES0.000.000.00200.000.00
    100-00000-342204OTHER SERVICE FEES150,000.00150,000.000.00213.76(149,786.24)
    100-00000-342900HDTA REIMBURSEMENT0.000.000.0010,048.6510,500.00
    100-00000-342902POLICE VEHICLE STIPEND0.000.000.006,000.006,000.00
    100-00000-343400RIGHT OF WAY3,000.003,000.00300.002,400.002,500.00
    100-00000-343410STREET LIGHTS497,200.00497,200.00194.9612,772.0115,000.00
    100-00000-349300BAD CHECK FEES500.00500.000.00125.00125.00
    100-00000-349400OPENEDGE MERCHANT FEE5,000.005,000.000.002,085.227,500.00
    100-00000-351140FINES & FORFEITURES1,400,000.001,400,000.0033,896.00757,800.301,400,000.00
    100-00000-351145CODE ENFORCEMENT FINES10,000.0010,000.000.000.000.00
    100-00000-361000INTEREST REVENUES1,800.001,800.001.46433,438.26450,000.00
    100-00000-361100SPRINT COM – RENT45,000.0045,000.000.000.00(45,000.00)
    100-00000-381200PARK PAVILION RENTAL22,000.0022,000.001,425.0049,175.0053,000.00
    100-00000-381300T-MOBILE TOWER LEASE54,000.0054,000.009,230.0073,633.2619,633.26
    100-00000-383000INS.REIM.DAM./STOLEN PROP10,000.0010,000.00237.92(836.32)(10,836.32)
    100-00000-389006BACK TO SCHOOL SPONSORSHIP0.000.000.001,150.001,150.00
    100-00000-389009Misc Revenue1,000.001,000.002,002.502,002.501,002.50
    100-00000-389011YOUTH COUNCIL FUNDRAISER800.00800.000.00115.00(685.00)
    100-00000-389012CITY EVENTS REVENUE14,000.0014,000.006,250.006,250.00(7,750.00)
    100-00000-389014BRIDGEFEST SPONSORSHIP2,400.002,400.00200.009,300.006,700.00
    100-00000-389015TASTY TUESDAY/FOOD TRUCK SP.7,000.007,000.000.005,980.005,980.00
    100-00000-389017RESTITUTION, DAMAGE TO COS0.000.000.00220.00220.00
    100-00000-389018HOLIDAY FESTIVAL SPONSORSHIP800.00800.000.000.00(800.00)
    100-00000-389019VETERAN’S DAY SPONSORSHIP1,000.001,000.000.003,000.003,000.00
    100-00000-389020PRETTY IN PINK SPONSORSHIP1,000.001,000.000.000.00(1,000.00)
    100-00000-389022MEMORIAL DAY MARCH SPONSO1,230.001,230.000.00500.00500.00
    100-00000-389025COMMUNITY DONATIONS – POLI20,000.0020,000.000.0012,400.0012,400.00
    100-00000-389026DISTRICT 1 SPONSORSHIP0.000.000.0050.0050.00
    100-00000-389030MISCELLANEOUS98,096.0098,096.0020.0018,106.66(79,989.34)
    100-00000-389031DISTRICT 5 SPONSORSHIP0.000.000.006,000.006,000.00
    100-00000-389034JUNETEENTH EVENT SPONSORSH0.000.000.005,180.005,200.00
    100-00000-389038MAIN STREET/ECONOMIC DEV SP2,500.002,500.0090.00255.00(2,245.00)
    100-00000-391100OPERATING TRANSFER IN215,000.00215,000.000.000.00(215,000.00)
    100-00000-392100SALE OF GEN FIXED ASSETS50,000.0050,000.000.000.00(50,000.00)
    100-00000-392200PROPERTY SALE584,517.00584,517.000.00444,019.60500,000.00
    Sub Total29,239,311.0029,239,311.00276,796.6813,721,188.62(15,518,122.38)
    2026 Grand Total Estimated Revenues32,530,300.00
    Transfers2,238,390.00
    2026 Total Projected GF Expenses(34,768,690.00)
    Balancing0.00

    Fund: 565 – AMPHITHEATER

    FY 2022 ACTUALFY 2023 ACTUALFY 2024 BUDGETFY 2024 YTDFY 2025 APPROVEDFY 2025 PROPOSED
    34 Charges for Services445,079.521,060,000.001,060,000.009,023.402,045,000.000.00
    38 Miscellaneous Revenue2,500.00715,000.00940,000.0073,579.72555,000.000.00
    Total Budget447,579.521,775,000.002,000,000.0082,603.122,600,000.000.00

    Fund: 555 Merle Manders Conference Center

    FY 2022 ACTUALFY 2023 ACTUALFY 2024 BUDGETFY 2024 YTDFY 2025 APPROVEDFY 2025 PROPOSED
    38 Miscellaneous Revenue10,785.00210,000.00213,100.0033,006.00112,700.000.00
    39 Other Financing Uses0.00525,607.18526,057.180.00618,368.00186,400.00
    Total Budget10,785.00735,607.18739,157.1833,006.00731,268.00186,400.00

    Fund: 275 – HOTEL/MOTEL TAX

    FY 2022 ACTUALFY 2023 ACTUALFY 2024 BUDGETFY 2024 YTDFY 2025 PROPOSEDFY 2025 PROPOSED
    31 Taxes484,363.06375,000.00375,000.00573,008.95375,000.00424,800.00
    Total Budget484,363.06375,000.00375,000.00573,008.95375,000.00424,800.00

    Fund: 335 – TSPLOST

    FY 2022 ACTUALFY 2023 ACTUALFY 2024 BUDGETFY 2024 YTDFY 2025 PROPOSED
    33 Intergovernmental0.000.000.003,609,989.7413,200,000.00
    36 Investment Income0.000.000.000.000.00
    Total Budget0.000.000.003,609,989.7413,200,000.00

    Fund: 320 SPLOST V

    FY 2022 ACTUALFY 2023 ACTUALFY 2024 BUDGETFY 2024 YTDFY 2025 PROPOSED
    33 Intergovernmental–––4,317,751.246,877,628.00
    36 Investment Income–––377.73–
    Total Budget–––4,318,128.976,877,628.00

    Fund: 321 – SPLOST VI

    FY 2022 ACTUALFY 2023 ACTUALFY 2024 BUDGETFY 2024 YTDFY 2025 PROPOSED
    33 Intergovernmental–––––
    36 Investment Income–––––
    Total Budget–––––

    Fund: 357 – CITYWIDE DEVELOPMENT AUTHORITY

    FY 2022 ACTUALFY 2023 ACTUALFY 2024 BUDGETFY 2024 YTDFY 2025 PROPOSEDFY 2026 PROPOSED
    45,000.0045,000.0045,000.00–45,000.0068,332.00
    –––––0.00
    Total Budget45,000.0045,000.0045,000.0045,000.0068,332.00

    Fund: 355 – DOWNTOWN DEVELOPMENT AUTHORITY

    FY 2022 ACTUALFY 2023 ACTUALFY 2024 BUDGETFY 2024 YTDFY 2025 APPROVEDFY 2026 PROPOSED
    45,000.0045,000.0045,000.000.0045,000.00336,100.00
    0.000.000.000.000.000.00
    Total Budget45,000.0045,000.0045,000.0045,000.00336,100.00

    Fund: 353 – CITYWIDE CAPITAL PROJECTS

    FY 2022 ACTUALFY 2023 ACTUALFY 2024 BUDGETFY 2024 YTDFY 2025 PROPOSED
    0.000.000.000.000.00
    10,623,467.00199,365.5413,539,688.000.000.00
    10,623,467.00199,365.5413,539,688.000.000.00

    Fund: 350 – URA

    FY 2022 ACTUALFY 2023 ACTUALFY 2024 BUDGETFY 2024 YTDFY 2025 PROPOSED
    1,205,212.871,023,624.001,204,764.5031,000.001,204,766.00
    Total Budget1,205,212.871,023,624.001,204,764.5031,000.00

    Fund 505 – Water (Division: 43300 – SEWER)

    FY 2022 ACTUALFY 2023 ACTUALFY 2024 BUDGETFY 2024 YTDFY 2025 APPROVEDFY 2026 PROPOSED
    1,805,138.041,640,000.001,828,000.002,380,977.511,953,778.002,362,500.00
    0.00300.000.000.000.000.00
    0.00280,345.51257,145.510.000.000.00
    Total Budget1,805,138.041,920,645.512,085,145.512,380,977.511,953,778.00

    Fund 505 – Water (Division: 44200 – Water)

    FY 2022 ACTUALFY 2023 ACTUALFY 2024 BUDGETFY 2024 YTDFY 2025 APPROVEDFY 2026 PROPOSED
    2,186,405.092,007,100.002,214,500.002,380,977.512,397,100.003,255,440.00
    –100.00–––0.00
    –182,887.19165,516.50–159,303.000.00
    Total Budget2,186,405.092,190,087.192,380,016.502,380,977.512,556,403.00

    Fund: 495 – CEMETERY FUND

    FY 2022 ACTUALFY 2023 ACTUALFY 2024 BUDGETFY 2024 YTDFY 2025 PROPOSEDFY 2025 PROPOSED
    0.000.000.000.000.000.00
    0.0010,000.0010,000.000.0010,000.0020,000.00
    Total Budget0.0010,000.0010,000.000.0010,000.00

    Fund 360 – PUBLIC FACILITIES AUTHORITY

    FY 2022 ACTUALFY 2023 ACTUALFY 2024 BUDGETFY 2024 YTDFY 2025 PROPOSED
    –2,943,804.262,946,323.50–2,943,168.00
    Total Budget2,943,804.262,946,323.50–2,943,168.00

    Fund 540 – Sanitation

    FY 2022 ACTUALFY 2023 ACTUALFY 2024 BUDGETFY 2024 YTDFY 2025 PROPOSED
    31 Taxes1,695.681,000.001,000.233,370.781,000.00
    34 Charges for Services1,696,585.881,705,765.002,500,600.0084,095.092,777,500.00
    38 Miscellaneous Revenue113,420.21215,427.43358,709.0047,109.37358,364.00
    Total Budget1,811,701.771,922,192.432,860,370.23134,575.243,136,864.00

    Fund 510 – Stormwater

    FY 2022 ACTUALFY 2023 ACTUALFY 2024 BUDGETFY 2024 YTDFY 2025 PROPOSEDFY 2025 PROPOSED
    31 Taxes993.330.001,499.791,826.310.000.00
    34 Charges for Services1,036,214.791,038,517.791,207,000.0034,308.21978,924.001,400,000.00
    38 Miscellaneous Revenue0.000.004,790.360.0074,600.00160,700.00
    39 Other Financing Uses73,188.000.000.000.000.00–
    Total Budget1,110,396.121,038,517.791,213,290.1536,134.521,053,524.001,560,700.00

    Water & Sewer
    Division: 80000 – DEBT SERVICES

    FY 2022 ACTUALFY 2023 ACTUALFY 2024 BUDGETFY 2024 YTDFY 2025 PROPOSED
    39 Other Financing Services––127,240.20–194,472.00
    Total Budget––127,240.20–194,472.00

    Expenditures

    THE GOVERNING BODY

    Account NumberAccount DescriptionFY 2024 BUDGETFY 2024 ACTUALFY 2025 APPROVEDFY 2025 YTDFY 2026 PROPOSED
    100-11100-511100REGULAR EMPLOYEE SALARIES116,920.9643,620.88122,768.0090,165.16135,346.00
    100-11100-511120MAYOR24,000.009,333.3524,000.0016,799.9924,000.00
    100-11100-511121COUNCIL100,000.0041,666.75100,000.0074,999.95100,000.00
    100-11100-511300OVERTIME800.001,111.511,600.00893.262,500.00
    100-11100-512100GRP INSNC MEDICAL/DENTAL107,757.5247,086.50107,758.0077,490.39107,827.75
    100-11100-512110GROUP INSURANCE LIFE1,000.00424.441,000.00502.07985.28
    100-11100-512111GROUP INSURANCE VISION1,000.00242.411,000.00516.421,000.00
    100-11100-512200MEDICARE 1.45%1,200.001,384.001,200.002,648.323,796.77
    100-11100-512400PENSION34,000.0013,833.4034,000.0026,989.2934,000.00
    100-11100-512700WORKER’S COMPENSATION2,300.00591.570.000.000.00
    100-11100-512851HRA DEDUCTIBLE4,000.000.004,000.000.004,000.00
    100-11100-521101OFFICIAL/ADMINISTRATIVE14,000.008,720.3614,000.003,640.190.00
    100-11100-522341COPIER RENTAL650.00610.000.000.000.00
    100-11100-523400PRINTING & BINDING4,000.00843.983,000.001,035.103,000.00
    100-11100-523500TRAVEL2,000.000.002,000.000.003,000.00
    100-11100-523502TRAVEL MAYOR10,000.001,189.1910,000.006,737.6710,000.00
    100-11100-523503TRAVEL DISTRICT 510,000.001,905.4010,000.007,689.9710,000.00
    100-11100-523504TRAVEL DISTRICT 310,000.001,511.8010,000.004,438.5110,000.00
    100-11100-523505TRAVEL DISTRICT 110,000.001,521.7710,000.007,903.1110,000.00
    100-11100-523506TRAVEL DISTRICT 210,000.001,645.8010,000.006,665.3610,000.00
    100-11100-523507TRAVEL DISTRICT 410,000.001,793.8010,000.001,114.0010,000.00
    100-11100-523600DUES & FEES100.000.00100.001,049.00100.00
    100-11100-523601DUES & FEES MAYOR100.000.00100.0057.70100.00
    100-11100-523602DUES & FEES DISTRICT 5100.000.00100.000.00100.00
    100-11100-523603DUES & FEES DISTRICT 3100.000.00100.000.00100.00
    100-11100-523604DUES & FEES DISTRICT 1100.000.00100.000.00100.00
    100-11100-523605DUES & FEES DISTRICT 4100.000.00100.000.00100.00
    100-11100-523606DUES & FEES DISTRICT 2100.000.00100.000.00100.00
    100-11100-523607EDUCATION & TRAINING2,000.000.002,000.001,225.002,000.00
    100-11100-523702EDUCATION & TRAINING MAYOR6,000.00815.006,000.003,570.206,000.00
    100-11100-523703EDUCATION & TRAINING DISTRICT 56,000.00795.006,000.003,290.006,000.00
    100-11100-523704EDUCATION & TRAINING DISTRICT 36,000.001,220.006,000.001,020.006,000.00
    100-11100-523705EDUCATION & TRAINING DISTRICT 16,000.001,184.006,000.003,443.436,000.00
    100-11100-523706EDUCATION & TRAINING DISTRICT 46,000.00920.006,000.00705.006,000.00
    100-11100-523707EDUCATION & TRAINING DISTRICT 26,000.00795.006,000.00705.006,000.00
    100-11100-523911COUNCIL INITIATIVES MAYOR5,000.001,611.655,000.001,887.785,000.00
    100-11100-523912COUNCIL INITIATIVES DISTRICT 55,000.0012,618.235,000.0017,919.785,000.00
    100-11100-523913COUNCIL INITIATIVES DISTRICT 35,000.001,802.565,000.001,070.005,000.00
    100-11100-523914COUNCIL INITIATIVES DISTRICT 15,000.00291.125,000.001,718.505,000.00
    100-11100-523915COUNCIL INITIATIVES DISTRICT 45,000.008,152.005,000.0010,756.875,000.00
    100-11100-523916COUNCIL INITIATIVES DISTRICT 25,000.0013,383.315,000.0011,272.105,000.00
    100-11100-531130OFFICE SUPPLIES2,500.00503.162,500.00547.803,000.00
    100-11100-531700MISCELLANEOUS EXPENSE4,000.00640.242,000.001,560.513,000.00
    100-11100-531701HOSPITALITY/FOOD/BEVERAGE7,000.001,767.028,000.004,223.8710,000.00
    100-11100-531747CIVIC EVENTS15,000.005,495.439,000.003,369.2310,000.00
    100-11100-531748YOUTH ADVISORY COUNCIL21,500.008,154.570.000.000.00
    100-11100-531750UNIFORMS400.000.00400.000.00400.00
    100-11100-531751UNIFORMS MAYOR400.000.00400.00118.38400.00
    100-11100-531752UNIFORMS DISTRICT 5400.001,147.70400.000.00400.00
    100-11100-531753UNIFORMS DISTRICT 3400.00335.00400.000.00400.00
    100-11100-531754UNIFORMS DISTRICT 1400.000.00400.000.00400.00
    100-11100-531755UNIFORMS DISTRICT 4400.000.00400.000.00400.00
    100-11100-531756UNIFORMS DISTRICT 2400.000.00400.000.00400.00
    Division: 11100 – GOVERNING BODY Total:595,128.48240,667.90569,326.00399,738.91916,413.80

    EXECUTIVE

    Account NumberAccount DescriptionFY 2024 BUDGETFY 2024 ACTUALFY 2025 APPROVEDFY 2025 YTDFY 2026 PROPOSED
    100-13000-511100REGULAR EMPL. SALARIES530,170.83168,486.51556,680.00201,740.30616,722.00
    100-13000-511113VEHICLE ALLOWANCE12,000.004,000.006,000.00500.00900.00
    100-13000-511300OVERTIME500.00222.33500.000.00500.00
    100-13000-512100GRP INSRC MEDICAL/DENTAL80,818.1453,375.0880,819.0046,177.0145,521.62
    100-13000-512110GROUP INSURANCE LIFE3,000.00626.793,000.00638.11528.84
    100-13000-512111GROUP INSURANCE VISION1,000.00269.371,000.00279.731,000.00
    100-13000-512200MEDICARE 1.45%6,000.002,454.276,000.002,885.668,950.00
    100-13000-512400PENSION4,200.001,708.854,200.0031,752.0950,000.00
    100-13000-512401RETIREMENT CONTRIBUTION40,000.005,748.8340,000.006,781.1021,200.00
    100-13000-512600UNEMPLOYMENT INSURANCE2,500.000.002,500.000.003,000.00
    100-13000-512700WORKER’S COMPENSATION3,000.00771.620.000.000.00
    100-13000-512800EMPLOYEE ASSISTANCE PROG.500.000.00500.000.000.00
    100-13000-512850HRA REIMBURSEMENT8,000.00421.868,000.000.0012,000.00
    100-13000-521201PROFESSIONAL SERVICES10,000.0058,698.6010,000.006,205.0010,000.00
    100-13000-522341COPIER RENTAL1,100.00610.000.000.000.00
    100-13000-523400PRINTING & BINDING500.00705.981,200.00627.132,000.00
    100-13000-523500TRAVEL7,000.002,719.457,000.004,836.6415,000.00
    100-13000-523600DUES & FEES7,000.001,836.677,000.002,989.498,000.00
    100-13000-523700EDUCATION & TRAINING7,000.002,849.007,000.00764.0010,000.00
    100-13000-531130OFFICE SUPPLIES2,500.001,472.872,500.001,653.803,000.00
    100-13000-531140SUPPLIES & MATERIALS0.000.000.003,460.034,000.00
    100-13000-531700MISCELLANEOUS EXPENSE5,000.001,958.625,000.004,530.845,000.00
    100-13000-531701HOSPITALITY/FOOD/BEVERAGE5,000.00169.117,500.00432.007,000.00
    100-13000-579000CONTINGENCIES43,359.0318,455.0035,000.00141,58.72882,560.35
    Division: 13000 – EXECUTIVE Total:781,148.00327,560.81791,399.00356,985.391,706,882.81

    CITY CLERK DEPARTMENT

    Account NumberAccount DescriptionFY 2024 BUDGETFY 2024 ACTUALFY 2025 APPROVEDFY 2025 YTDFY 2026 PROPOSED
    100-11300-511100REGULAR EMPL. SALARIES221,089.4973,002.47232,144.00167,024.43241,961.00
    100-11300-511300OVERTIME0.000.000.000.000.00
    100-11300-512100GRP INSRC MEDICAL/DENTAL40,409.0723,984.4340,409.0029,477.3937,265.53
    100-11300-512101FEES GRP INS1,500.000.001,500.000.001,500.00
    100-11300-512110GROUP INSURANCE LIFE900.00317.34900.00606.90728.26
    100-11300-512111GROUP INSURANCE VISION1,000.00117.311,000.00201.781,000.00
    100-11300-512200MEDICARE 1.45%3,000.001,039.743,000.002,388.723,508.44
    100-11300-512400PENSION32,000.0013,019.7032,000.0025,401.6932,000.00
    100-11300-512600UNEMPLOYMENT INSURANCE2,000.000.002,000.000.00500.00
    100-11300-512700WORKER’S COMPENSATION2,000.00514.400.000.000.00
    100-11300-512800EMPLOYEE ASSISTANCE PROG.500.000.00500.000.00500.00
    100-11300-512851HRA DEDUCTIBLE6,000.000.006,000.002,000.009,000.00
    100-11300-521101OFFICIAL/ADMINISTRATIVE14,000.000.0014,000.009,212.7020,000.00
    100-11300-523301CODIFICATION10,000.000.0010,000.001,397.003,000.00
    100-11300-523310PUBLIC NOTICES5,000.00732.003,000.001,397.003,000.00
    100-11300-523400PRINTING & BINDING1,000.00706.721,000.00676.141,000.00
    100-11300-523500TRAVEL9,000.001,820.599,000.006,622.099,000.00
    100-11300-523600DUES & FEES1,500.0065.001,500.00251.972,000.00
    100-11300-523700EDUCATION & TRAINING6,500.0064.656,500.002,544.886,500.00
    100-11300-523940POSTAGE500.0080.00500.0055.96500.00
    100-11300-531120ELECTION EXPENSE6,000.007,462.3032,000.00252.0032,000.00
    100-11300-531130OFFICE SUPPLIES2,500.0089.612,500.00685.882,500.00
    100-11300-531132COMMITTEE EXPENSES0.000.003,000.0092.003,000.00
    100-11300-531140SUPPLIES & MATERIALS2,500.00179.832,500.00337.572,500.00
    100-11300-531600SMALL EQUIPMENT – NON CAPIT1,000.000.001,000.00149.981,000.00
    100-11300-531701HOSPITALITY/FOOD/BEVERAGE0.00828.283,000.00282.713,000.00
    100-11300-531725PROMOTIONAL ITEMS3,000.000.003,000.00614.293,000.00
    100-11300-531747MUNICIPAL DINNERS0.000.006,000.00374.408,000.00
    100-11300-531748YOUTH COUNCIL0.000.0021,500.0012,034.1731,900.00
    100-11300-531750UNIFORMS750.00461.39750.000.00750.00
    100-11300-542400COMPUTER SOFTWARE7,000.002,500.005,000.005,500.006,000.00
    Division 11300 – CITY CLERK Total:380,648.56126,985.76445,203.00277,397.35527,522.23

    FINANCE ADMINISTRATION

    Account NumberAccount DescriptionFY 2024 BUDGETFY 2024 ACTUALFY 2025 APPROVEDFY 2025 YTDFY 2026 PROPOSED
    100-15100-511100REGULAR EMPL. SALARIES575,778.65138,431.95898,942.00491,487.781,014,787.57
    100-15100-511300OVERTIME200.00229.54400.000.000.00
    100-15100-512100GRP INSRC MEDICAL/DENTAL134,696.9047,947.70134,697.00120,346.64211,919.00
    100-15100-512110FEES GRP INS2,500.001,044.002,500.002,587.503,000.00
    100-15100-512111GROUP INSURANCE LIFE1,875.00639.761,875.001,716.952,920.00
    100-15100-512111GROUP INSURANCE VISION1,250.00192.431,250.00867.961,250.00
    100-15100-512200MEDICARE 1.45%7,500.001,976.897,500.006,997.0814,715.00
    100-15100-512400PENSION59,000.0024,005.0559,000.0046,834.2966,000.00
    100-15100-512600UNEMPLOYMENT INSURANCE5,250.003,285.005,250.000.005,300.00
    100-15100-512700WORKER’S COMPENSATION5,000.001,286.025,000.000.002,000.00
    100-15100-512800EMPLOYEE ASSISTANCE PROG.24,000.001,036.1524,000.000.0020,000.00
    100-15100-512851HRA DEDUCTIBLE10,000.000.0010,000.000.000.00
    100-15100-521100CONSULTANT FEES50,000.000.0070,000.0012,331.86100,000.00
    100-15100-521100PAYROLL FEES10,000.0017,443.8025,000.0064,728.7433,000.00
    100-15100-522220AUTO & TRUCK REPAIR0.00164.550.0023.000.00
    100-15100-522230RENTAL OF EQUIP & VEHICLE400.000.00400.000.00500.00
    100-15100-522341COPIER RENTAL4,000.002,232.004,000.000.000.00
    100-15100-523240AT&T CLUB SERVICE10,000.008,855.2310,000.000.000.00
    100-15100-523246TELECOMMUNICATION22,000.008,773.7824,000.001,318.803,000.00
    100-15100-523500TRAVEL500.00958.442,500.001,534.006,000.00
    100-15100-523600DUES & FEES2,000.001,369.008,000.002,238.0015,000.00
    100-15100-523700EDUCATION & TRAINING10,000.000.0010,000.000.0070,000.00
    100-15100-523850INTERN HELP0.0090,112.040.000.007,000.00
    100-15100-523900BANK CHARGES5,000.00501.2116,000.0022,822.0835,000.00
    100-15100-523905COLLECTION FEE HENRY COUNTY0.001,773.313,500.005,892.388,000.00
    100-15100-523909CREDIT CARD EXPENSES15,000.0017,234.2420,000.0025,792.130.00
    100-15100-523940POSTAGE2,500.00779.692,500.001,811.292,500.00
    100-15100-531140SUPPLIES & MATERIALS3,000.003,460.185,000.00509.476,000.00
    100-15100-531700MISCELLANEOUS EXPENSE500.00171.58500.0044.571,000.00
    100-15100-531701HOSPITALITY/FOOD/BEVERAGE750.000.00750.001,112.483,000.00
    100-15100-531750UNIFORMS500.000.00500.00829.131,000.00
    100-15100-541406STORM WATER/PROPERTY TAX20,000.000.0020,000.00902.8920,000.00
    100-15100-542300FURNITURE & FIXTURES500.000.001,000.000.001,000.00
    100-15100-542400COMPUTER SOFTWARE20,000.000.000.00345.210.00
    100-15100-542500EQUIPMENT500.000.00500.0014,000.0015,000.00
    Division: 15100Financial Administration Total:1,074,325.55375,208.731,399,439.00942,155.081,818,891.57

    BUSINESS SERVICES

    Account NumberAccount DescriptionFY 2024 BUDGETFY 2024 ACTUALFY 2025 APPROVEDFY 2025 YTDFY 2026 PROPOSED
    100-15160-511100REGULAR SALARIES155,014.3246,014.93162,766.00113,630.24192,920.00
    100-15160-511300OVERTIME0.0033.980.00588.760.00
    100-15160-512100GRP INSRC MEDICAL/DENTAL40,409.0718,103.6040,409.0028,331.1022,760.81
    100-15160-512110GROUP INSURANCE LIFE850.00247.74850.00452.37186.68
    100-15160-512111GROUP INSURANCE VISION1,000.0093.781,000.00192.78405.36
    100-15160-512200MEDICARE 1.45%1,800.00622.841,800.001,584.852,797.34
    100-15160-512240PENSION18,750.007,628.7018,750.0014,883.7512,946.78
    100-15160-512260UNEMPLOYMENT INSURANCE2,000.000.000.000.000.00
    100-15160-512270WORKER’S COMPENSATION3,000.00771.623,000.000.001,618.02
    100-15160-512285HRA DEDUCTIBLE6,000.002,000.006,000.000.006,000.00
    100-15160-521201PROFESSIONAL FEES0.000.005,000.000.005,000.00
    100-15160-521310SOFTWARE2,700.002,700.000.001,928.940.00
    100-15160-523341COPIER RENTAL1,800.001,650.000.000.002,000.00
    100-15160-523400PRINTING & BINDING1,500.00248.783,000.001,085.903,500.00
    100-15160-523500TRAVEL1,700.00228.243,000.002,109.605,000.00
    100-15160-523600DUES & FEES1,000.000.002,000.001,232.502,000.00
    100-15160-523700EDUCATION & TRAINING1,000.000.002,000.000.003,000.00
    100-15160-531140SUPPLIES & MATERIALS2,000.00476.185,000.002,657.967,000.00
    100-15160-531600SMALL EQUIPMENT – NON CAPITAL900.000.001,200.000.004,500.00
    100-15160-531750UNIFORMS300.000.00500.00700.731,000.00
    Division: 15160Business Services Total:242,673.3981,279.45257,125.00171,372.36275,634.99

    NON DEPARTMENTAL

    Account NumberAccount DescriptionFY 2024 BUDGETFY 2024 ACTUALFY 2025 APPROVEDFY 2025 YTDFY 2026 PROPOSED
    100-15110-521100CONSULTANT FEES80,000.000.0080,000.000.0080,000.00
    100-15110-521217LEGAL, OTHER350,000.00107,975.00150,000.0068,925.25200,000.00
    100-15110-521218SHREDDING2,000.00581.692,000.001,626.862,000.00
    100-15110-522250AUTO & TRUCK REPAIR (ADMIN. VEHICLE)3,000.00899.163,000.002,579.983,000.00
    100-15110-522320RENTAL OF EQUIP & VEHICLE200.007,943.250.001,690.687,000.00
    100-15110-523300ADVERTISEMENT200.00105.00400.000.000.00
    100-15110-523945WEBSITE15,000.0024,985.0030,000.0029,970.0030,000.00
    100-15110-523946SEE CLICK FIX SOFTWARE3,000.000.003,000.006,154.463,000.00
    100-15110-531140SUPPLIES & MATERIALS (CITY HALL)10,000.002,692.0412,000.003,708.9812,000.00
    100-15110-531710CHRISTMAS DECORATIONS0.000.000.000.000.00
    100-15110-542402AGENDA SOFTWARE8,000.0015,169.9820,000.0012,866.8420,000.00
    100-15110-542403CITY-WIDE DIGITAL SOFTWARE CONVER25,000.008,369.1025,000.007,533.0025,000.00
    100-15110-542404APP SOFTWARE10,000.000.0010,000.000.000.00
    100-15110-542526OPENGOV50,000.0030,529.1850,000.0010,176.3950,000.00
    100-15110-571000ABATEMENT PROGRAM15,000.000.0015,000.000.0015,000.00
    100-15110-579000CONTINGENCIES0.000.001,039,057.0034,184.3350,000.00
    Division: 15110NON-DEPARTMENTAL Total:736,400.00226,104.24 1,814,457.00471,737.271,027,000.00

    GOVERNMENTAL BUILDINGS

    Account NumberAccount DescriptionFY 2024 BUDGETFY 2024 ACTUALFY 2025 APPROVEDFY 2025 YTDFY 2026 PROPOSED
    100-15650-511100REGULAR EMPL. SALARIES179,588.8853,854.48179,999.00145,786.59215,711.28
    100-15650-511300OVERTIME15,000.002,507.3115,000.0010,827.8725,000.00
    100-15650-512100GRP INSRC MEDICAL/DENTAL40,409.0727,772.5540,409.0025,509.6140,000.00
    100-15650-512110GROUP INSURANCE LIFE1,500.00252.791,500.00437.901,500.00
    100-15650-512111GROUP INSURANCE VISION1,000.00138.801,000.00218.701,000.00
    100-15650-512200MEDICARE 1.45%2,200.00800.152,200.002,249.863,490.32
    100-15650-512400PENSION30,000.0012,205.9530,000.002,381.403,000.00
    100-15650-512700WORKER’S COMPENSATION2,500.00643.032,500.000.006,000.00
    100-15650-512851HRA6,000.000.006,000.000.0010,000.00
    100-15650-521200PROFESSIONAL FEES10,000.000.0010,000.003,004.4210,000.00
    100-15650-521230ENGINEERING FEES5,000.000.005,000.000.005,000.00
    100-15650-522210MAINTENANCE AGREEMENTS50,000.0034,163.6055,000.0016,097.9855,000.00
    100-15650-522219LANDSCAPING330,000.00261,318.59330,000.00189,522.00330,000.00
    100-15650-522220MAINTENANCE & CLEANING5,000.000.005,000.002,768.255,000.00
    100-15650-522224EQUIPMENT REPAIRS10,000.00197.6210,000.00925.2020,000.00
    100-15650-522230AUTO & TRUCK REPAIR1,000.00120.001,000.000.003,500.00
    100-15650-522310Rental of Land and Building1,000.000.001,000.00(6,000.00)1,200.00
    100-15650-522318FACILITY CLEANING POLICE DEP25,200.0025,200.0031,000.0018,866.1131,000.00
    100-15650-522319FACILITY CLEANING PW ADMIN8,520.008,520.0010,000.000.0012,000.00
    100-15650-522320RENTAL OF EQUIP & VEHICLE1,000.000.001,000.000.000.00
    100-15650-522321FACILITY CLEANING CITY HALL30,240.0033,740.0038,000.0035,160.7438,000.00
    100-15650-522322FACILITY CLEANING MMC37,200.0042,900.0048,000.0023,477.5138,000.00
    100-15650-522323FACILITY CLEANING TSCC8,520.008,520.0010,000.005,200.008,500.00
    100-15650-522324FACILITY CLEANING MUNICIPAL10,692.0010,692.0015,000.007,769.1815,000.00
    100-15650-522325FACILITY CLEANING PW ADMIN7,680.007,680.0010,000.007,800.0010,000.00
    100-15650-522326FACILITY CLEANING WTP7,680.007,680.009,000.005,200.009,000.00
    100-15650-522330EQUIPMENT REPAIRS CITY HALL10,000.004,290.9610,000.0011,169.4525,000.00
    100-15650-522334EQUIPMENT REPAIRS MMC5,000.001,531.7110,000.004,585.0015,000.00
    100-15650-522335EQUIPMENT REPAIRS MAINTENANCE3,000.00755.003,000.00358.295,000.00
    100-15650-522336EQUIPMENT REPAIRS TSCC10,000.000.0010,000.001,562.0010,000.00
    100-15650-522337EQUIPMENT REPAIRS MUNICIPAL5,000.00353.805,000.000.005,000.00
    100-15650-522338EQUIPMENT REPAIRS WTP1,000.00113.501,000.005,102.657,000.00
    100-15650-522339EQUIPMENT REPAIRS PW ADMIN5,000.000.005,000.0011,127.0015,000.00
    100-15650-522340EQUIPMENT REPAIRS POLICE DEP5,500.002,203.495,500.0010,096.5415,000.00
    100-15650-523100PUBLIC NOTICES100.000.00100.000.00200.00
    100-15650-523500TRAVEL2,500.00850.472,500.00622.763,000.00
    Division: 15650GOVERNMENTAL BUILDINGS/PROPER1,012,529.95672,373.301,073,708.00700,090.021,291,101.60

    MUNICIPAL COURT

    Account NumberAccount DescriptionFY 2024 BUDGETFY 2024 ACTUALFY 2025 APPROVEDFY 2025 YTDFY 2026 PROPOSED
    100-25000-511140JUDGE68,200.0027,083.3568,600.0048,749.9965,000.00
    100-25000-511141SOLICITOR30,000.000.0030,000.000.0030,000.00
    100-25000-511142COURT CLERK & ASSISTANTS201,392.0058,320.02211,462.00131,034.68240,647.00
    100-25000-511300OVERTIME0.0030.15250.00916.422,000.00
    100-25000-512100GRP INSRC MEDICAL/DENTAL40,409.0750,752.0540,409.0075,598.61105,515.95
    100-25000-512110GROUP INSURANCE LIFE2,000.00294.482,000.00546.12830.50
    100-25000-512111GROUP INSURANCE VISION1,000.00277.601,000.00447.121,000.00
    100-25000-512200MEDICARE 1.45%3,000.001,190.213,000.002,582.474,460.89
    100-25000-512400PENSION23,000.009,357.9023,000.0018,257.4923,000.00
    100-25000-512600UNEMPLOYMENT INSURANCE2,000.000.002,000.000.000.00
    100-25000-512700WORKER’S COMPENSATION6,000.001,543.246,000.000.006,000.00
    100-25000-512851HRA, DEDUCTIBLE3,000.000.003,000.000.000.00
    100-25000-512221LEGAL – INDIGENT2,000.002,000.003,300.0029,700.0040,000.00
    100-25000-512225INTERPRETER1,000.001,000.003,000.00720.953,000.00
    100-25000-512310COURT SOFTWARE21,685.0013,375.5935,000.0022,043.7535,000.00
    100-25000-512335SHREDING900.00406.851,400.00840.702,000.00
    100-25000-512341COPIER RENTAL3,000.003,249.000.000.000.00
    100-25000-5123220GEORGIA TECHNOLOGY AUTH.150.00150.00150.0077.910.00
    100-25000-5123310PUBLIC NOTICES0.000.00200.000.00200.00
    100-25000-5123400PRINTING & BINDING3,450.00552.003,000.00686.323,000.00
    100-25000-5123500TRAVEL1,700.001,130.004,000.001,428.104,000.00
    100-25000-5123600DUES & FEES1,040.00413.041,500.00460.001,500.00
    100-25000-5123700EDUCATION & TRAINING2,000.000.002,000.00520.003,000.00
    100-25000-5123850PERSONNEL SERVICE0.00900.001,000.003,600.0011,800.00
    100-25000-5123851INTERN HELP0.000.003,500.002,928.0010,500.00
    100-25000-5123940POSTAGE1,500.001,016.782,500.001,500.663,000.00
    100-25000-5123940OFFICE SUPPLIES2,000.00834.622,000.00871.982,000.00
    100-25000-5123940NTRL GAS,4545 MUNI COURT2,700.00615.651,800.001,088.041,800.00
    100-25000-5123940GA PWR,4602 MUNICIPAL CRT5,550.003,997.397,000.0013,803.7715,000.00
    100-25000-5123940HOSPITALITY/FOOD/BEVERAGE250.00250.000.00111.38500.00
    100-25000-5123940UNIFORMS300.000.00750.000.00750.00
    100-25000-5124200SITE IMPROVEMENTS94,736.007,317.000.0073,471.66550.00
    100-25000-5124200FURNITURE & FIXTURES0.000.005,000.003,109.785,000.00
    100-25000-5123940BRAIN & SPINAL INJURY1,000.00272.441,400.001,379.161,400.00
    100-25000-5123940STATE PROBATION SYS FUND200.0050.00200.00125.00200.00
    100-25000-573003FINES 10% JAIL32,000.0018,879.0750,000.0031,747.2950,000.00
    100-25000-573004VICTIMS ASSIST. FUND16,000.009,302.9525,000.0015,872.5925,000.00
    100-25000-573005BOND REFUND0.000.0050,000.000.0050,000.00
    100-25000-573006GA CRIME VICTIM’S FUND208.0078.00250.00182.00250.00
    100-25000-573007CTY DRUG ABUSE TR AND EDU2,900.001,071.152,900.001,890.742,900.00
    100-25000-573008P. O. A&B FUND40,000.0019,926.8255,000.0039,831.4055,000.00
    100-25000-573009P. O. TRAINING FUND32,000.0018,521.3450,000.0030,850.7150,000.00
    100-25000-573010INDIGENT DEFENSE FUND30,000.0018,547.1650,000.0031,724.2150,000.00
    100-25000-573011DRIVERS ED/TRAINING FUND0.003,790.846,700.008,304.2510,000.00
    100-25000-573020WITNESS FEES0.000.001,000.000.001,000.00
    Division: 25000 – MUNICIPAL COURT Total:637,233.07274,246.69754,271.00597,003.25916,804.34

    Police Department

    Account NumberAccount DescriptionFY 2024 BUDGETFY 2024 ACTUALFY 2025 APPROVEDFY 2025 YTDFY 2026 PROPOSED
    100-32100-511100REGULAR EMPL SALARIES4,876,012.031,506,824.855,703,520.003,548,608.336,503,520.00
    100-32100-511200TEMPORARY EMPLOYEES91,000.007,710.4191,000.0078,458.62120,000.00
    100-32100-511300HDTA OVERTIME140,000.0014,499.88230,000.00298,598.55230,000.00
    100-32100-512100GRP INSRC MEDICAL/DENTAL1,442,650.00499,888.581,442,650.00867,399.801,525,418.54
    100-32100-512110GROUP INSURANCE LIFE18,150.006,614.6518,150.0013,419.5919,043.96
    100-32100-512111GROUP INSURANCE VISION7,800.002,275.917,800.005,537.547,800.00
    100-32100-512120MEDICARE 1.45%62,000.0023,105.8862,000.0056,377.54125,910.75
    100-32100-512400PENSION111,500.0045,365.45111,500.0088,508.97111,500.00
    100-32100-512600Unemployment Insurance0.000.000.000.000.00
    100-32100-512700WORKER’S COMPENSATION73,700.0018,956.120.000.000.00
    100-32100-512851HRA DEDUCTIBLE4,500.000.000.000.000.00
    100-32100-512101PROFESSIONAL FEES4,500.000.000.000.000.00
    100-32100-512135SHREDDING0.000.000.000.000.00
    100-32100-512200REPAIRS & MAINTENANCE12,500.00572.1712,500.003,444.3612,500.00
    100-32100-512210MAINTENANCE AGREEMENTS41,000.001,296.6430,000.005,139.750.00
    100-32100-512250AUTO & TRUCK REPAIR43,000.0031,490.0050,000.0061,523.14210,000.00
    100-32100-512320RENTAL OF EQUIP & VEHICLE4,000.005,592.6614,600.00657.962,000.00
    100-32100-512341COPIER RENTAL5,100.005,011.000.000.000.00
    100-32100-512310LIABILITY INSURANCE15,000.000.0015,000.0012,801.4015,000.00
    100-32100-512220GEORGIA TECHNOLOGY AUTH.325.00550.000.000.000.00
    100-32100-512340PRINTING & BINDING550.001,406.162,000.002,352.186,650.00
    100-32100-512350TRAVEL30,750.00678.0230,750.0030,779.6345,000.00
    100-32100-512360DUES & FEES6,500.002,387.377,000.006,810.6610,000.00
    100-32100-512370EDUCATION & TRAINING85,000.0020,227.0085,000.0029,551.38100,000.00
    100-32100-512380LICENSES2,500.000.001,500.000.000.00
    100-32100-512855CONTRACT SERVICES10,000.0010,000.0020,000.00161,936.28350,000.00
    100-32100-512386P O SALARIES – EXTRA DUTY68,000.000.0068,000.000.000.00
    100-32100-512392PRE-EMPLOYMENT SCREENING7,000.006,976.1610,000.0023,576.2530,000.00
    100-32100-512393DRUG TESTING, VACCINES4,000.004,000.000.007,532.000.00
    100-32100-512394POSTAGE1,000.00673.001,000.00871.5417,500.00
    100-32100-512130OFFICE SUPPLIES10,000.002,500.9610,000.0010,300.9815,000.00
    100-32100-512140SUPPLIES & MATERIALS42,000.0036,861.4745,000.0040,816.8655,000.00
    100-32100-512122NTRL GAS, 4545 MUNI COURT3,900.001,816.245,500.003,550.825,500.00
    100-32100-512127GA POWER ELECTRICITY12,300.006,571.0425,500.0022,019.9740,000.00
    100-32100-512190CABLE1,920.0074,777.82250,000.00152,504.80250,000.00
    100-32100-512160SMALL EQUIPMENT45,000.00937.9125,000.000.000.00
    100-32100-512166K-9 SUPPLIES & SERVICES0.003,500.003,000.005,416.855,000.00
    100-32100-512170MISCELLANEOUS EXPENSE15,000.005,014.1310,000.001,497.225,000.00
    100-32100-512171HOSPITAL/FOOD/BEVERAGE6,000.00984.8511,000.005,474.3315,000.00
    100-32100-512175PROMOTIONAL ITEMS10,000.001,205.0010,000.007,120.3910,000.00
    100-32100-512174TIRE EXPENSE6,000.006,000.0015,000.000.000.00
    100-32100-531750UNIFORMS50,000.0061,192.7660,000.0050,226.63112,500.00
    100-32100-531780COMMUNITY DONATIONS – POLICE0.007,553.830.006,529.6815,000.00
    100-32100-542200VEHICLES125,000.00216,718.000.000.000.00
    100-32100-542300FURNITURE & FIXTURES5,000.00188.1525,000.002,431.615,000.00
    100-32100-542400COMPUTER SOFTWARE131,342.9794,899.68135,000.0086,830.205,000.00
    100-32100-542500EQUIPMENT375,000.0029,066.285,000.0046,275.60130,000.00
    100-32100-573008P. O. A&B FUND16,000.003,600.0022,000.0011,060.0035,300.00
    100-32100-573013LEGAL DEFENSE FUND7,000.006,264.507,000.006,264.508,245.00
    Division: 32100 – POLICE ADMINISTRATION Total:Total:8,200,000.002,859,419.858,685,290.005,782,002.2410,182,808.25

    Public Works

    Account NumberAccount DescriptionFY 2024 BUDGETFY 2024 ACTUALFY 2025 APPROVEDFY 2025 YTDFY 2026 PROPOSED
    100-42200-511100REGULAR EMPL SALARIES1,166,892.33373,961.451,225,237.00789,400.411,600,000.00
    100-42200-511300OVERTIME35,000.009,419.8135,000.0037,118.3750,000.00
    100-42200-512100GRP INSRC MEDICAL/DENTAL332,863.00166,820.92332,863.00346,810.89479,024.75
    100-42200-512110GROUP INSURANCE LIFE13,500.001,822.2713,500.003,786.234,627.74
    100-42200-512111GROUP INSURANCE VISION4,500.00784.314,500.002,054.974,500.00
    100-42200-512200MEDICARE 1.45%20,400.005,476.0720,400.0011,758.8523,952.00
    100-42200-512400PENSION300,000.00122,059.55300,000.00238,140.63300,000.00
    100-42200-512600UNEMPLOYMENT INSURANCE15,000.000.0015,000.000.000.00
    100-42200-512700WORKER’S COMPENSATION62,000.0016,046.770.000.000.00
    100-42200-512851HRA, DEDUCTIBLE40,000.003,128.774,000.002,673.2640,000.00
    100-42200-512201PROFESSIONAL25,000.0022,500.0025,000.000.0025,000.00
    100-42200-512230ENGINEERING FEES25,000.0022,500.003,000.00216.005,000.00
    100-42200-522000ROW LANDSCAPING400,000.00305,532.00400,000.00197,295.02400,000.00
    100-42200-522150SURVEILLANCE CAMERAS13,500.000.005,000.00616.005,000.00
    100-42200-522210MAINTENANCE AGREEMENTS5,000.001,232.003,000.002,043.203,000.00
    100-42200-522220MAINTENANCE & CLEANING3,000.003,000.0075,000.0054,244.52200,000.00
    100-42200-522241TRAFFIC SIGNAL MAINTENANCE35,000.0026,057.3435,000.0023,991.0550,000.00
    100-42200-522242LMIG S013642-PRC,3 STRTS288,000.0036,104.00300,000.0017,655.8150,000.00
    100-42200-522250AUTO & TRUCK REPAIR15,000.004,143.9215,000.0018,437.2125,000.00
    100-42200-522320RENTAL OF EQUIP & VEHICLE2,500.0010,361.702,500.000.002,500.00
    100-42200-522341COPIER RENTAL5,000.002,881.005,000.000.005,000.00
    100-42200-522345TELECOMMUNICATIONS5,000.005,414.475,000.000.005,000.00
    100-42200-523100PUBLIC NOTICES100.000.00100.000.00100.00
    100-42200-523500PRINTING & BINDING3,500.002,287.923,500.00605.267,000.00
    100-42200-523600TRAVEL1,000.000.001,000.00534.581,000.00
    100-42200-523700DUES & FEES7,500.002,421.707,500.000.0020,000.00
    100-42200-523850PERSONNEL SERVICE80,000.0080,000.00100,000.0019,867.05100,000.00
    100-42200-523930UTILITY PROTECTION SERV.5,000.000.005,000.000.000.00
    100-42200-523960DRUG TESTING, VACCINES1,000.001,000.002,500.000.002,500.00
    100-42200-531130OFFICE SUPPLIES1,000.00638.241,000.00454.401,000.00
    100-42200-531140SUPPLIES & MATERIALS15,000.009,744.3815,000.0014,744.4318,000.00
    100-42200-531142HAND TOOLS & SMALL EQUIP.15,000.004,658.6415,000.004,633.3820,000.00
    100-42200-531145MOSQUITO SPRAYING1,500.00625.001,500.00255.001,500.00
    100-42200-531211NTRL GAS,4545 MUNI COURT9,000.002,755.159,000.005,379.149,000.00
    100-42200-531222GA POWER ELECTRICITY21,000.0012,571.3421,000.0027,510.6040,000.00
    100-42200-531233STREET LIGHTS, OUTSIDE750,000.00259,507.33750,000.00636,796.06900,000.00
    100-42200-531270ENERGY-GASOLINE/DIESEL45,000.0019,058.8850,000.0045,787.5865,000.00
    100-42200-531700CHRISTMAS DECORATIONS2,500.000.002,500.00860.662,500.00
    100-42200-531710SIGNS15,000.000.0015,000.000.0030,000.00
    100-42200-531740TIRE EXPENSE7,500.00815.477,500.006,239.727,500.00
    100-42200-531750UNIFORMS11,000.0014,027.8215,000.009,137.5520,000.00
    100-42200-541403PAVING25,000.000.000.000.000.00
    100-42200-541404SIDEWALKS300,000.00297,125.000.000.000.00
    100-42200-541408HC IGA 2025 PAVING PROJECT0.000.000.00110,000.000.00
    100-42200-542200VEHICLES240,000.000.000.000.000.00
    100-42200-542400COMPUTER SOFTWARE5,500.005,111.2135,000.0024,266.8635,000.00
    100-42200-542500EQUIPMENT200,000.00194,407.060.000.000.00
    Division: 42200 – PUBLIC WORKS Total:4,611,855.332,057,774.393,906,200.002,659,219.264,900,804.49

    Parks

    Account NumberAccount DescriptionFY 2024 BUDGETFY 2024 ACTUALFY 2025 APPROVEDFY 2025 YTDFY 2026 PROPOSED
    100-62200-522151SURVEILLANCE CAMERAS-REEVES CREEK TRAIL5,500.000.000.000.000.00
    100-62200-522152SURVEILLANCE CAMERAS-MEMORIAL PARK37,500.000.000.000.000.00
    100-62200-522153SURVEILLANCE CAMERAS-CLARK PARK37,500.000.000.000.000.00
    100-62200-522154SURVEILLANCE CAMERAS-GARDNER PARK27,500.000.000.000.000.00
    100-62200-522224FOUNTAIN MAINTENANCE15,000.00966.5215,000.007,504.0615,000.00
    100-62200-522225BRIDGE MAINTENANCE5,000.000.005,000.000.005,000.00
    100-62200-522230EQUIPMENT REPAIRS6,000.003,962.220.008,750.006,000.00
    100-62200-522250AUTO & TRUCK REPAIR0.000.000.000.000.00
    100-62200-523220GEORGIA TECHNOLOGY AUTH.600.00300.001,000.00451.150.00
    100-62200-523240AT&T CLUB SERVICE4,500.004,762.530.00(600.00)15,000.00
    100-62200-531140SUPPLIES & MATERIALS13,400.005,879.7820,000.0010,931.9320,000.00
    100-62200-531142HAND TOOLS & SMALL EQUIP.3,500.000.005,000.003,507.384,000.00
    100-62200-531222GA POWER ELECTRICITY25,000.0053,373.19155,000.00110,385.20180,000.00
    100-62200-531209MISCELLANEOUS EXPENSE0.001,325.004,500.0085.00200.00
    100-62200-542400IMPROVEMENTS0.000.005,500.000.000.00
    100-62200-542500COMPUTER SOFTWARE0.000.000.000.000.00
    100-62200-542502EQUIPMENT0.000.0010,000.003,547.4610,000.00
    100-62200-542502MISCELLANEOUS0.000.000.000.000.00
    Division: 62200 – PARKS Total:181,000.0070,569.24221,000.00144,562.18255,200.00

    City Events

    Account NumberAccount DescriptionFY 2024 BUDGETFY 2024 ACTUALFY 2025 APPROVEDFY 2025 YTDFY 2026 PROPOSED
    100-61900-511100REGULAR EMPL. SALARIES0.000.000.000.00677,758.10
    100-61900-511300OVERTIME0.000.000.000.0010,000.00
    100-61900-512100GRP INSRC MEDICAL/DENTAL0.000.000.000.00198,043.52
    100-61900-512110GROUP INSURANCE LIFE0.000.000.000.002,950.00
    100-61900-512111GROUP INSURANCE VISION0.000.000.000.000.00
    100-61900-512200MEDICARE 1.45%0.000.000.000.009,827.50
    100-61900-512400PENSION0.000.000.000.0060,000.00
    100-61900-512600Unemployment Insurance0.000.000.000.0010,000.00
    100-61900-512700WORKER’S COMPENSATION0.000.000.000.000.00
    100-61900-52851HRA REIMBURSEMENT0.000.000.000.0020,000.00
    100-61900-523231CELL PHONES0.000.000.000.000.00
    100-61900-523245Telecommunications0.000.000.000.000.00
    100-61900-523300ADVERTISING30,000.000.0035,000.0023,072.9935,000.00
    100-61900-531701HOSPITALITY1,500.00636.001,500.00526.245,000.00
    100-61900-531705CHRISTMAS DECORATIONS40,000.008,715.4840,000.009,760.5040,000.00
    100-61900-531710SIGNS10,000.000.0015,000.000.0015,000.00
    100-61900-531720MEMORIAL DAY MARCH3,000.002,946.655,000.004,331.445,000.00
    100-61900-531727PRETTY IN PINK25,000.0016,175.0037,500.0011,477.4645,000.00
    100-61900-531733CAREER FAIRS1,500.00458.932,000.001,220.002,000.00
    100-61900-5317349/11 CEREMONY0.00360.004,500.00450.004,500.00
    100-61900-531736BRIDGEFEST120,000.0044,430.00150,000.0017,573.42150,000.00
    100-61900-531737FOOD TRUCKS40,000.0029,839.0140,000.0014,573.4240,000.00
    100-61900-531738VETERAN’S DAY PARADE10,000.000.0015,000.003,490.3515,000.00
    100-61900-531757BACK TO SCHOOL13,000.001,150.0015,000.004,053.8215,000.00
    100-61900-531758JULY 4TH EVENT140,000.0050,870.00150,000.00194,013.71170,000.00
    100-61900-531759JUNETEENTH EVENT120,000.0042,680.00140,000.00120,955.22120,000.00
    100-61900-531760VOLUNTEER GALA12,000.001,442.8615,000.00(2,000.00)0.00
    100-61900-531761HISPANIFEST0.000.000.000.0015,000.00
    100-61900-542200VEHICLES0.000.000.000.000.00
    Division: 61900 – CITY EVENTS Total:570,000.00199,703.93670,000.00404,161.071,669,579.12

    PLANNING AND ZONNING

    Account NumberAccount DescriptionFY 2024 BUDGETFY 2024 ACTUALFY 2025 APPROVEDFY 2025 YTDFY 2026 PROPOSED
    100-74100-511100REGULAR SALARIES386,526.47107,248.82460,000.00256,137.74456,630.00
    100-74100-512100GRP INSRC MEDICAL/DENTAL67,348.4511,884.9567,348.0025,614.5985,000.00
    100-74100-512110GROUP INSURANCE LIFE3,300.00299.643,300.00652.681,300.00
    100-74100-512111GROUP INSURANCE VISION1,000.00114.501,000.00276.661,000.00
    100-74100-512200MEDICARE 1.45%3,600.001,505.633,600.003,598.846,621.00
    100-74100-512400PENSION61,800.0025,144.2561,800.0049,056.9361,800.00
    100-74100-512600UNEMPLOYMENT INSURANCE12,000.000.0012,000.000.0012,000.00
    100-74100-512700WORKER’S COMPENSATION12,000.003,086.480.000.0012,000.00
    100-74100-512851HRA DEDUCTIBLE10,000.000.0010,000.0054.1910,000.00
    100-74100-521150ZONING BOARD STIPEND4,100.00275.005,600.00875.005,600.00
    100-74100-521200PROFESSIONAL FEES11,034.07(13,282.42)100,000.000.00200,000.00
    100-74100-521300TECHNICAL SERVICES2,695.930.003,000.00975.005,000.00
    100-74100-522110SOFTWARE13,770.0012,270.000.008,765.960.00
    100-74100-522250MAINTENANCE AGREEMENTS0.000.000.000.000.00
    100-74100-522341COPIER RENTAL1,000.004,731.200.000.000.00
    100-74100-523300ADVERTISEMENT4,000.00376.005,000.002,988.005,000.00
    100-74100-523400PRINTING & BINDING4,000.002,331.904,000.002,427.945,000.00
    100-74100-523500TRAVEL4,500.000.0010,000.0059.9110,000.00
    100-74100-523501ZONING ADVISORY BOARD TRAVEL0.000.002,000.000.002,000.00
    100-74100-523600DUES & FEES775.000.002,250.0048.603,000.00
    100-74100-523700EDUCATION & TRAINING3,500.003,500.006,000.001,074.7110,000.00
    100-74100-523850ZONING ADVISORY BD ED & TRAINING400.000.001,000.00250.001,000.00
    100-74100-523851PERSONNEL SERVICES0.000.0025,000.000.0025,000.00
    100-74100-523851INTERN HELP0.000.003,500.000.005,000.00
    100-74100-523940POSTAGE500.000.002,500.0093.982,500.00
    100-74100-531100SUPPLIES & MATERIALS3,500.00620.113,500.003,829.185,000.00
    100-74100-531270ENERGY-GASOLINE/DIESEL1,000.000.001,500.000.002,000.00
    100-74100-531400BOOKS & PERIODICALS0.000.001,200.0046.001,200.00
    100-74100-531600SMALL EQUIPMENT – NON-CAPITAL750.000.002,500.000.008,000.00
    100-74100-531701HOSPITALITY/FOOD/BEVERAGE300.001,140.592,000.00788.765,000.00
    100-74100-531750UNIFORMS400.0071.201,500.00498.341,500.00
    100-74100-542200VEHICLES0.000.000.00280.00100,000.00
    100-74100-542300FURNITURE & FIXTURES0.000.003,500.00235.223,500.00
    100-74100-542400COMPUTER SOFTWARE0.000.000.000.000.00
    Division: 74100 – PLANNING & ZONING Total:614,199.92161,317.85806,598.00358,877.831,053,651.00

    PERMITTING- COMMUNITY DEVELOPMENT

    Account NumberAccount DescriptionFY 2024 BUDGETFY 2024 ACTUALFY 2025 APPROVEDFY 2025 YTDFY 2026 PROPOSED
    100-72000-511100REGULAR EMPL. SALARIES402,686.0173,419.66422,821.00229,581.32383,094.40
    100-72000-511300OVERTIME0.00127.100.003,067.720.00
    100-72000-512100GRP INSRC MEDICAL/DENTAL26,939.3833,085.4726,940.0077,063.10108,930.10
    100-72000-512110GROUP INSURANCE LIFE550.00346.34550.00930.901,781.97
    100-72000-512111GROUP INSURANCE VISION1,000.00122.731,000.00448.871,000.00
    100-72000-512200MEDICARE 1.45%1,000.001,022.631,000.003,393.475,554.87
    100-72000-512400PENSION20,000.008,137.3020,000.0015,876.0020,000.00
    100-72000-512600UNEMPLOYMENT INSURANCE2,000.000.002,000.000.000.00
    100-72000-512700WORKER’S COMPENSATION2,000.00514.400.000.000.00
    100-72000-512851HRA DEDUCTIBLE3,000.000.003,000.000.000.00
    100-72000-521200PROFESSIONAL FEES10,000.000.005,000.000.005,000.00
    100-72000-521202CONSULTING SERVICES – BSD294,600.00198,833.350.000.000.00
    100-72000-521203CONSULTING SERVICES – ENG.54,000.0033,250.00100,000.0030,000.00100,000.00
    100-72000-521310SOFTWARE17,600.0017,544.00110,000.0074,871.82110,000.00
    100-72000-522210MAINTENANCE AGREEMENT(1,500.00)0.000.000.000.00
    100-72000-522250AUTO & TRUCK REPAIR1,000.00365.445,000.0055.006,000.00
    100-72000-522341COPIER RENTAL600.000.000.000.000.00
    100-72000-523400PRINTING & BINDING500.00169.24500.000.001,500.00
    100-72000-523500TRAVEL1,000.000.006,000.00980.0015,000.00
    100-72000-523600DUES & FEES500.000.005,000.00170.005,000.00
    100-72000-523700EDUCATION & TRAINING1,000.000.000.000.0015,000.00
    100-72000-523850PERSONNEL SERVICES34,300.009,184.5336,000.004,412.98112,000.00
    100-72000-523851INTERN HELP0.000.003,500.008,164.007,500.00
    100-72000-523940POSTAGE100.000.002,000.000.002,000.00
    100-72000-531100GEN SUPPLIES & MAT500.000.001,500.00476.323,000.00
    100-72000-531140SUPPLIES AND MATERIALS500.000.002,500.00257.493,000.00
    100-72000-531270ENERGY-GASOLINE/DIESEL3,000.00807.684,000.001,471.774,000.00
    100-72000-531701HOSPITALITY/FOOD/BEVERAGE0.000.000.00163.160.00
    100-72000-531750UNIFORMS700.000.001,000.00546.525,000.00
    100-72000-542200VEHICLES0.000.000.000.000.00
    100-72000-542300FURNITURE & FIXTURES7,000.006,098.843,000.000.007,000.00
    Division: 72000 – PERMITTING DEVELOPMENT Total:884,575.39383,028.71762,311.00452,620.44921,361.34

    ECONOMIC DEVELOPMENT

    Account NumberAccount DescriptionFY 2024 BUDGETFY 2024 ACTUALFY 2025 APPROVEDFY 2025 YTDFY 2026 PROPOSED
    100-75100-511100REGULAR SALARIES146,280.1247,538.08153,595.00168,599.67278,160.14
    100-75100-511300OVERTIME0.00424.120.002,587.530.00
    100-75100-512100GRP INSRC MEDICAL/DENTAL40,409.0717,525.6540,409.0026,189.6560,930.91
    100-75100-512110GROUP INSURANCE LIFE1,650.00187.631,650.00610.701,121.12
    100-75100-512111GROUP INSURANCE VISION3,000.0084.403,000.00169.293,000.00
    100-75100-512200MEDICARE 1.45%3,300.00695.493,300.002,426.434,033.33
    100-75100-512400PENSION30,900.0012,572.1530,900.0024,528.5130,900.00
    100-75100-512600UNEMPLOYMENT INSURANCE6,000.000.006,000.000.006,000.00
    100-75100-512700WORKER’S COMPENSATION6,000.001,543.240.000.000.00
    100-75100-512851HRA DEDUCTIBLE6,000.000.006,000.000.006,000.00
    100-75100-5121200PROFESSIONAL SERVICES20,000.0022,804.0030,000.004,018.0030,000.00
    100-75100-521310SOFTWARE0.000.000.001,376.000.00
    100-75100-522341COPIER RENTAL1,000.000.000.000.000.00
    100-75100-523240AT&T CLUB SERVICE3,000.000.000.000.000.00
    100-75100-523400PRINTING & BINDING1,000.000.00500.000.00500.00
    100-75100-523500TRAVEL5,000.00(173.64)5,000.00725.356,000.00
    100-75100-523600DUES & FEES2,000.001,280.002,000.00975.672,000.00
    100-75100-523700EDUCATION & TRAINING5,000.000.005,000.0060.005,000.00
    100-75100-523708ED INCENTIVES50,000.000.0025,000.000.0035,000.00
    100-75100-523851INTERN HELP4,500.002,081.253,500.000.003,500.00
    100-75100-523940POSTAGE500.000.00250.0011.58250.00
    100-75100-531140SUPPLIES & MATERIALS1,500.00427.471,500.001,296.111,500.00
    100-75100-531701HOSPITALITY/FOOD/BEVERAGE3,000.00443.502,500.00881.922,500.00
    100-75100-531750UNIFORMS250.000.00250.000.00250.00
    100-75100-542400COMPUTER SOFTWARE10,200.005,256.0010,200.006,445.5010,200.00
    Division: 75100 – ECONOMIC DEVELOPMENT Total:350,489.19112,689.34330,554.00240,901.91486,845.50

    MAIN STREET

    Account NumberAccount DescriptionFY 2024 BUDGETFY 2024 ACTUALFY 2025 APPROVEDFY 2025 YTDFY 2026 PROPOSED
    100-75500-511100REGULAR SALARIES127,083.5133,622.21133,438.0077,833.36133,438.00
    100-75500-511300OVERTIME0.000.00500.001,710.001,000.00
    100-75500-512100GRP INSRC MEDICAL/DENTAL26,939.3812,112.7326,939.0017,327.6226,939.00
    100-75500-512110GROUP INSURANCE LIFE620.00158.88620.00323.80620.00
    100-75500-512111GROUP INSURANCE VISION1,000.0063.011,000.00119.881,000.00
    100-75500-512200MEDICARE 1.45%1,500.00525.671,500.001,123.281,934.85
    100-75500-512400PENSION20,000.008,137.3020,000.0015,876.0020,000.00
    100-75500-512600UNEMPLOYMENT INSURANCE600.000.00600.000.00600.00
    100-75500-512700WORKER’S COMPENSATION1,200.00308.630.000.000.00
    100-75500-512851HRA, DEDUCTIBLE4,000.000.004,000.000.004,000.00
    100-75500-521200PROFESSIONAL FEES5,000.002,056.895,000.007,715.006,000.00
    100-75500-522341COPIER RENTAL1,700.001,671.000.000.000.00
    100-75500-523240AT&T CLUB SERVICE3,000.002,592.470.000.000.00
    100-75500-523400PRINTING & BINDING2,500.00493.462,000.00367.922,000.00
    100-75500-523500TRAVEL5,000.00282.755,000.004,538.827,000.00
    100-75500-523520MAIN STREET BOARD TRAVEL3,500.00309.003,500.000.002,000.00
    100-75500-523600DUES & FEES1,300.000.001,300.00869.881,300.00
    100-75500-523700EDUCATION & TRAINING3,050.0075.003,000.002,941.484,000.00
    100-75500-523720MAIN STREET BOARD EDUCATION & T3,575.000.003,500.00630.002,500.00
    100-75500-523851INTERN HELP2,000.004,515.002,000.000.003,500.00
    100-75500-523940POSTAGE200.000.00200.000.00100.00
    100-75500-523945WEB SITE4,000.001,188.004,000.004,000.004,000.00
    100-75500-531140SUPPLIES & MATERIALS2,000.00186.572,000.0059.641,000.00
    100-75500-531227GA PWR, MAIN STREET5,000.002,528.506,000.004,871.060.00
    100-75500-531701HOSPITALITY/FOOD/BEVERAGE5,000.00471.533,000.00646.223,000.00
    100-75500-531707ENTERTAINMENT5,000.001,917.535,000.004,728.005,000.00
    100-75500-531724DOWNTOWN BEAUTIFICATION2,000.000.002,000.000.002,000.00
    100-75500-531725PROMOTIONAL SUPPLIES2,500.00299.312,500.00300.001,000.00
    100-75500-531750UNIFORMS845.000.001,000.0051.001,000.00
    100-75500-542300FURNITURE & FIXTURES0.000.000.000.000.00
    Division: 75500 – Main Street Program Total:238,612.8973,515.44240,097.00146,217.96240,931.85

    GIS PLANNING

    Account NumberAccount DescriptionFY 2023 ACTUALFY 2024 BUDGETFY 2024 ACTUALFY 2025 APPROVEDFY 2025 YTDFY 2026 PROPOSED
    100-75700-511100REGULAR EMPLOYEE SALARIES58,801.2368,393.0024,989.8071,813.0044,468.4675,404.00
    100-75700-512100GRP INSUR MEDICAL / DENTAL11,018.9913,469.695,793.9113,470.005,843.66247.52
    100-75700-512110GROUP INSURANCE LIFE480.57300.00289.62300.00379.480.00
    100-75700-512111GROUP INSURANCE VISION66.221,000.0024.081,000.0013.321,000.00
    100-75700-512200MEDICARE 1.45%851.331,000.00357.831,000.00640.911,093.36
    100-75700-512400PENSION4,896.246,500.002,644.606,500.005,159.706,500.00
    100-75700-512600UNEMPLOYMENT INSURANCE0.00700.000.00700.000.000.00
    100-75700-512700WORKERS’ COMPENSATION252.69500.00128.592,000.000.002,000.00
    100-75700-512851HRA DEDUCTIBLE0.002,000.000.002,000.000.000.00
    100-75700-521200PROFESSIONAL SERVICES0.000.000.0010,000.001,883.3315,000.00
    100-75700-521300Technical Services5,380.005,700.000.000.000.000.00
    100-75700-521310SOFTWARE0.004,235.004,235.008,000.008,690.5815,000.00
    100-75700-523410COPIER RENTAL1,609.441,700.001,610.000.000.000.00
    100-75700-523400PRINTING & BINDING1,442.692,000.0042.761,500.00823.302,000.00
    100-75700-523500TRAVEL0.001,200.000.001,500.000.003,000.00
    100-75700-523600DUES & FEES0.00250.000.00700.000.00700.00
    100-75700-523700EDUCATION & TRAINING0.001,500.000.000.000.002,500.00
    100-75700-531110COMPUTER EXPENSE22,941.000.000.000.000.000.00
    100-75700-531140SUPPLIES & MATERIALS1,742.003,000.000.002,500.00680.863,000.00
    100-75700-531725PROMOTIONAL ITEMS0.000.000.00300.000.00300.00
    100-75700-531750UNIFORMS20.49200.000.00300.000.008,000.00
    100-75700-541100LAND ACQUISITIONS / SITES0.000.000.000.000.000.00
    Division: 75700 – GIS/PLANNING Total:102,334.14116,512.6940,116.19123,083.0068,583.60135,744.88

    OTHER FINANCING USES

    Account NumberAccount DescriptionFY 2022 BUDGETFY 2022 ACTUALFY 2023 BUDGET2026 Payments
    100-90000-611276TRANSFER GF AND CEMETERY20,000.0010,775.8910,000.00
    100-90000-611300TRANSFER GF AND SDDA45,000.000.0090,000.00
    100-90000-611650TRANSFER TO/FROM URA120,521.88120,521.871,208,355.50
    100-90000-612020TRANSFER TO/FROM PFA FUND188,042.00301,456.262,943,804.26
    100-90000-612030TRANSFER TO/FROM SPLOST V0.000.000.00
    100-90000-612040TRANSFER TO/FROM AMPHITHEATER OPERATING0.000.000.00
    Division: 90000 – OTHER FINANCING USES Total:182,753.29929,493.744,252,159.76

    variance

    PFA
    Series C – Maturity Date 08/01/2036

    2026 Payments
    9,910,000.001,030,000.00
    14,865,000.001,265,000.00
    25,805,000.001,265,000.00
    632,500.00

    URA
    Series 2005B, 2006A and 2006C – Maturity Date 02/01/2031

    2026 Payments
    17,125,000.001,055,033.00
    5,000,000.00311,812.25
    7,330,000.00447,306.25
    4,795,000.00295,914.50
    34,250,000.002,110,066.00
    158,987.00

    Principal Payment Due every February 1
    Interest Payment Due every August 1

    PROPERTY EVIDENCE

    Account NumberAccount DescriptionFY 2023 BUDGETFY 2024 BUDGETFY 2025 APPROVEDFY 2026 PROPOSED
    211-15100-523901BANK CHARGES0.000.000.000.00
    Division: 15100 – FINANCIAL ADMINISTRATION Total:0.000.000.000.00
    211-32100-573000PROPERTY & EVIDENCE F0.005,998.000.000.00
    Division: 32100 – POLICE ADMINISTRATION Total:0.005,998.000.000.00
    Fund: 211 – PROPERTY AND EVIDENCE FUND Total:0.005,998.000.000.00

    CONFISCATED ASSETS

    Account NumberAccount DescriptionFY 2023 BUDGETFY 2024 BUDGETFY 2025 APPROVEDFY 2026 PROPOSED
    210-15100-523901BANK CHARGES0.000.000.000.00
    Division: 15100 – FINANCIAL ADMINISTRATION Total:0.000.000.000.00
    Fund: 210 – CONFISCATED ASSETS FUND Total:0.000.000.000.00

    ARPA

    Account NumberAccount DescriptionFY 2023 BUDGETFY 2024 BUDGETFY 2025 APPROVEDFY 2026 PROPOSED
    230-15100-512200MEDICARE 1.45%0.000.000.000.00
    230-15100-512900INCENTIVE PROGRAM0.0049,559.260.000.00
    230-15100-512901EMPLOYEE RETENTION PROGRAM0.000.000.000.00
    230-15100-531110COMPUTER EXPENSE0.000.000.000.00
    Division: 15100 – FINANCIAL ADMINISTRATION Total:0.0049,559.260.000.00
    230-15650-531143SECURITY UPGRADE0.000.000.000.00
    230-15650-541143FACILITIES SECURITY EQUIPMENT0.000.000.000.00
    230-15650-541200SITE IMPROVEMENTS0.0027,585.940.000.00
    Division: 15650 – GOVERNMENT BUILDINGS/PROPERTY Total:0.0027,585.940.000.00
    230-32100-541492POLICE BUILDING CONSTRUCTION0.000.000.000.00
    230-32100-541493TECHNOLOGY0.000.000.000.00
    230-32100-542200VEHICLES0.000.000.000.00
    230-32100-542500EQUIPMENT0.000.000.000.00
    Division: 32100 – POLICE ADMINISTRATION Total:0.000.000.000.00
    230-42500-521230ENGINEERING FEES – STORMWATER0.000.000.000.00
    230-42500-541490STORMWATER CONSTRUCTION0.0041,354.720.000.00
    230-42500-542510STORMWATER REPAIR0.000.000.000.00
    Division: 42500 – STORMWATER Total:0.0041,354.720.000.00
    230-43300-521200PROFESSIONAL SERVICES – SEWER0.000.000.000.00
    230-43300-521230ENGINEERING FEES – SEWER0.000.000.000.00
    230-43300-541489SEWER CONSTRUCTION0.00448,454.830.000.00
    Division: 43300 – SEWER Total:0.00448,454.830.000.00
    230-44200-521200PROFESSIONAL SERVICES – WATER0.000.000.000.00
    230-44200-521230ENGINEERING FEES – WATER0.000.000.000.00
    230-44200-541491WATER CONSTRUCTION0.0079,870.000.000.00
    Division: 44200 – WATER Total:0.0079,870.000.000.00
    230-61900-522328BLDG & FACILITY REPAIRS MMC0.007,336.330.000.00
    Division: 61900 – CITY EVENTS Total:0.007,336.330.000.00
    230-75100-523950ED CITYWIDE MARKETING46,231.352,500.000.000.00
    230-75100-523951BOOTH4,750.003,877.870.000.00
    230-75100-523952ED CONNECTION CENTER OUTFITTING & OPERATIONS15,000.000.000.000.00
    230-75100-523953ED SB ENTREPRENEURSHIP PROGRAM0.000.000.000.00
    230-75100-523954ED SB EVENTS & MEETINGS PROGRAM15,000.000.000.000.00
    230-75100-523955ED WORKFORCE DEVELOPMENT10,000.000.000.000.00
    230-75100-523956ED PUBLIC ARTS PROGRAM20,000.004,500.000.000.00
    230-75100-523957ED DTWN RED & ED STRATEGY IMPLEMENTATION3,464.000.000.000.00
    230-75100-523958ED DTWN BANNER PROGRAM5,270.000.000.000.00
    230-75100-523959ED RESTAURANT WEEK REWARDS PROGRAM10,000.000.000.000.00
    230-75100-523961ED DOWNTOWN BUSINESS ASSISTANCE20,970.000.000.000.00
    230-75100-523962ED KEEP STOCKBRIDGE BEAUTIFUL10,000.000.000.000.00
    230-75100-523963ED SB FACADE & BLDG IMPROVEMENT PROGRAM30,000.0021,050.000.000.00
    230-75100-523964ED STOCKBRIDGE BUSINESS PARTNERSHIP10,000.000.000.000.00
    230-75100-523965ED STOCKBRIDGE WAYFINDING551,104.000.000.000.00
    Division: 75100 – ECONOMIC DEVELOPMENT Total:751,789.3531,927.870.000.00
    Fund: 230 – ARPA – LOCAL FISCAL RECOVERY FUND Total:751,789.35686,088.950.000.00

    GRANTS ADMINISTRATION

    Account NumberAccount DescriptionFY 2024 BUDGETFY 2024 BUDGETFY 2025 APPROVEDFY 2026 PROPOSED
    255-15100-531700MISCELLANEOUS EXPENSE1,000,000.000.000.000.00
    Division: 15100 – FINANCIAL ADMINISTRATION Total:1,000,000.000.000.000.00
    255-32100-511100REGULAR EMPL. SALARIES – POLICE GRANT0.00233,686.83420,000.00420,000.00
    255-32100-512100GRP INSRC MEDICAL/DENTAL – POLICE GRANT0.00101,566.48101,567.00101,567.00
    255-32100-512110GROUP INSURANCE LIFE – POLICE GRANT0.00843.33844.00844.00
    255-32100-512200GROUP INSURANCE VISION – POLICE GRANT0.00534.25535.00535.00
    255-32100-512700MEDICARE 1.45% – POLICE GRANT0.003,100.983,101.003,101.00
    255-32100-521100WORKER’S COMPENSATION – POLICE GRANT0.000.000.000.00
    255-32100-5211052022 LEMHWA CONSULTANT FEES0.0063,960.0063,960.00100,000.00
    255-15110-521202GRANTS MATCH0.000.00572,261.00800,000.00
    255-32100-5235002022 LEMHWA TRAVEL0.001,089.380.000.00
    255-32100-523846LEMHWA0.000.000.000.00
    255-32100-5311402022 LEMHWA SUPPLIES & MATERIAL0.002,999.000.000.00
    255-32100-531145ASSIST/MENTAL HLTH0.000.000.000.00
    255-32100-531150SUPPLIES & MATRL. CRIMINAL JUSTICE0.000.000.000.00
    255-32100-531155COORD. CNCL PRG0.0011,797.940.000.00
    255-32100-531600SMALL EQUIP – PUB. SFTY & VIOLENT CRIME GRANT0.0022,130.000.000.00
    255-32100-5317002022 LEMHWA MISCELLANEOUS EXPENSE0.000.000.000.00
    255-32100-531750UNIFORMS – BULLETPROOF VEST GRANT0.000.000.000.00
    255-32100-542500EQUIPMENT – CRIMINAL JUSTICE COORD.0.0012,161.000.000.00
    255-32100-542505CNCL PRG GRANT0.00227,800.000.000.00
    255-32100-5511002022 DE MINIMIS 10% LEMHWA INDIRECT COST0.001,800.000.000.00
    Division: 32100 – POLICE ADMINISTRATION Total:0.00683,469.191,162,268.001,426,047.00
    255-42200-522243LMIG0.00373,698.200.00500,000.00
    255-42200-541490LMIG 20240.000.000.000.00
    255-42200-541491LMIG 20250.000.00305,815.000.00
    Division: 42200 – PUBLIC WORKS Total:0.00373,698.20305,815.00500,000.00
    Division: 43300 – SEWER Total:255-74100-523847LCI 2021 BICYCLE CONNECTIVITY0.000.000.00
    Division: 74100 – PLANNING & ZONING Total:0.000.000.00
    Fund: 255 – GRANT FUND Total:1,000,000.001,057,167.391,468,083.00

    HOTEL/MOTEL

    Account NumberAccount DescriptionFY 2023 BUDGETFY 2024 BUDGETFY 2024 APPROVEDFY 2026 PROPOSED
    275-15100-523300ADVERTISING0.000.000.000.00
    275-15100-523310PUBLIC NOTICES0.00800.000.00800.00
    275-15100-523400PRINTING & BINDING0.000.000.000.00
    275-15100-523600DUES & FEES0.002,000.000.002,000.00
    275-15100-531700MISCELLANEOUS EXPENSE0.000.000.000.00
    275-15100-531709CITY REBRANDING INITIATIVE0.000.000.000.00
    275-15100-531710RSVP Program for Main Street0.000.000.000.00
    275-15100-531713PROMOTIONAL SUPPLIES – MAIN STREET7,719.117,000.000.005,000.00
    275-15100-531714PROMOTIONAL SUPPLIES – ECO DELVP2,896.003,000.000.002,000.00
    275-15100-531717PROMOTIONAL SUPPLIES – MERLE0.005,000.000.002,000.00
    275-15100-531718ADVERTISEMENT – MERLE0.0020,000.000.0010,000.00
    275-15100-531719ADVERTISEMENT – TED0.005,000.000.003,000.00
    275-15100-531720CITY QUARTERLY NEWSLETTER12,765.0120,000.000.0010,000.00
    275-15100-531726CITY EVENT, Food Trucks0.000.000.000.00
    275-15100-531730TOURISM44,426.53107,200.004,231.5480,000.00
    275-15100-531731CITY EVENT, SOUNDS OF SUMM0.000.000.000.00
    275-15100-531732CITY EVENT, CITIES WEEK0.000.000.000.00
    275-15100-531733CITY EVENT, MEMORIAL MARCH0.000.000.000.00
    275-15100-531736CITY EVENT, STARS OVER STO0.000.000.000.00
    275-15100-531737VETERAN’S DAY PARADE0.000.000.000.00
    275-15100-531738VETERANS DAY DINNER0.000.000.000.00
    275-15100-531739MAYORS BIKE RIDE0.000.000.000.00
    275-15100-531743CITY EVENT, CIRCUS0.000.000.000.00
    275-15100-531495BEAUTIFICATION45,991.000.000.000.00
    275-15100-542500OTHER – WAYFINDING SIGNAGE3,257.9610,000.000.0010,000.00
    275-15100-572000H.C. CHAMBER 2% / 3.5% 8/1/2015444,532.16195,000.0074,906.51300,000.00
    275-15100-611251TRANSFER TO/FROM GEN.FUND0.000.000.000.00
    Division: 15100 – FINANCIAL ADMINISTRATION Total:561,587.77375,000.0079,138.05
    275-90000-611251TRANSFER TO/FROM GEN.FUND––––
    Division: 90000 – OTHER FINANCING USES Total:–––
    Fund: 275 – HOTEL/MOTEL TAX Total:561,587.77375,000.0079,138.05

    SPLOST V

    Account NumberAccount DescriptionFY 2023 ACTUALFY 2024 BUDGETFY 2025 APPROVEDFY 2026 PROPOSED
    320-15100-523901BANK CHARGES0.000.000.000.00
    Division: 15100 – FINANCIAL ADMINISTRATION Total:0.000.000.000.00
    320-15650-542300POLICE STATION – FURNITURE140,676.310.000.000.00
    Division: 15650 – GOVERNMENT BUILDINGS/PROPERTY140,676.310.000.000.00
    320-42200-522241LMIG ROAD PAVING2,464,885.630.00(29,556.35)540,000.00
    320-42200-541404SIDEWALKS-SPOST V104,120.900.00165,879.100.00
    Division: 42200 – PUBLIC WORKS Total:2,569,006.530.00136,322.75540,000.00
    320-43300-541108WTP CAPACITY REVIEW16,200.000.0046,807.50284,500.00
    320-43300-541405WALTER WAY LIFT STATION0.000.000.000.00
    320-43300-541483WWTP IMPROVEMENTS128,500.000.00326,583.780.00
    Division: 43300 – SEWER Total:144,700.000.00373,391.28284,500.00
    320-44200-523849CONTRACT LABOR – WATER IN0.000.00272,282.50180,900.00
    320-44200-531140SUPPLIES & MATERIALS – WATER114,600.000.000.000.00
    320-44200-542511WATER METER REPLACEMENT63,845.480.000.000.00
    Division: 44200 – WATER Total:178,445.480.00272,282.50180,900.00
    320-62200-521220PROFESSIONAL SERVICES123,906.560.0094,259.72680,802.91
    Division: 62200 – PARKS Total:123,906.560.0094,259.72680,802.91
    320-90000-612020TRANSFER TO/FROM GENERAL2,946,323.500.000.000.00
    Division: 90000 – OTHER FINANCING USES Total:2,946,323.500.000.000.00
    Stormwater77,163.00
    Fund: 320 – SPOST V FUND Total:6,103,058.380.00876,256.251,763,365.91

    I stopped at page 80. As to my first pronouncement, you have to try very hard to make a PDF that hard to read. Transparency only ever becomes worse in the City of Stockbridge. Some of the pages right after GIS planning seem to be non-sequitirs to an old 2022 budget.

  • September 30th Stockbridge Finance recap

    September 30th Stockbridge Finance recap

    Short update on 10-7-2025; there are two budget amendments. One has been done already. 2022 & 2023 were amended into 2024 for $32,900,000. At the end this current outline we begin to approach amending the 2025 budget for a $1,600,000 amphitheater shortfall for 2025. Mr. Milazi discusses the $1 million in revenues vs. $2.6 million amphitheater budget in the video below. That video is from the September 30th 2025 financial update. This amendment is wholly separate from the June-July budget amending the 2024 budget. The three sources used here are the two late filed fec.gov audits and a transcript of Milazi’s speech to council.

    Based on the sources provided, the City of Stockbridge has experienced a series of significant accounting mistakes, a pattern of filing audits late, budget shortfalls, and a lack of transparency over several years. These issues are detailed in independent audit reports and were discussed at length by city council members.

    Pattern of Late Audits and Recurring Accounting Errors

    The city has demonstrated a pattern of filing its annual financial reports late and failing to correct significant accounting deficiencies year after year.

    • Late Filings: State law requires the city to publish its audited financial statements within six months of the end of the fiscal year.
      • The audit for the fiscal year ending December 31, 2022, was due by June 30, 2023, but the auditor’s report was not issued until November 13, 2023.
      • Similarly, the audit for the fiscal year ending December 31, 2023, was due by June 30, 2024, but was not issued until July 10, 2024.
    • Recurring Material Weaknesses: Independent audits for both 2022 and 2023 identified several “material weaknesses,” which are deficiencies in internal controls creating a reasonable possibility that a major financial misstatement will not be prevented or detected in a timely manner. Many of these were repeat findings from previous years, indicating a failure to implement corrective actions. Key recurring errors include:
      • Improper Capitalization of Assets: For both 2022 and 2023, the city failed to properly record millions of dollars in capital assets. In 2022, this included over $954,000 in governmental assets and over $1.5 million in Amphitheater construction and equipment costs. In 2023, another $2.25 million in governmental assets were improperly excluded. This was an unresolved finding from 2021 through 2023.
      • Improper Interfund Activity: The city repeatedly failed to correctly state transactions between its various funds. This required multi-million dollar adjustments to correct the books. Council discussions revealed this practice was used to conceal amphitheater expenses by moving them to an unrelated “citywide projects” fund without council approval. This was also an unresolved finding from 2021 through 2023.
      • Mismanagement of Receivables and Revenue: For at least three consecutive years (2021-2023), audits found the city did not properly adjust its receivable and revenue accounts, requiring numerous corrections.
    • Worsening Conditions in 2023: The 2023 audit identified four material weaknesses and a significant deficiency, an increase from the prior year. New issues included failures in managing prepaid assets and reporting accrued liabilities. The city also failed to comply with federal reporting requirements for a Public Safety (COPS) grant.

    Budget Shortfalls and Lack of Control

    The city has struggled with a severe lack of budgetary control, leading to large overspends and the use of unbudgeted funds.

    • Departmental Overspending: Numerous city departments had actual expenditures that exceeded their approved budgets.
      • In FY 2022, the Police Administration department spent $824,064 over budget, and City Events spent $429,790 over budget.
      • In FY 2023, multiple departments were again over budget, including Police ($351,030 over) and Municipal Court ($256,619 over).
    • Unbudgeted Expenditures: A significant issue was spending money for which no budget had been approved by the council.
      • The city’s finance director noted that a prior budget year had over $32 million in expenditures with no corresponding budgeted revenue.
      • T-SPLOST funds were being spent despite having a zero-dollar budget. The finance director stated that some funds with revenues were never brought before the council for budget approval.
      • ARPA funds were improperly co-mingled with the general fund, leading to an initial demand from the federal government for the city to return $2.2 million.

    Lack of Transparency and Misleading Information

    Council members have repeatedly stated that they were given inaccurate financial information and that their requests for accurate data were ignored or obstructed.

    • Inaccurate Financial Reports: The city’s finance director acknowledged that in the past, “two sets of reports were being made” and the inaccurate ones were provided to the council for decision-making, effectively misleading them. Council members received reports suggesting the city was breaking even or had a minor loss of $65,000, when in reality, spending was millions of dollars higher. One council member noted a report showed only $2.3 million in spending through August 2023, but the year-end total was actually $10 million.
    • Withholding Information and Open Records Issues: Several council members described a culture of non-transparency.
      • Councilwoman Yolanda Barber stated, and I witnessed her censure, as she was consistently “shut down” and “fought on every turn” when asking for financial data, to the point of having to hire her own attorney to submit a demand letter for information. She also stated it took her 10 months to receive the 2022 audit results.
      • Another council member highlighted that open records requests from the public were being redacted beyond standard practice at the direction of the legal department, without the full council’s knowledge.
      • The consensus among several council members was that despite all of them asking for financial information, the reports they received were erroneous and concealed the city’s true financial condition.

    Based on the source from the September 30 Stockbridge City Council meeting, the city’s finance director, Mr. Malazi, provided a budget update covering January through the end of August 2024. The presentation was a summary, with more detailed departmental reports and a significant budget amendment planned for October.

    Overall Financial Reporting Status

    • Catching Up: The finance department has caught up on bank reconciliations through the end of August 2024, allowing for the presentation of a credible financial report.
    • Past Misinformation: Mr. Malazi acknowledged that in the past, “two sets of reports that were being made” and the inaccurate ones were given to the council for decision-making, effectively misleading them. The current reports are intended to provide a more transparent view.
    • Upcoming Corrections: A budget amendment will be presented on October 13, 2024, to address numerous funds that had expenditures but no approved budget. This issue was previously highlighted when an audit noted over $32 million in expenditures without corresponding budgeted revenue.

    General Fund Performance (January – August 2024)

    • Budget vs. Actual: The General Fund had a budgeted revenue of $29.2 million for the year. As of the end of August, the city had collected $14.2 million. Expenditures were also at approximately $14 million.
    • Delayed Major Revenues: Mr. Malazi noted that while revenues appear low, the largest revenue streams for the General Fund arrive late in the year. These include insurance premiums ($3.5 million expected in November), property tax ($7.4 million expected in December), and sales tax.

    Issues with Unbudgeted Funds and Spending

    A significant theme of the update was the ongoing effort to correct years of spending from funds that were never formally budgeted by the council.

    • T-SPLOST: The T-SPLOST fund had a zero-dollar budget for expenditures, yet money has been spent from it. A budget amendment will correct this by formally budgeting both the revenues already collected and the expenditures.
    • ARPA Funds: The American Rescue Plan Act (ARPA) fund was budgeted with zero revenue and has shown significant expenditures. This is because the funds were improperly “co-mingled into general fund” instead of being accounted for separately. The city must continue to fund ARPA-designated projects until the program ends in 2026. Mr. Malazi confirmed that the city was previously asked to return $2.2 million due to improper accounting but was able to resolve the issue by complying with federal requirements and did not have to return the money.
    • Other Funds: Other funds, like the Property and Evidence fund and the new Red Speed fund, also had revenues or expenditures that were not included in the original 2025 budget and will be corrected via the upcoming amendment.

    Enterprise Fund Performance

    The finance director expressed concern about the performance of the city’s enterprise funds.

    • Revenues Are Down: Revenues for all enterprise funds—Water, Sewer, Sanitation, and Storm Water—are down. The department plans to assess the reasons for this decline.
    • Conference Center: The Conference Center’s expenses are inflated because personnel costs for the City Events department (approximately $500,000) are currently budgeted under the Conference Center. This will be corrected to reflect the true cost of each department.
    • Amphitheater: The Amphitheater had a budgeted revenue of $2.6 million and had collected $1 million through August, with more concerts scheduled. The budget amendment will transfer money from the General Fund to “make up for the shortfalls in revenues”.

    From the transcript of this September 30th, 2025 work session video:

    233
    00:11:49,020 –> 00:11:57,080
    There were two sets of reports that were being made, and the reports that were being given

    234
    00:11:57,080 –> 00:12:00,080
    to you to make wise decisions were not.

    235
    00:12:00,460 –> 00:12:03,420
    So we misled you.

    There must be an investigation into why two sets of books were kept, leading to a vastly over budget amphitheater, and how we’re going to claw back our money.